
Earnings Beat Could Reshape The Case For Allegro MicroSystems Stock
- Allegro MicroSystems reported Q2 fiscal 2027 sales of US$276.88 million and net income of US$23.26 million, then issued Q3 guidance for US$278 million to US$288 million of net sales, which at the midpoint implies 23% year over year growth.
- The latest quarter showed higher earnings per share, a swing from a year ago loss over the first six months, and continued momentum in automotive, industrial and AI data center demand supported by new power and sensing products.
- The next focus is on how Allegro MicroSystems' stronger guidance and AI data center traction could reshape its investment narrative.
Allegro MicroSystems Investment Narrative Recap
For Allegro MicroSystems to make sense in a portfolio, you need to be on board with its push into higher value power and sensing chips for EVs, industrial automation and AI data centers. The latest Q2 results and Q3 sales outlook keep that thesis intact in the near term. The key short term catalyst is continued execution on bookings and backlog as those orders convert into shipments and margin progress.
The biggest near term risk still revolves around demand or pricing pressure in core regions such as China and the chance that current order strength reflects some over ordering that later unwinds. The Q2 report and guidance do not remove that risk, but they also do not materially increase it based on the information disclosed.
The recent AI data center product announcement looks most relevant to the current earnings story. Allegro MicroSystems rolled out higher isolation current sensors, a Power Thru silicon carbide gate driver and an upgraded 48V motor driver aimed at dense server and high performance computing racks, with early customer traction through Acbel Polytech.
For investors, that launch helps frame why data center has become a meaningful slice of revenue and a focus in management commentary. It ties directly into the catalyst of mix shift toward higher margin current sensors and power ICs, while also introducing new execution risks around ramping complex parts into safety critical 800V systems and keeping design wins active as AI infrastructure customers refine architectures.
What Current Forecasts Assume For Allegro MicroSystems
Analyst models around Allegro MicroSystems lean heavily on long term acceleration in both revenue and profitability. The consensus view points to revenue expanding at about 18.2% a year over the next three years, with profit margins rising from 1.5% today to 22.6% in that same window. That backdrop feeds into longer dated earnings projections that anchor a lot of the discussion around what the stock already prices in.
On current estimates, earnings are projected to reach US$352.6 million by 2029, up from US$14.2 million today, which implies a very large step up in profit dollars. Some forecasters sit above that at US$474.5 million, while others see a lower US$296.2 million outcome, so there is a wide spread in possible earnings paths. Those figures also assume a modest 0.69% per year increase in the share count as Allegro MicroSystems issues new equity or stock based compensation.
Allegro MicroSystems' narrative projects US$1.6b revenue and US$352.6 million earnings by 2029. This requires 18.2% yearly revenue growth and about a 25x earnings increase from US$14.2 million today.
On these projections, the implied P/E multiple used by the analyst group would fall from about 435.4x earnings today to 39.3x earnings in 2029. That future multiple sits below the current 44.4x P/E cited for the wider US semiconductor peer set in the same report. For investors, the question is less whether Allegro MicroSystems can grow and more whether that type of profit and valuation reset feels realistic enough to underwrite with personal capital.
Uncover why Allegro MicroSystems' fair value indicates a 59% potential upside to its current price that could narrow quickly.
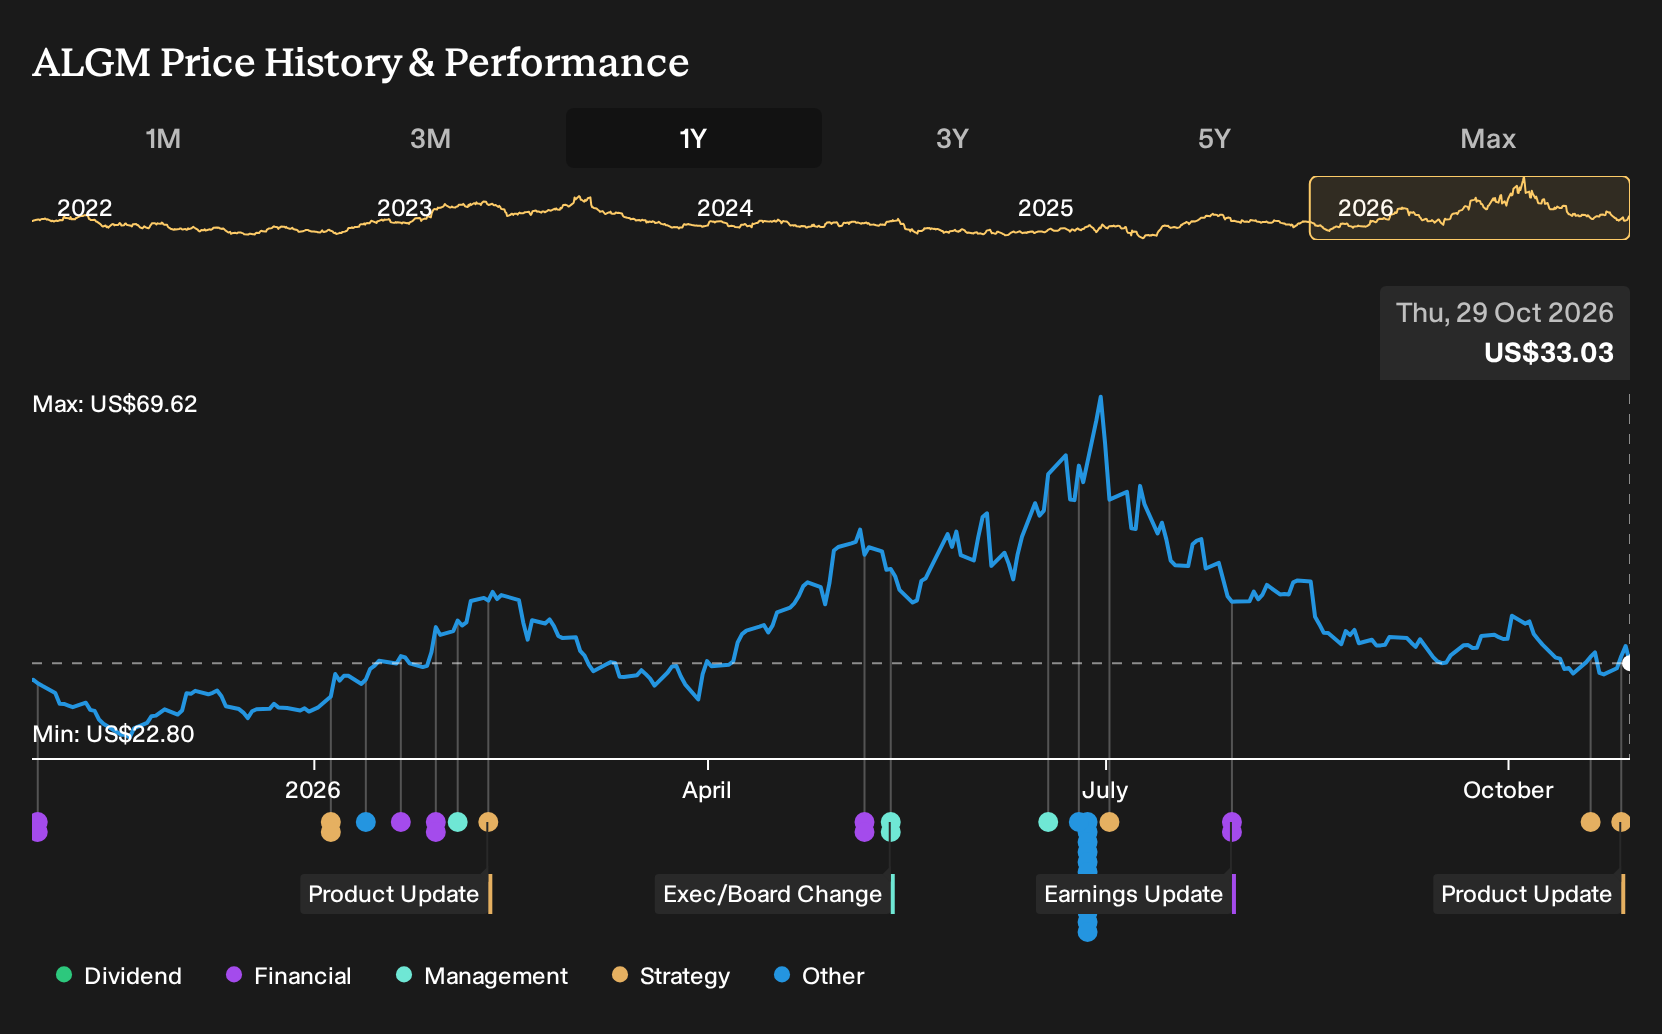
Exploring Other Perspectives
The most upbeat analysts build their case for Allegro MicroSystems around AI data center revenue. They were already modeling earnings of about US$379.2 million and a P/E of 43.1x by 2029 before this Q2 beat and 23% Q3 sales growth guidance. You can treat that AI driven story as one possible path among many and explore how different investors weigh it.
Explore 4 other Allegro MicroSystems fair value estimates, including one that suggests up to 88% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Allegro MicroSystems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Allegro MicroSystems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allegro MicroSystems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Allegro MicroSystems?
If Allegro MicroSystems has sharpened your thinking about where to put fresh capital to work, it can help to line it up against other high quality opportunities. The Simply Wall St Screener lets you quickly filter for different types of potential investments so you are not relying on a single story.
- For investors who want income first and foremost, review a set of higher yielding opportunities through 7 dividend fortresses that may suit a payout focused portfolio.
- If capital preservation is your priority, narrow your watchlist to sturdier businesses by scanning a 30 resilient stocks with low risk scores that pass tighter risk checks.
- When you want to go beyond familiar tickers, broaden your opportunity set by searching a 18 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com