
3 Japanese Growth Stocks With Earnings Growth Over 13%
Japanese interest rates are still relatively low, yet the Bank of Japan now says its 2% inflation goal has been met and is talking more openly about keeping borrowing costs higher. That combination makes fast growing companies with managers heavily invested alongside you especially interesting. This article walks through three such high growth Japanese stocks where insiders have significant skin in the game and explains why they merit a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the names that matter most, these 26 high growth high conviction stocks are the strongest companies we've found.
Kotobuki Spirits (TSE:2222)
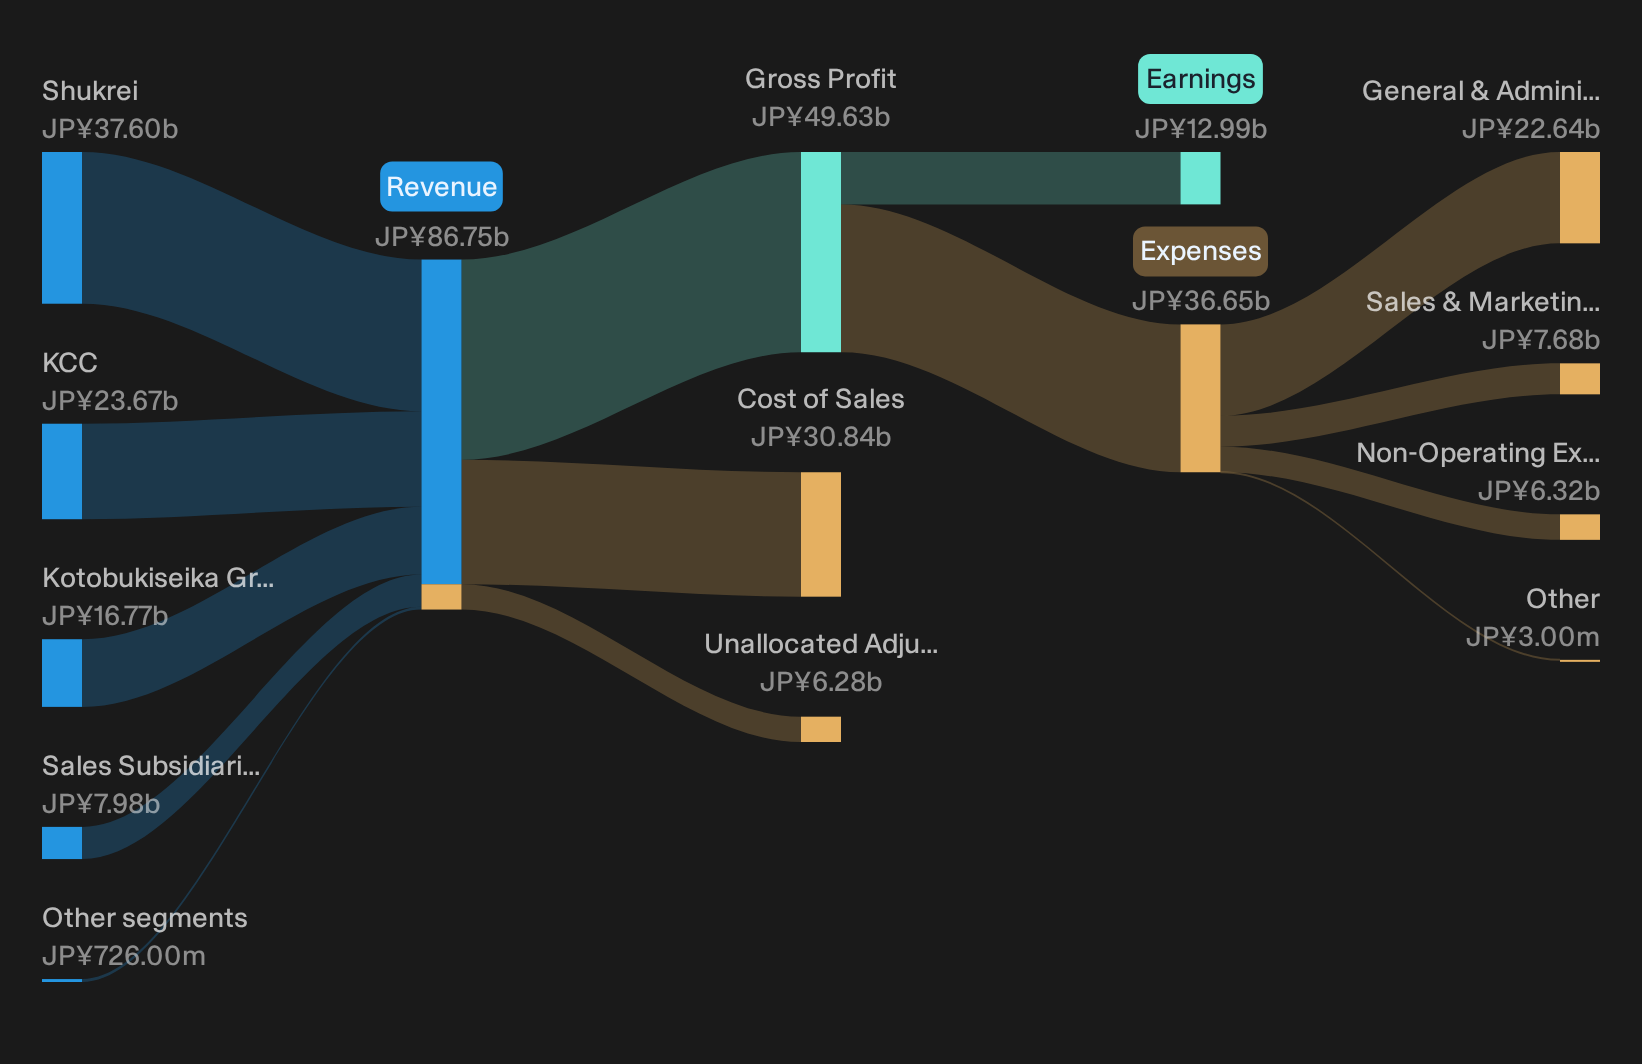
Kotobuki Spirits is a long established Japanese confectioner whose sweets and baked goods are the main engine of its growth story, supported by smaller operations such as insurance agency services. It generated about ¥37.6b from Shukrei, ¥23.7b from KCC and ¥16.8b from the Kotobukiseika Group, and the stock is valued around ¥377.2b.
Investors looking at fast growing stocks with aligned insiders may find Kotobuki Spirits interesting. Its core sweets business sits at the center of management’s growth push, backed by guidance for rising sales, solid profit targets and a new interim dividend policy that signals confidence while leaving one key pressure on future margins unresolved.
That unresolved margin pressure is exactly why investors are scrutinising the 4 key rewards and 1 important warning sign, which shows where ambition could be stretched or still underappreciated.
Sansan (TSE:4443)
Sansan runs a cloud platform that turns business-card and contact data into shared sales intelligence, backed by Bill One and Contract One. It generated about ¥48.9b from Sansan/Bill One, ¥7.1b from Eight and ¥0.4b from Others, all in Japan, and the stock is valued around ¥268.5b.
Sansan fits directly into the screener theme, with its contact-management cloud associated with recurring revenue potential and management guiding to higher sales and earnings. Recent Q1 FY2026 results and the dividend outlook support that view. However, everything still depends on how one quiet pressure shapes the next stage of growth.
That quiet pressure is worth unpacking further. The 3 key rewards and 1 important warning sign puts Sansan’s recurring potential and the less obvious friction points side by side.

Micronics Japan (TSE:6871)
Micronics Japan focuses on semiconductor probe cards and test equipment that help chip makers improve yields, backed up by smaller TE and inspection tools. Probe Card Business generated about ¥84.9b in revenue versus ¥1.4b from TE Business, and the stock is valued around ¥480.4b.
Micronics Japan ties cleanly into the screener theme through its semiconductor probe card and test gear, where earnings grew 89.4% year over year and management is guiding to higher sales, profits and dividends. Growth investors still need to watch what happens when memory semiconductor demand shifts direction.
When memory demand turns, see the 2 key rewards and 1 important major warning sign to spot where Micronics Japan’s upside could be accelerating while pressure points remain underappreciated.

Seeking Alternatives Before The Crowd
Fresh ideas move first, and late money often chases breakouts after the best entry point has already dropped out of reach. Scan under the radar for now and act early instead of following the crowd.
- Spot resilient cash generators by scanning a curated list of solid balance sheet and fundamentals (23 results) before momentum stories start flying on every headline.
- Ride powerful secular shifts by checking the hand picked 54 AI infrastructure stocks that supports the hardware and energy backbone behind artificial intelligence growth.
- Target structural demand in energy and defense by reviewing the focused 16 nuclear energy infrastructure stocks while the sector is still building quiet momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com