
How Tenant Rent Fears At Sabra Health Care REIT (SBRA) Have Changed Its Investment Story
- Sabra Health Care REIT is in focus after Medical Properties Trust reported a rent shortfall from tenant HSA, which pulled attention to tenant payment reliability across health care real estate owners.
- The key issue for Sabra is whether its own operator base and lease structures can absorb sector anxiety around unpaid rent without disrupting day-to-day cash generation.
- We will now look at how Sabra Health Care REIT's investment narrative compares with the renewed concern over tenant rent collection risk.
Stress test your approach to Sabra Health Care REIT by comparing it with a curated group of landlords focused on tenant quality and resilient balance sheets through our list of solid balance sheet and fundamentals (23 results).
Sabra Health Care REIT Investment Narrative Recap
To own Sabra Health Care REIT, you really have to believe the managed senior housing push and portfolio recycling can turn into steady, repeatable cash flows even as the sector debates tenant credit risk again. The short term swing factor is whether Sabra’s operators keep paying on time and maintain occupancy while management is still re tenanting assets like the Avamere portfolio.
The biggest near term risk is strain on retained cash. Sabra is funding a large SHOP focused pipeline while dealing with items like the US$102.4 million loan loss reserve and interest costs that are not well covered by earnings. If tenant issues similar to HSA spread into Sabra’s base, that pressure would only increase.
Without a fresh headline tied directly to this Medical Properties Trust news, the most relevant reference point is Sabra’s ongoing shift toward SHOP, with over 95% of more than US$1b of active opportunities tied to managed senior housing. For this model to work, tenant performance needs to hold up so those properties keep supporting occupancy, RevPOR and cash NOI.
That same SHOP pivot also intersects with the rent collection story. Managed senior housing puts Sabra closer to day to day operations, which can help monitor trends in real time but also exposes the REIT to higher operating complexity and costs. For you, the key watch items around the next print are tenant level health, any new loan reserves and how much balance sheet flexibility Sabra retains for further investment.
Sabra Health Care REIT’s current analyst storyline points to about US$1.2b of revenue and US$243.7 million of earnings by 2029, built on forecast revenue growth of 10.1% each year and an earnings increase of roughly US$178 million from today’s US$65.4 million level.
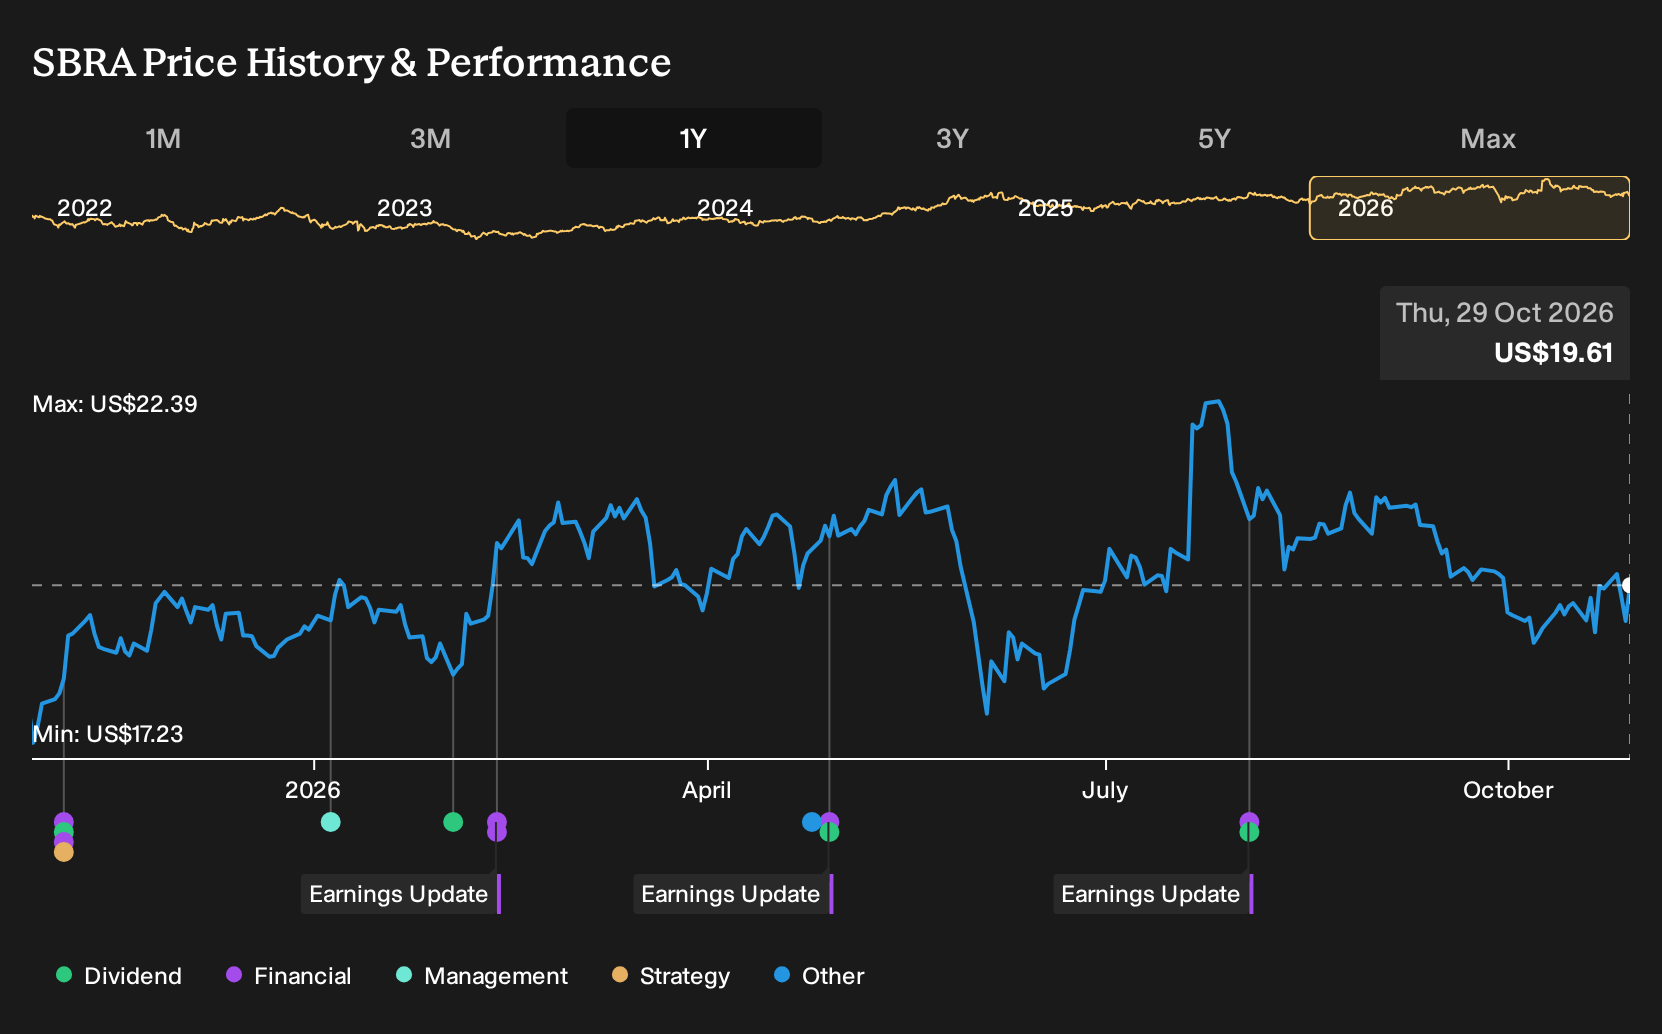
Uncover why Sabra Health Care REIT's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community provides two fair value views for Sabra Health Care REIT, and they are far apart, ranging from US$22.79 to US$56.67 per share. That spread leaves considerable room for different conclusions, especially with portfolio reshuffling and tenant transitions that could either support earnings resilience or strain cash and rent coverage. Readers may wish to compare several of these perspectives before deciding how much tenant risk they are comfortable holding.
Explore another Sabra Health Care REIT fair value estimate, including one that suggests it could be worth just $22.79.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sabra Health Care REIT research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Sabra Health Care REIT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sabra Health Care REIT's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sabra Health Care REIT?
If you want to pressure test your view on Sabra Health Care REIT against other opportunities, it can help to scan a wider field of potential holdings with different risk and income profiles.
- If you care most about balance sheet strength and staying power through tougher periods, start with our 30 resilient stocks with low risk scores that score well on resilience.
- For investors who want a mix of quality and attractive pricing, review our 30 high quality undervalued stocks that blend solid fundamentals with more modest expectations baked into the share price.
- If you are hunting for less crowded opportunities with room for a fresh thesis, consider our 18 high quality undiscovered gems that combine strong financials with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com