
Vusion Stock In Focus After 2026 Revenue Growth Outlook
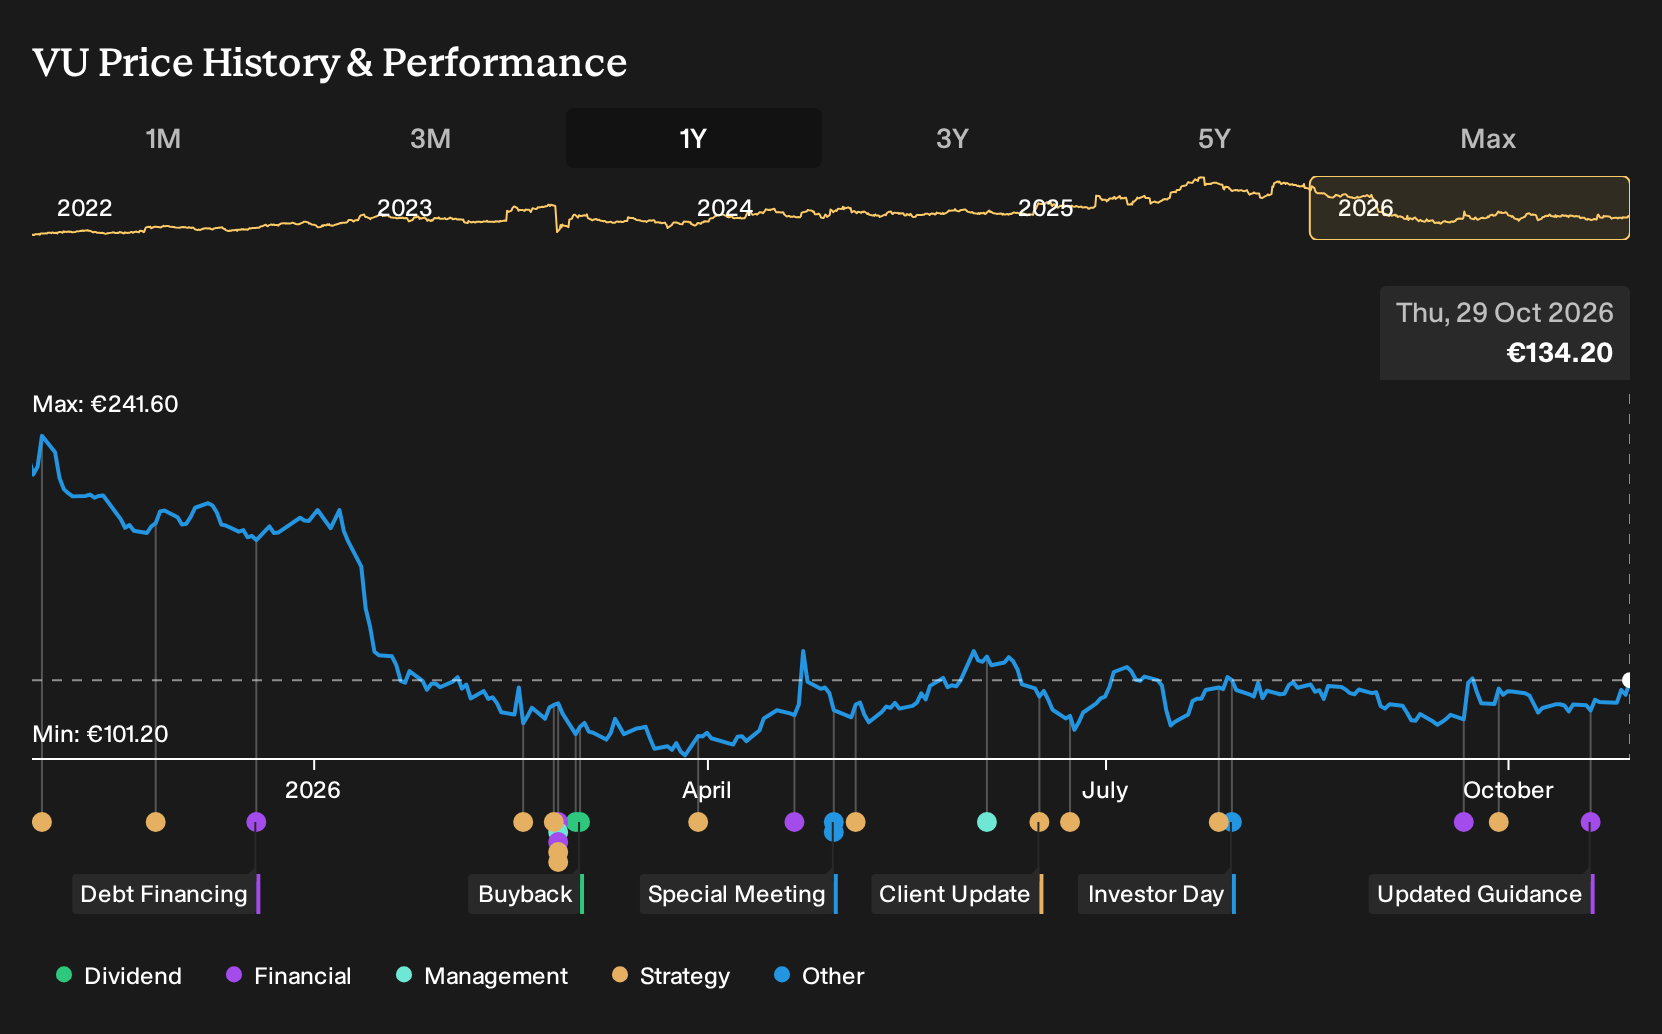
- Vusion S.A. has issued revenue guidance for 2026, indicating an expected group top line increase of 15% to 20% versus 2025 at constant euro dollar exchange rates.
- This quantified outlook gives investors a clearer view of Vusion's demand pipeline and execution priorities across its commerce digitalization activities.
- This development also shows how Vusion's broader investment narrative is influenced by management targeting 15% to 20% revenue expansion in 2026.
Scan beyond Vusion's 2026 guidance and line up other potential digital commerce beneficiaries by reviewing the hand picked 607 high quality undiscovered gems that might be building similar pipelines under the radar.
Vusion Investment Narrative Recap
To back Vusion, you need to believe physical retail keeps investing in digital shelves, data rich store networks and higher margin software like VAS, VusionCloud and EdgeSense. The 2026 revenue guidance of 15% to 20% growth at constant euro dollar terms points to management planning for continued demand across these offerings.
For the near term, the key swing factor remains execution on large contracts such as Walmart and follow on deals in new verticals and regions. The biggest risk still sits with concentration and rollout timing, especially after past regional lumpiness and the pressure that forecast earnings declines over the next 3 years may put on sentiment.
The most relevant recent reference point for this guidance is management’s earlier indication that adjusted revenue could reach €1.4b in 2025, driven by strong orders and major wins like Walmart. The new 2026 top line range now frames what comes after that expected step up, giving you another data point on management’s growth ambition.
Putting these together, the story now hinges on two execution threads. First, whether Vusion converts its retail IoT platform, including EdgeSense and VusionCloud, into a larger base of recurring, higher margin VAS. Second, whether it can broaden beyond Walmart, smooth regional volatility and offset earnings that analysts expect to decline on average over the next 3 years.
Vusion's narrative projects €1.8b revenue and €195.0 million earnings by 2029. This assumes 6.6% yearly revenue growth and about €51.7 million earnings increase from €143.3 million today.
Uncover why Vusion's fair value indicates a 56% potential upside to its current price, which investors may view as a window that narrows quickly.
Exploring Other Perspectives
One optimistic twist in the alternate Vusion view sits in the backlog. Bullish analysts saw the weighted pipeline and order book as strong enough to support 10.9% yearly revenue growth and about €251.2 million in 2029 earnings, versus consensus nearer €195.0 million. Both sets of forecasts predate the new 2026 guidance, so you should expect opinions and models to evolve, and you should compare several angles before leaning on any single narrative.
Explore 3 other Vusion fair value estimates, including one that suggests potential upside of up to 92% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vusion research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vusion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vusion's overall financial health at a glance.
Looking For More Ideas Beyond Vusion?
If you are weighing Vusion against other opportunities, it can help to scan a broader field of companies that share similar financial traits or risk profiles. The Simply Wall St Screener is built for that kind of quick comparison, so you can line up alternatives before committing fresh capital.
- If resilience matters most to you, focus on businesses that aim to limit downside with steadier fundamentals by starting with the 228 resilient stocks with low risk scores.
- If balance sheet strength is your filter, concentrate on companies that pair manageable debt with solid cash positions through the list of solid balance sheet and fundamentals (207 results).
- If you are hunting for ideas that are not widely followed, broaden your watchlist with the 607 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com