
Lucid Group (LCID) Could Be 79% Undervalued As Uber And Nuro Deal Lands
Why Lucid Group’s Uber and Nuro deal matters now
Lucid Group (LCID) moved into the spotlight after announcing a partnership with Uber and Nuro that combines a planned US$300 million Uber investment with a pledge to deploy at least 20,000 Lucid Gravity robotaxis.
This fresh agreement arrives just ahead of Lucid Group’s 9 November 2026 earnings release, so investors are weighing the potential revenue from future autonomous ride hailing activity against ongoing questions about cash burn and past inventory write downs.
For context, Lucid Group’s share price has retreated sharply despite the Uber and Nuro announcement, with the stock down 56.64% on a 90 day share price return basis and the 5 year total shareholder return down 99.14%. This signals fading momentum even as new partnerships aim to reset the story.
Look beyond Lucid Group and this Uber and Nuro headline by comparing it with 18 high quality undiscovered gems that also pair ambitious narratives with strong underlying fundamentals.
The Uber and Nuro headline has not stopped Lucid Group’s share price slide. That leaves a simple tension: Are investors finally pricing in the underlying business, or has sentiment swung too far against it as the valuation now suggests?
Most Popular Narrative: 79% Undervalued
Lucid Group’s most followed narrative pegs fair value at $15.50 versus a last close of $3.20. The market price therefore sits well below what bullish models imply when using a 12.54% discount rate.
The midsize Cosmos and Earth platform, engineered for roughly 60 to 70% unit cost cuts versus Gravity while targeting about 10% better miles per kWh than key rivals and ramping through 2027, gives Lucid Group room for a different mix of lower priced, higher volume vehicles that could shift the revenue and gross margin profile faster than current expectations.
See why 8 investors see Lucid Group as 79% undervalued.
Result: Fair Value of $15.50 (UNDERVALUED)
Still, chronic cash burn, along with recent weak production and delivery trends, could pressure Lucid Group’s liquidity plan and force tougher funding decisions sooner than bulls expect.
Find out about the key risks to this Lucid Group narrative.
Another View on Lucid Group’s Valuation
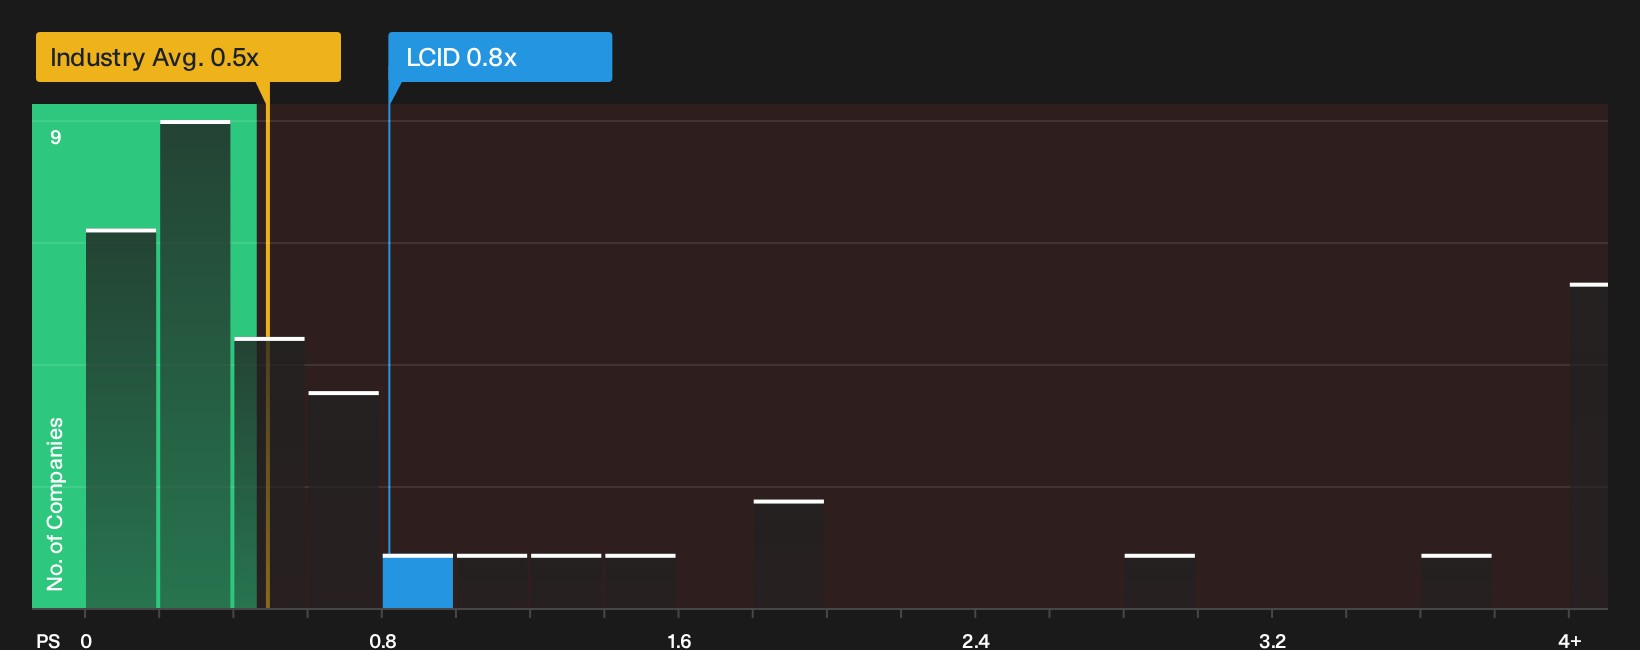
The $15.50 fair value narrative presents Lucid Group as heavily undervalued, yet the market is assigning a very different valuation. On a P/S ratio of 0.8x, the stock trades at a higher multiple than the US Auto industry at 0.5x and above peer averages at 0.4x, while the fair ratio model points to 0x.
In other words, the share price already reflects a premium to sector and peer sales multiples, even as the fair ratio suggests the market could move toward pricing Lucid Group on effectively zero sales value. This raises a direct question for investors: Is this an early re-rating, or is valuation risk building in plain sight?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Lucid Group after all of this, or feeling that sentiment has swung too far in one direction? Act quickly, review the underlying data, and weigh both sides of the story by starting with 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Lucid Group?
Lucid Group may be front of mind today, but your portfolio benefits when you keep scanning for fresh, data backed opportunities that fit your own playbook.
- Target potential mispricing by reviewing companies our filters highlight as attractively valued through the 30 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with cleaner finances using the list of solid balance sheet and fundamentals (23 results).
- Boost your income watchlist by zeroing in on companies with higher yields through the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com