
UK Growth Leaders: Elixirr International And 2 Insider-Owned Stocks
The UK market has been experiencing some turbulence, with the FTSE 100 and FTSE 250 indices slipping amid concerns over weak trade data from China, highlighting the global interconnectedness of economies. In such a climate, companies with strong growth potential and high insider ownership can be particularly appealing as they may indicate confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TPXimpact Holdings (AIM:TPX) | 19.5% | 106% |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.5% | 22.4% |
| Hochschild Mining (LSE:HOC) | 38.3% | 21.6% |
| Gulf Keystone Petroleum (LSE:GKP) | 12.6% | 21.1% |
| FDM Group (Holdings) (LSE:FDM) | 17.8% | 44.6% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 104.2% |
| Crimson Tide (AIM:TIDE) | 33% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
Let's uncover some gems from our specialized screener.
Elixirr International (LSE:ELIX)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Elixirr International plc is a management consultancy firm operating in the United Kingdom, the United States, and internationally, with a market capitalization of £258.22 million.
Operations: The company generates £167.15 million in revenue from its management consulting services across the UK, US, and other international markets.
Insider Ownership: 34.8%
Earnings Growth Forecast: 16.6% p.a.
Elixirr International exhibits strong growth potential with earnings forecasted to increase by 16.65% annually, outpacing the UK market's 10.7%. Despite an unstable dividend track record, it trades at a significant discount of 73.4% below its estimated fair value, suggesting good relative value compared to peers. Recent half-year results show sales rising to £88.96 million from £71.41 million and net income increasing modestly, reinforcing its growth trajectory amidst high insider ownership dynamics.
- Get an in-depth perspective on Elixirr International's performance by reading our analyst estimates report here.
- Our valuation report unveils the possibility Elixirr International's shares may be trading at a discount.
easyJet (LSE:EZJ)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: easyJet plc is a low-cost airline carrier operating in Europe with a market cap of £5.09 billion.
Operations: The company generates revenue primarily from its airline operations (£8.97 billion) and EasyJet Holidays (£2.06 billion).
Insider Ownership: 15.6%
Earnings Growth Forecast: 20.4% p.a.
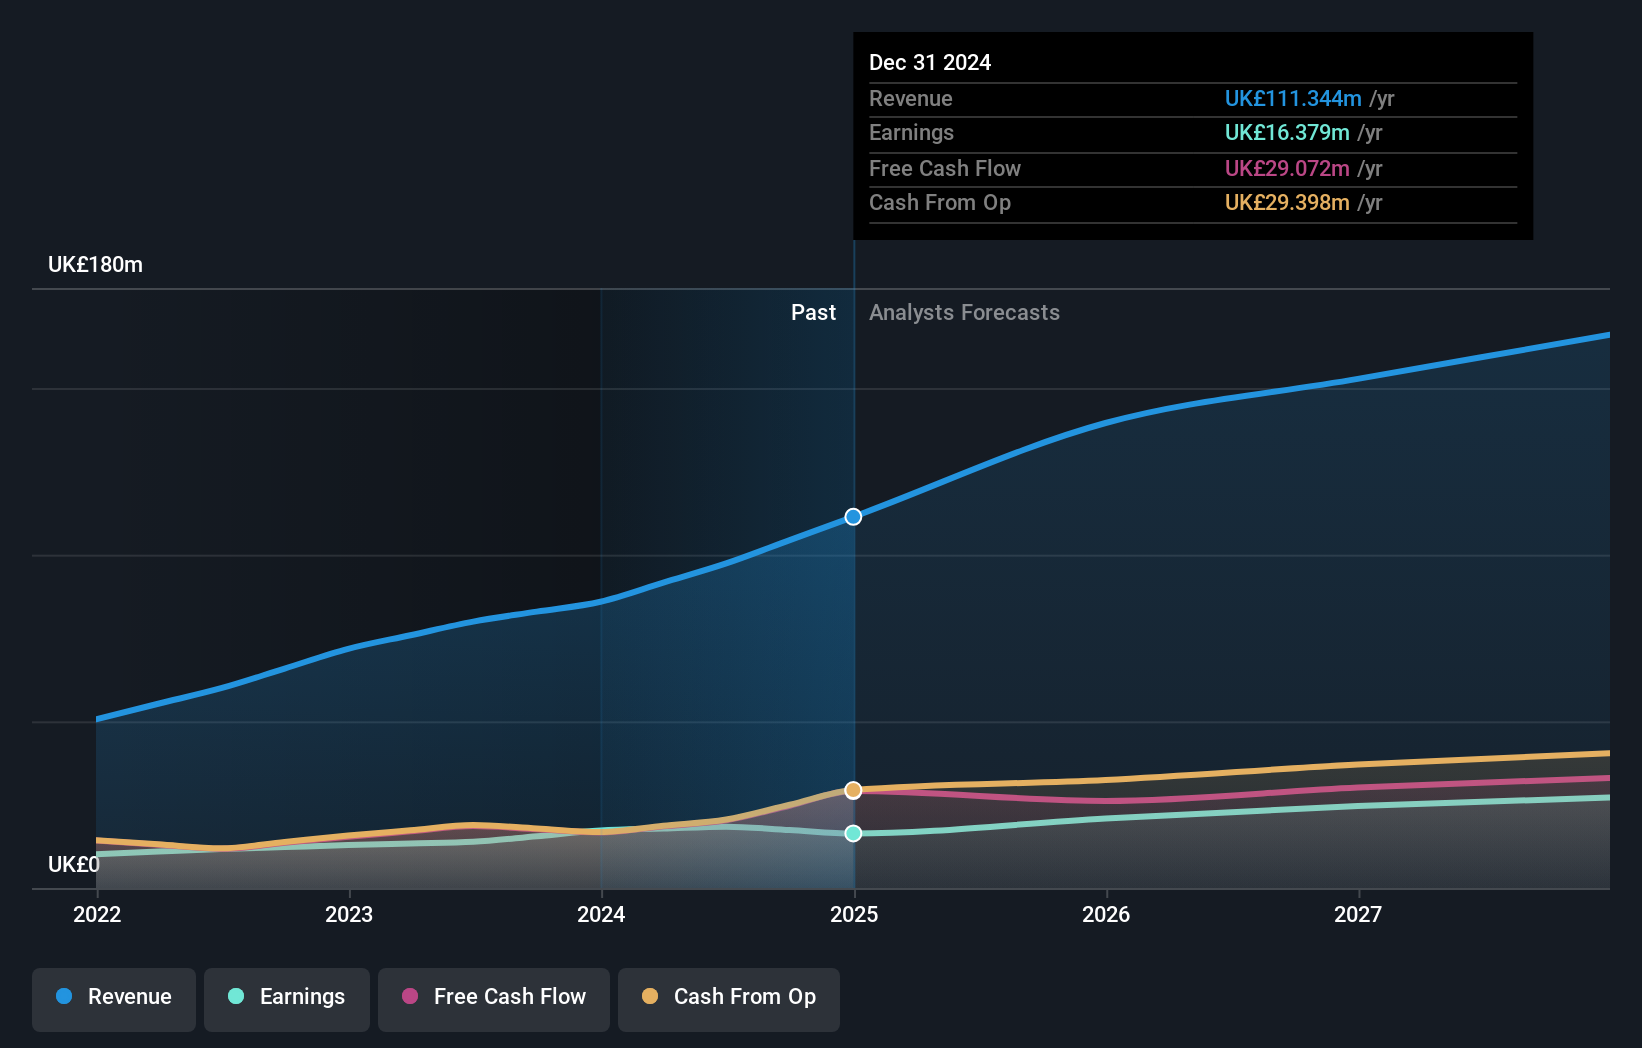
easyJet is poised for growth with earnings projected to rise 20.4% annually, outpacing the UK market's 10.7%. Despite being dropped from the FTSE 250 Index, it was recently added to the FTSE 100 Index, indicating a shift in market perception. Its price-to-earnings ratio of 12.3x suggests good value relative to the broader UK market at 16.4x. Revenue growth forecasts at 7.8% annually surpass the UK average but remain below high-growth benchmarks.
- Click to explore a detailed breakdown of our findings in easyJet's earnings growth report.
- According our valuation report, there's an indication that easyJet's share price might be on the expensive side.
Beauty Tech Group (LSE:TBTG)
Simply Wall St Growth Rating: ★★★★★☆
Overview: The Beauty Tech Group plc, along with its subsidiaries, offers at-home beauty devices across the United States, Canada, the United Kingdom, Ireland, Europe, Asia, and other international markets with a market cap of £526.76 million.
Operations: The company's revenue segments include Tria Laser at £3.01 million, Ziip Beauty at £14.58 million, and Currentbody skin at £147.81 million.
Insider Ownership: 19.5%
Earnings Growth Forecast: 23.8% p.a.
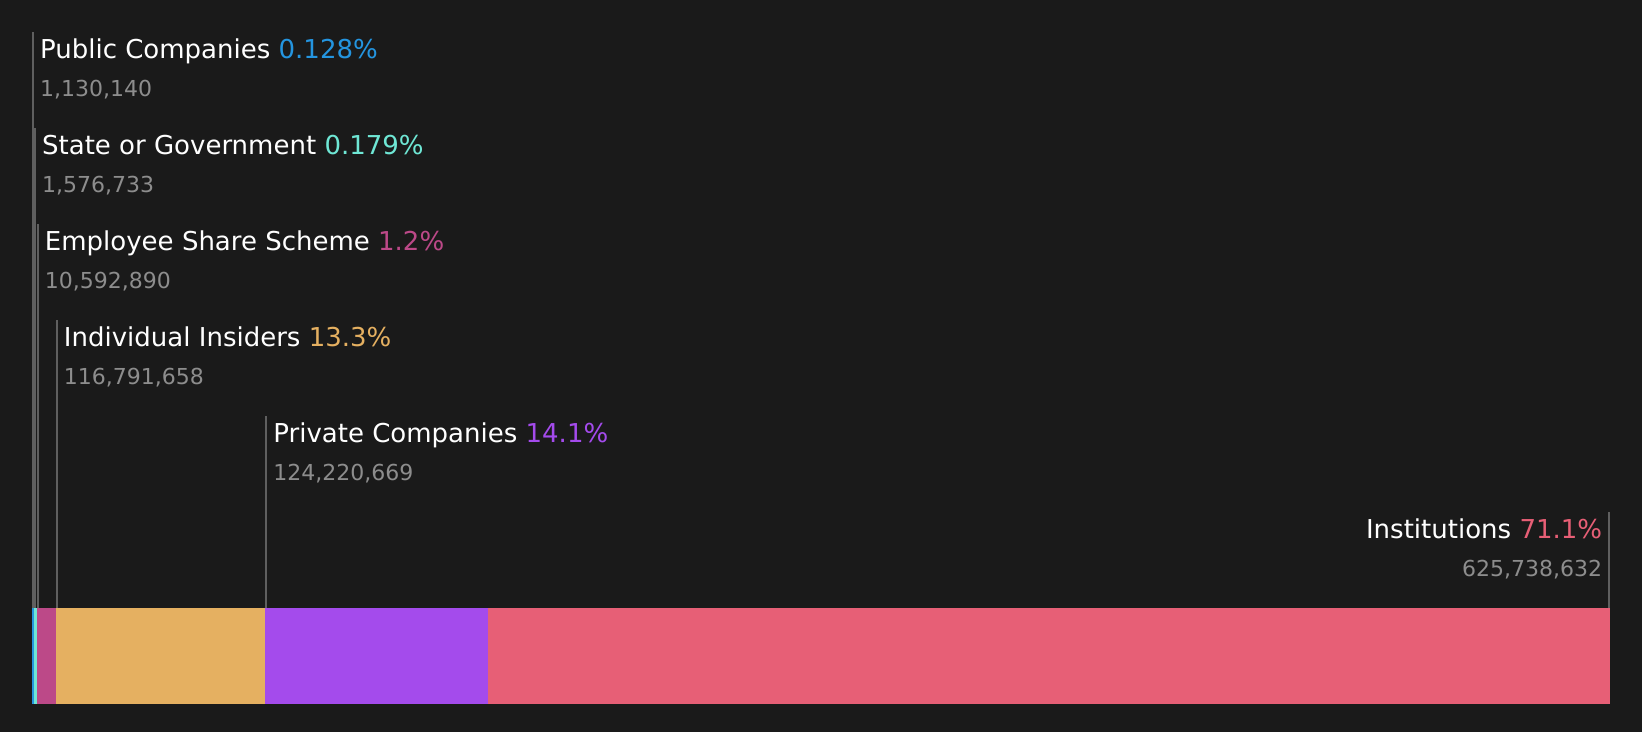
Beauty Tech Group demonstrates strong growth potential with earnings expected to increase significantly at 23.8% annually, surpassing the UK's average of 10.7%. Revenue is forecast to grow at 11.7% per year, which is above the market rate but below high-growth benchmarks. Recently, the company initiated a £20 million share buyback program aimed at reducing share capital, signaling confidence in its valuation as it trades nearly 29% below estimated fair value.
- Click here and access our complete growth analysis report to understand the dynamics of Beauty Tech Group.
- Our valuation report unveils the possibility Beauty Tech Group's shares may be trading at a premium.

Summing It All Up
- Reveal the 65 hidden gems among our Fast Growing UK Companies With High Insider Ownership screener with a single click here.
- Interested In Other Possibilities? We've found 9 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com