
Amundi (ENXTPA:AMUN) Following Strong Q3 Results Is The Undervalued View Still Intact
How Amundi’s Q3 earnings reset the conversation
The latest earnings release for Amundi (ENXTPA:AMUN) put fresh numbers behind the story. Q3 2026 brought higher revenue, a sharp jump in net income, and a sizeable uplift in earnings per share.
For the quarter to 30 September 2026, Amundi reported revenue of €908 million compared with €815 million a year earlier. Net income was €675 million versus €249 million in the same period, while basic earnings per share from continuing operations reached €3.27 compared with €1.21 a year ago.
Looking at the first nine months of 2026, revenue came in at €2.743b against €2.428b for the prior year period. Net income over those nine months was €1.428b compared with €1.246b, with basic earnings per share from continuing operations at €6.92 versus €6.07.
Management commentary around the Q3 2026 earnings call points to adjusted net income growth of more than 20% year on year. This was backed by net inflows of €46b in the quarter and €102b across the first nine months. That flow picture, spread across client segments and geographies, sits alongside higher revenue and earnings metrics and gives investors more building blocks to assess the current business trajectory.
Amundi’s Q3 release and earnings call arrived alongside a 1-day share price return of 1.96% and a 7-day gain of 3.88%. The 90-day share price performance is down 3.5%, while the 1-year total shareholder return of 48.58% and 3-year total shareholder return of 107.73% suggest momentum has been strong over longer holding periods.
Spot opportunities beyond Amundi by scanning 607 high quality undiscovered gems, which have been curated for strong fundamentals and the potential to move when the market pays attention.After a strong run over 1 year but a softer 3 month patch, Amundi now forces a practical decision. Is this the moment to commit fresh capital, or does patience for a cheaper entry make more sense given the current valuation metrics?
Most Popular Narrative: 5% Undervalued
Set against Amundi’s last close at €91.05, the most followed narrative points to a fair value of €96.20 and uses a 9.75% discount rate to tie the current price back to its long term earnings power.
The main thing that has to go right is that Amundi converts strong net inflows in areas like ETFs, technology services, Asia and private assets into durable fee and platform revenues that more than offset outflows from legacy partnerships and slight fee margin dilution.
The current valuation implies the market already prices Amundi as fairly valued with expectations for continued solid profitability and capital returns, rather than assuming a distressed scenario or a high growth premium.
See why 22 investors see Amundi as 5% undervalued.
Result: Fair Value of €96.20 (UNDERVALUED)
Still, the story around Amundi can change quickly if the French exceptional tax contribution lands on profits, or if fee margins compress faster than inflows can offset them.
Find out about the key risks to this Amundi narrative.
Another View on Amundi’s valuation
The earlier narrative leans on a fair value of €96.20. A different lens comes from Simply Wall St’s DCF model, which points to a future cash flow value of €89.37 against today’s €91.05 share price. That suggests a slight premium. Which signal should carry more weight for you?
For readers who want to see how that cash flow based estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
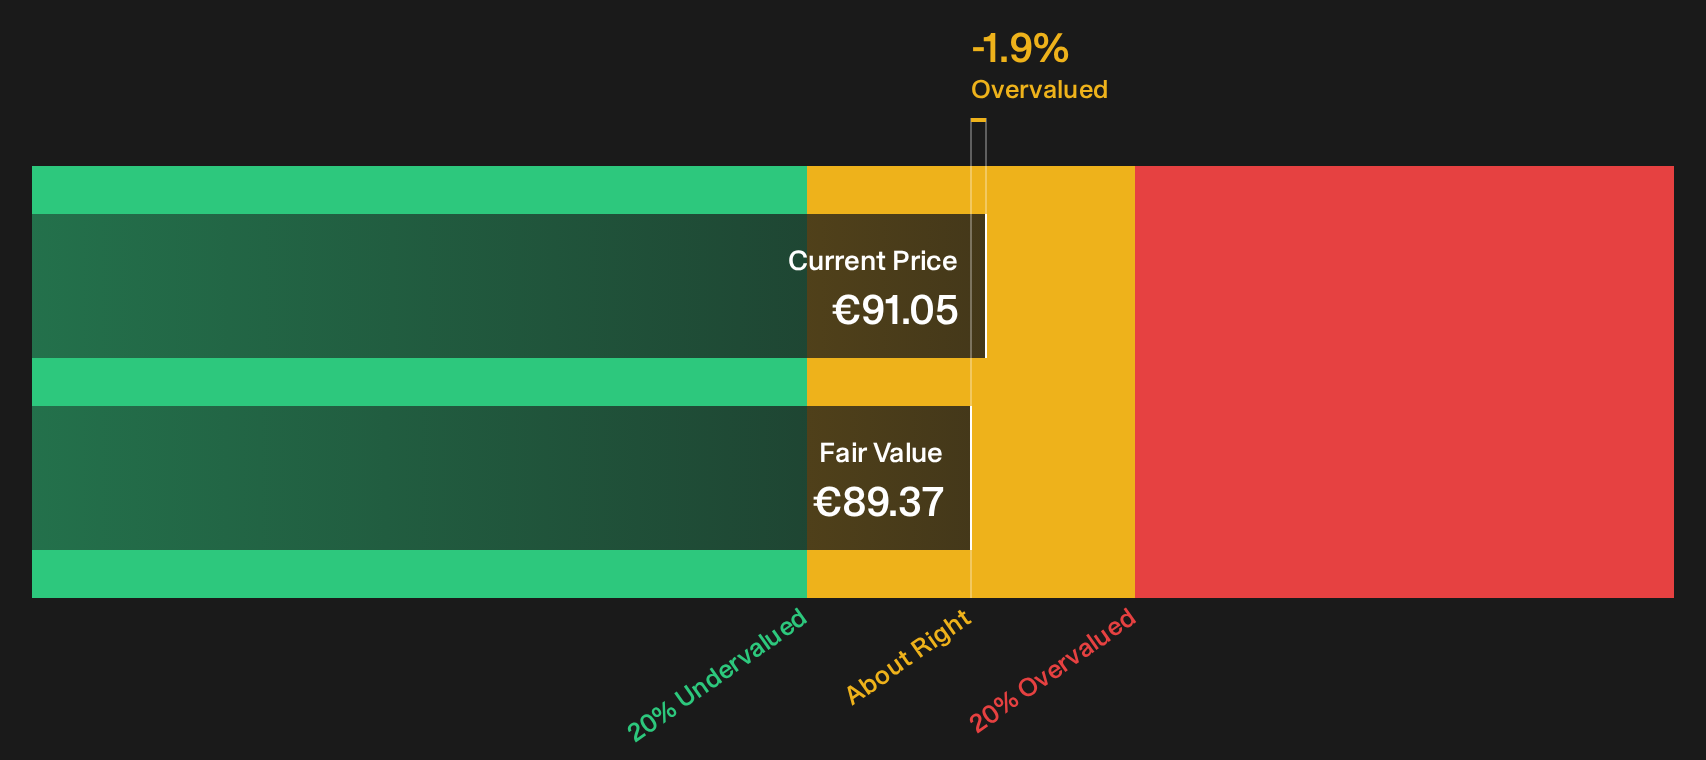
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amundi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Optimistic about Amundi yet cautious after the tax and fee margin flags. Act while the data is fresh and weigh both sides using the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Amundi?
If you stop with Amundi, you risk missing other opportunities that fit your style, so put fresh ideas on your radar using the Simply Wall St screener.
- Target resilient performers by checking out 228 resilient stocks with low risk scores that may help steady your portfolio when volatility picks up.
- Lock in potential cash flow by scanning 228 dividend fortresses that focus on income strength and payout resilience.
- Spot quality at a better price by reviewing the 195 high quality undervalued stocks before the rest of the market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com