
Learn Why The Bull Case For Telecom Italia Stock Could Change Following Leadership Reshuffle
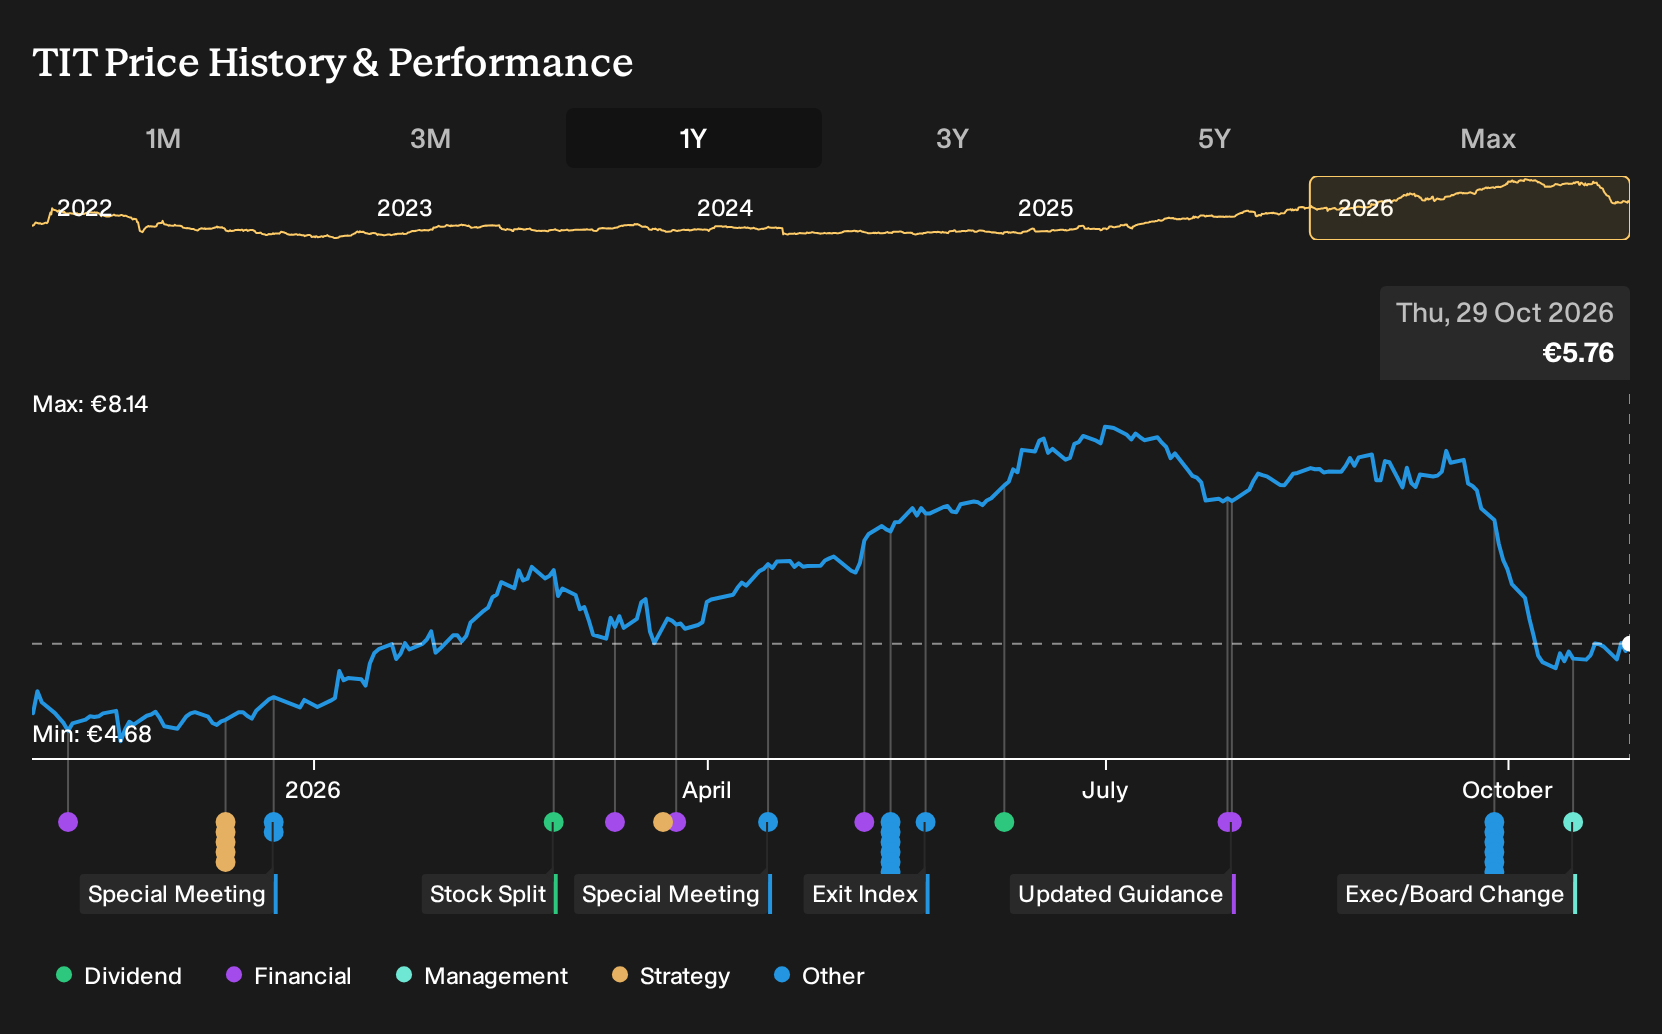
- Telecom Italia has reshaped its leadership after the voluntary departures of senior executives Elio Schiavo and Leonardo de Carvalho Capdeville, putting a fresh management team in place and increasing focus on how priorities are set and executed.
- The refreshed executive lineup focuses investor attention on whether Telecom Italia can maintain cost discipline and deliver on operational plans that some already view as out of step with the current valuation.
- We will now look at how Telecom Italia's refreshed leadership and emphasis on execution could reshape the investment narrative for the business.
Scan how investors are pricing leadership change at Telecom Italia, then compare it with other potential mispriced opportunities in our curated list of 195 high quality undervalued stocks.
Telecom Italia Investment Narrative Recap
To own Telecom Italia, you need to believe the business can keep tightening costs, lean on higher value connectivity and enterprise services, and keep TIM Brasil delivering steady cash while competition in Italy remains intense. The leadership reshuffle does not change those core levers, but it does put more attention on whether execution can stay consistent through a transition.
In the near term, the key swing factor is whether management holds the line on the cost transformation and capital structure work that support equity free cash flow. The biggest risk is still financial pressure, since interest costs are not well covered by earnings and any slip in cash generation could slow deleveraging.
Against that backdrop, the cost program and operating targets already laid out for Telecom Italia look even more important after the management change. Domestic EBITDA after lease was reported up 7.1% in the first half of 2026, with FiberCop related operating expenses down about 11 to 12%, and the refreshed leadership now has to keep those numbers on track.
Management has also outlined AI driven automation goals such as handling about half of inbound calls and 70% of back office tasks by 2027, which is central to the efficiency story investors are watching. If the new executive team delivers on that operational roadmap while TIM Brasil keeps contributing cash, it would directly influence how quickly the balance sheet pressure can ease.
Telecom Italia's current analyst narrative points to revenues of €15.1 billion and earnings of €726.1 million by 2029, built on an assumed 2.4% yearly revenue growth rate and a move from €284.0 million in earnings today to the 2029 consensus, which is an earnings increase of about €442 million.
Uncover how Telecom Italia's fair value indicates a 14% potential upside to its current price before other investors close that discount.
Exploring Other Perspectives
One alternate view treats Telecom Italia’s leadership change as a catalyst for a sharper earnings reset rather than extra cost progress. The most bullish analysts were already pencilling in €15.9b of revenue and €1.1b of earnings by 2029. That is far above the roughly €15.1b and €726.1m that consensus was using before this news, which shows how wide opinion can run and why it can be useful to compare several narratives before deciding what this reshuffle might mean for you.
Explore 2 other Telecom Italia fair value estimates, including one that suggests as much as 48% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Telecom Italia research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Telecom Italia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telecom Italia's overall financial health at a glance.
Looking For More Ideas Beyond Telecom Italia?
Once you have a view on Telecom Italia, it can help to widen the lens and compare it with other companies that fit different risk and return profiles. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, income focus, or potential mispricing.
- If capital preservation comes first for you, start with companies that score well on stability and resilience through the 228 resilient stocks with low risk scores.
- If you want to focus on businesses with robust finances, move across to companies with cleaner balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (207 results).
- If you are hunting for opportunities the market may be overlooking, scan through a curated pool of potential mispriced candidates using the 607 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com