
3 British Nuclear Stocks To Watch In October 2026
Oil prices are heading for a fourth straight monthly gain as conflict in the Middle East highlights how fragile global fuel supply can be. That sort of shock tends to push governments back toward stable, low carbon baseload power. For you, that shines a spotlight on United Kingdom listed nuclear energy companies. This article walks through three stocks from our specialist screener that offer focused exposure to that theme.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium production, fuel enrichment and reactor operators that provide reliable, sustainable power. However, if you want the absolute best, these 16 nuclear renaissance stocks are the cream of the crop.
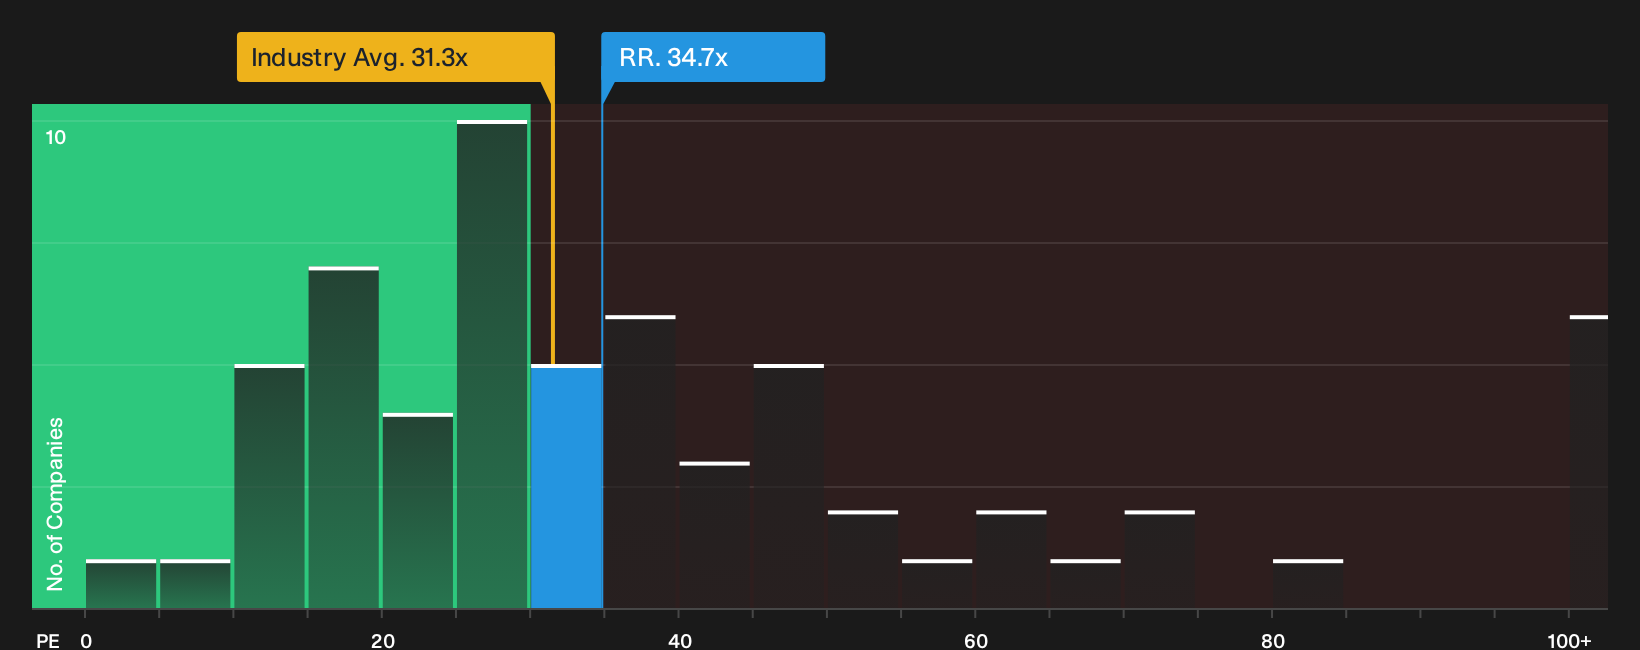
Rolls-Royce Holdings (LSE:RR.)
Overview: Rolls-Royce Holdings designs mission-critical power systems, with its Defence segment providing submarine nuclear power plants and small modular reactor technology alongside larger civil aerospace and power businesses.
Operations: Rolls-Royce generates about £11.8b from Civil Aerospace, £5.5b from Power Systems and £5.0b from Defence, with minor other items.
Market Cap: £105.5b
For the Nuclear Energy Stocks theme, Rolls-Royce matters because its work on submarine reactors and small modular reactors gives you exposure to real nuclear hardware rather than just fuel or infrastructure suppliers.
"Rolls-Royce SMR has secured multi-country selections and is already in execution for units in the UK, Sweden and the Czech Republic while aiming to commission up to 2 small modular reactors per year in the mid 2030s and up to 8 per year at maturity, creating a potential new source of high margin revenue and profit growth."
The real swing factor for Rolls-Royce in this theme is how one unresolved cost and funding pressure ultimately feeds through to long-term margins.
That funding question is exactly what sits at the centre of the full narrative for Rolls-Royce Holdings, which breaks down how those pressures could reshape the nuclear opportunity for Rolls-Royce Holdings.
National Atomic Company Kazatomprom JSC (LSE:KAP)
Overview: National Atomic Company Kazatomprom JSC is a Kazakhstan based uranium producer that supplies nuclear fuel feedstock alongside smaller rare metals and services operations.
Operations: The group generates about KZT 1,697,002 million from Uranium, KZT 90,728 million from Ulba Metallurgical Plant and KZT 294,086 million from other activities.
Market Cap: US$16.7 billion
Kazatomprom matters for this nuclear energy screen because its uranium mines and processing assets sit at the very start of the fuel chain that powers reactors worldwide.
"Global structural undersupply of uranium driven by increasing nuclear build-outs, plant lifespan extensions, and a lag in bringing new projects online is supporting a multi-year demand upcycle. This is positioning Kazatomprom for sustained pricing power and higher sales volumes, which is positive for revenue and margin growth."
The real question for investors is how long that favourable uranium backdrop can outweigh rising cost pressures and capital demands on the business.
That balance of uranium strength and rising costs is exactly what the full narrative for National Atomic Company Kazatomprom JSC unpacks. It reveals how Kazatomprom's pricing power could accelerate or stall from here.

Centrica (LSE:CNA)
Overview: Centrica is an integrated energy utility that supplies power and gas, runs nuclear generation and trades and optimises that electricity within a broader portfolio.
Operations: Centrica generates about £16.3b from Retail, £6.0b from Optimisation and £1.6b from Infrastructure, partly offset by inter segment and IFRS 9 related items.
Market Cap: £7.1b
Centrica matters for this Nuclear Energy Stocks theme because its nuclear generation and trading arm feeds directly into grid scale low carbon baseload power rather than just peripheral services.
"Expanding investment in regulated and contracted infrastructure such as Sizewell C, Grain LNG and the Meter Asset Provider, which together contributed about £80m of EBITDA in H1 2026 and are expected to reach roughly £175m in 2026, points to a growing base of long-duration earnings that can raise the share of predictable EBITDA and support more stable net margins."
The real test for Centrica is how one gathering pressure in its retail book shapes the cash that ultimately supports those nuclear linked assets.
That pressure point is exactly what the full narrative for Centrica unpacks, separating noise from the cash engine that could keep Centrica's nuclear exposure on an accelerating path.

Seeking Alternatives Before The Crowd Moves
Fresh breakout themes rarely stay quiet for long. Once momentum catches, prices can start moving quickly and entry points can become less attractive. Scan these under the radar ideas now to review them while they are still early.
- Spot income ideas that aim to keep paying you while others focus on headlines by scanning a curated set of 5 dividend fortresses built on robust fundamentals.
- Target smaller AI players before attention increases by running through 4 AI small caps with real businesses behind the ticker, not just hype.
- Focus on resilient balance sheets and cleaner risk profiles by tapping into a hand picked list of solid balance sheet and fundamentals (10 results) for your shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com