
Learn Why The Bull Case For Watsco (WSO) Could Change Following Record Sales And Margin Pressure
- Watsco reported third quarter 2026 sales of US$2,220.36 million and net income of US$155.37 million, with nine month revenue of US$5,858.23 million and net profit of US$397.78 million, while diluted EPS from continuing operations reached US$3.77 for the quarter and US$9.72 for the nine month period.
- Management is leaning on e commerce investments, plumbing expansion such as the Granite Group acquisition, and a new US$750 million five year unsecured revolving credit facility to fund working capital, M&A and dividends while margins remain below internal targets.
- We will now look at how Watsco's investment narrative is shaped by record sales alongside investor focus on sub target profit margins.
What Is Watsco's Investment Narrative?
The basic Watsco pitch is pretty simple. You need to believe this distributor can turn its HVAC and plumbing scale, tech investments and long relationships with contractors into durable cash generation, even when margins wobble. The latest quarter supports the idea that demand is there. Revenue for both the quarter and nine month period was higher than last year, even though earnings per share from continuing operations were slightly lower. That combination keeps the focus squarely on execution rather than end market collapse.
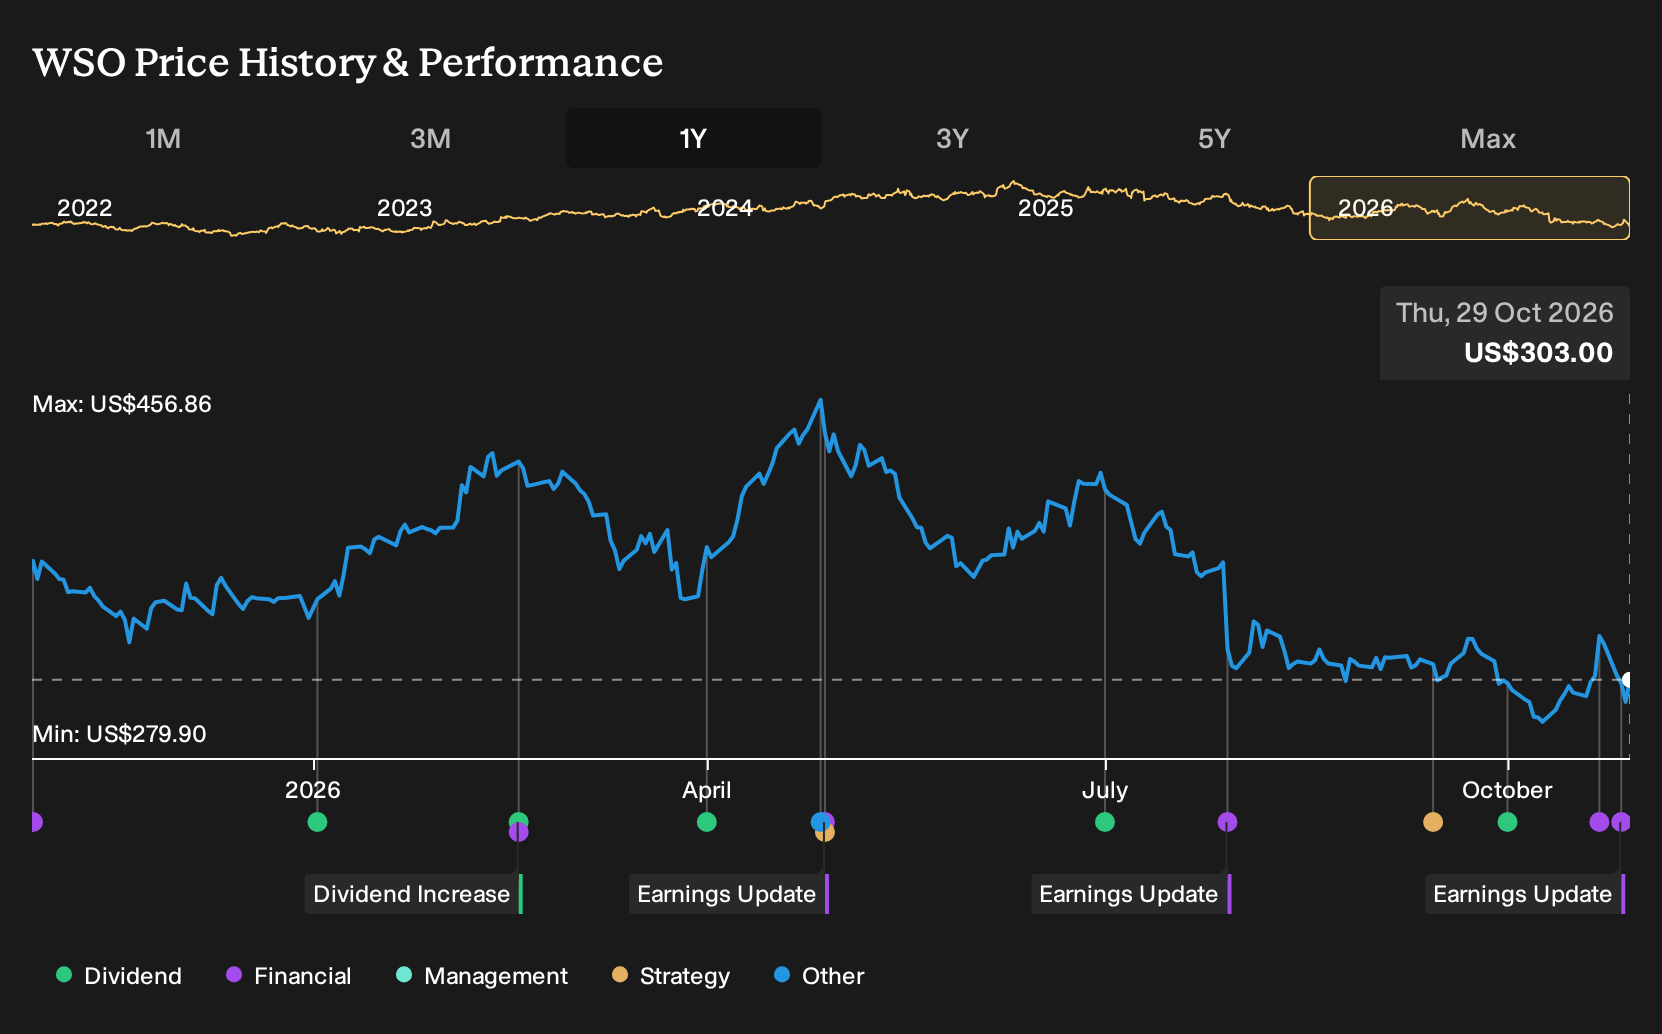
In the short term, the key swing factor is whether Watsco can lift profitability back toward its own targets while still funding e commerce, plumbing and potential M&A. The new US$750 million unsecured revolving credit facility gives breathing room on working capital, deals and dividends, which matters for a distributor with seasonal cash needs. Recent share price weakness and softer net income underline the risk that heavier spending, thinner margins and a not cheap P/E all collide if management mis-times this push.
Even so, there is a less obvious pressure point that could matter a lot if ...
There's only one way to know the right time to buy, sell or hold Watsco. Head to Simply Wall St's company report for the latest analysis of Watsco's Fair Value.
Exploring Other Perspectives
One alternative view puts Watsco’s digital push at the center of the story. The most optimistic analysts were penciling in about 8.5% annual revenue growth and earnings of US$638.0 million longer term, even before this quarter’s results. That is a much brighter script than consensus and it may be rewritten once you see how these numbers age after the new data.
Explore 3 other Watsco fair value estimates, including one that suggests potential upside of up to 65% from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Watsco research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Watsco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Watsco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Watsco?
If this Watsco update has sharpened your thinking but you want a broader hunting ground, the Simply Wall St screener can help you line up fresh possibilities that fit your own risk tolerance and income needs.
- For investors who want potential upside with some balance sheet resilience on their side, start with a focused 18 high quality undiscovered gems that puts financial strength and quality front and center.
- If capital preservation is high on your list, you may prefer sturdier businesses that tend to ride out tougher periods with fewer shocks. In that case, a curated 30 resilient stocks with low risk scores can quickly narrow the field.
- When you care most about companies that are not drowning in debt and still have solid fundamentals backing their story, a targeted list of solid balance sheet and fundamentals (23 results) can surface ideas worth a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com