
Union Tool And 2 Other Japanese Growth Stocks To Own
Japanese shares linked to growth are back in focus after the Bank of Japan held rates at 1.25% and signalled that inflation has reached its 2% target. That combination puts a spotlight on companies where management and analysts already expect robust expansion. For investors seeking potential upside rather than simply holding cash, this article walks through three high conviction Japanese stocks filtered for strong growth characteristics.
The three stocks highlighted below are only a sample of the idea. The full screen surfaced 23 more Japanese growth stories where both management commentary and analyst expectations point to ambitious expansion plans that are not covered here. To see the wider opportunity set, head straight into the High Growth High Conviction screener to analyze, filter, and identify the highest conviction growth plays that best match your own risk profile and time horizon.
Union Tool (TSE:6278)
Overview: Union Tool manufactures precision PCB drills, micro hole cutting tools, and coated routers for semiconductor and electronics production, alongside broader cutting and motion control equipment.
Operations: Union Tool generates about ¥31.1b of revenue from Asia and ¥31.0b from Japan, with smaller contributions from Europe and North America.
Market Cap: ¥258.0b
Union Tool is positioned within the High Growth High Conviction theme through its PCB drills and precision tooling for electronics manufacturing. Forecast earnings growth of 27.5% a year and profit margins at 18.8% are reported alongside new capacity plans for cutting tools, with the company’s outlook linked to how this expanded production aligns with end demand.
That production question is exactly what you can pressure test through the DCF valuation analysis for Union Tool to see how different demand paths might reshape Union Tool’s upside profile.

Sansan (TSE:4443)
Overview: Sansan runs cloud services that turn business cards and contact data into shared corporate CRM, driving subscription revenue from digitised relationship data.
Operations: Sansan generates about ¥48.9b from its Sansan/Bill One business and ¥7.1b from Eight, with virtually all revenue from Japan.
Market Cap: ¥268.5b
Sansan aligns closely with the High Growth High Conviction theme because its contact-data SaaS stack supports recurring revenue and high projected ROE. However, the stock trades well below one estimate of fair value, and outcomes may depend on how a single pressure on that data monetisation story resolves.
That single pressure point is exactly what you can stress test through the 3 key rewards and 1 important warning sign, so you see where Sansan’s upside and vulnerability really sit.
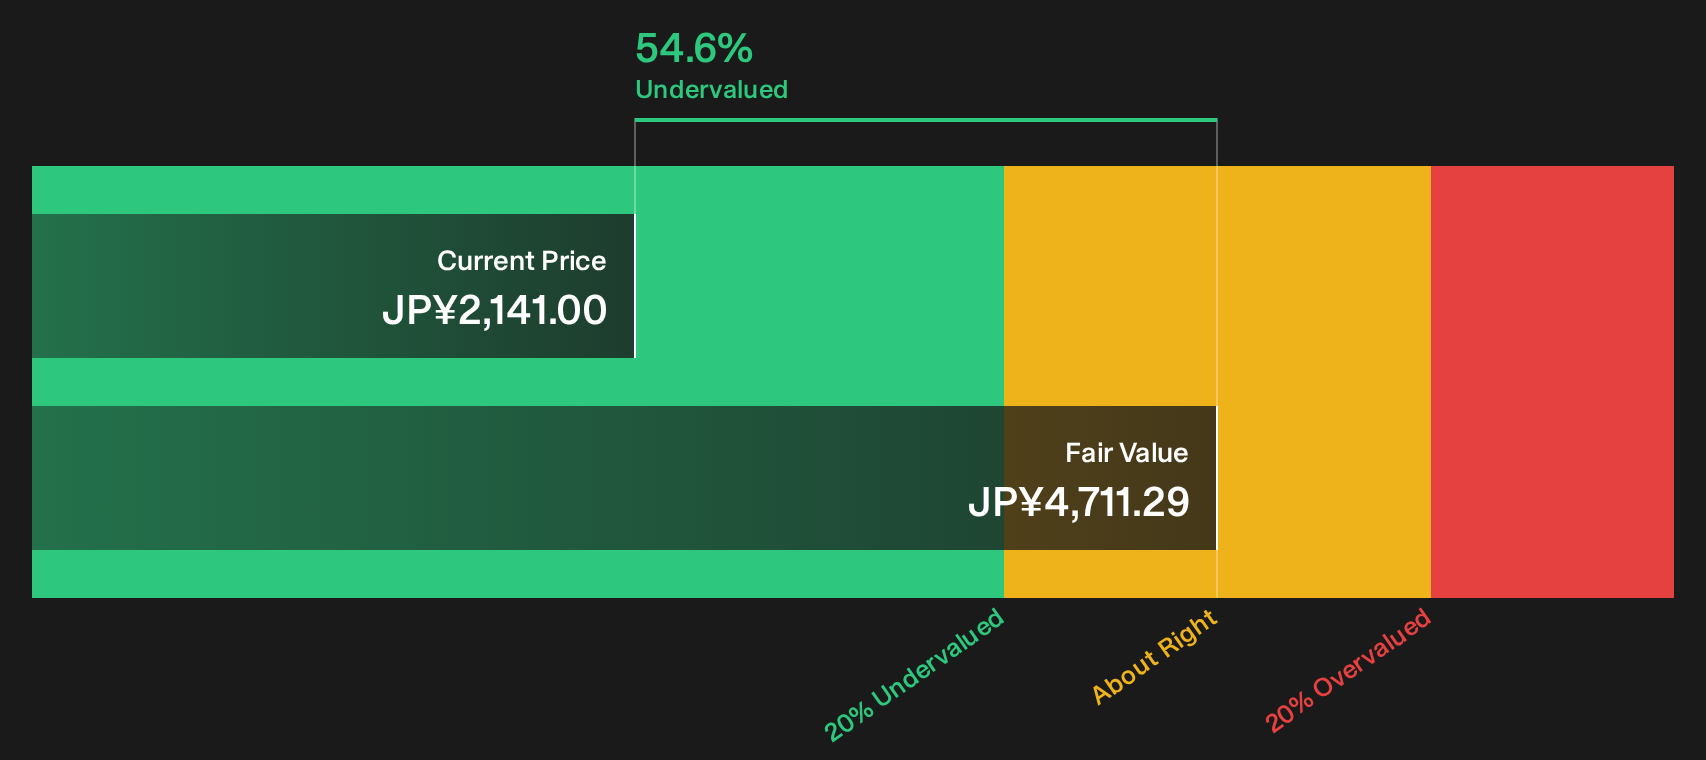
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor test and inspection equipment, especially probe cards and wafer probers, plus body measurement and display testing gear.
Operations: Micronics Japan generates about ¥84.9b from its Probe Card Business and ¥1.4b from TE Business, with sales mainly across Japan and wider Asia.
Market Cap: ¥480.4b
Micronics Japan is closely connected to the High Growth High Conviction theme through its semiconductor testing tools. One key consideration is how assumptions about the probe card order cycle may influence whether margins widen or compress.
That margin swing is exactly what you can pressure test through the DCF valuation analysis for Micronics Japan before the probe card cycle either accelerates or stalls.

Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move first, and the best breakout stories often fly before most investors are even watching. Scan these under the radar for now and consider acting while they remain less widely followed.
- Target resilient payouts that keep working while markets shift by running your own search across the 30 dividend fortresses before yields change or spreads compress.
- Track industrial and infrastructure momentum by scanning the 43 power grid technology and infrastructure stocks while these grid and electrification opportunities are still building strength under the radar.
- Review new AI compounding stories and filter through the 38 profitable AI stocks that aren't just burning cash while cash generative operators may still be mispriced and before momentum develops further.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com