
T. Rowe Price (TROW) Stock Gains Ground After Q3 Results Pressure Fees
T. Rowe Price came into this earnings report with a value label attached, trading on a low P/E and carrying a rich dividend, yet questioned for growth. Q3 2026 results put some numbers behind that debate. The asset manager posted US$2.79 in basic earnings per share and US$2.0b in revenue, solid profitability for an active manager under fee and flow pressure. The stock rose 2.5% to US$106.63 on the day after the release, a move that hints at relief, but the real story sits in how those profits were earned and what they cost.
Love the income from T. Rowe Price Group but uneasy about paying up for an asset manager under fee and flow pressure? You can filter for other high cash generation plays with strong balance sheets and fundamentals using our list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,004.9m vs. US$1,893.5m (up about 5.9%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$595.1m vs. US$631.4m (down about 5.7%)
- Basic EPS (Earnings Per Share, Q3 2026 vs. Q3 2025): US$2.79 vs. US$2.88 (down about 3.0%)
- Assets Under Management (AUM, End of Period, Q3 2026 vs. Q3 2025): US$1,863.4b vs. US$1,767.2b (up about 5.4%)
Management keeps highlighting AI as a key growth catalyst. Ask Charlie which T. Rowe Price AI moves really matter.
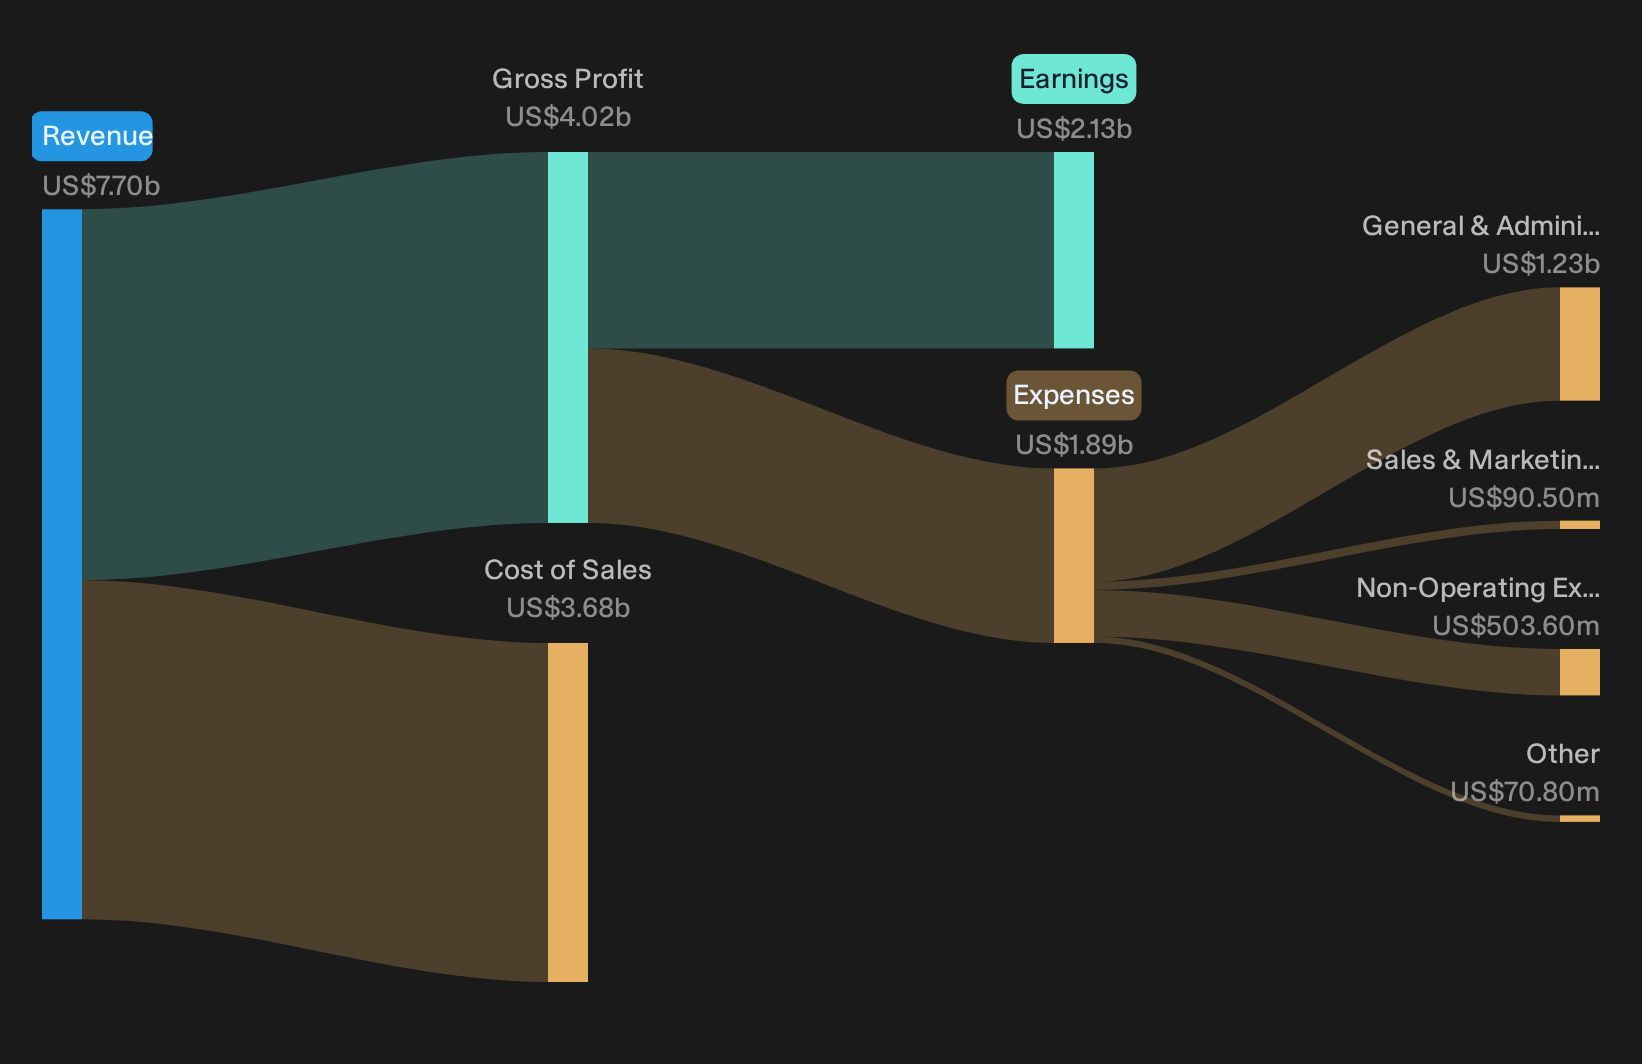
T. Rowe Price Bull Case Meets Mixed Flow Reality
The bullish script argues that newer products eventually outweigh legacy mutual funds as engines for T. Rowe Price.
"A key factor is whether growth in ETFs, SMAs, alternatives, digital assets and AI enabled offerings is sufficient to offset fee pressure and persistent outflows from higher fee active equity products."
Q3 shows partial progress. ETF assets kept attracting money, with US$3.8b of net inflows and US$11b year to date, and fixed income plus alternatives also drew cash. Yet overall net outflows of US$28.3b, along with a lower 37.8 bp advisory fee rate, indicate that the newer engines are not yet large enough to neutralize pressure from active equity redemptions.
One Narrative disagrees with today's price. → See where this Narrative says T. Rowe Price Group should trade.
T. Rowe Price Bear Case Finds Fresh Support
The bear worry is that fee pressure and heavy spending quietly chip away at earnings power even when T. Rowe Price posts solid headline profit.
"While T. Rowe Price Group is investing heavily in AI across more than 130 workflows and tying this to demand for more advice and personalization in defined contribution plans, the cost of rolling out and maintaining these tools, alongside an expense growth outlook of 4% to 7% over 2025 levels, could offset potential efficiency gains and restrain future earnings leverage."
Q3 delivers early evidence. The effective fee rate slipped again to 37.8 bp and net outflows reached US$28.3b. Management still guides to 4% to 7% expense growth for 2026, so the milestone of clear operating leverage is not met this quarter.
Hunt Quiet Mispricing Before It Fades
T. Rowe Price Group just showed how headline profit can mask pressure on fees and flows. The real opportunity is tracking down stocks that could be undervalued before the crowd catches on.
- Company 1 - 26% below our estimate - builds chips and software that keep data moving, connected and secured across complex AI and cloud workloads.
- Company 2 - 23% below our estimate - ties AI assistants into productivity, coding and security tools so enterprise customers can activate new paid workloads quickly.
- Company 3 - 20% below our estimate - scales a teahouse network where new locations and memberships raise transaction volume while protecting franchisee economics.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com