
Power Corp. Of Canada (TSX:POW) Stock May Stay Reasonable As Wealth Platform Funding Expands
Power Corporation of Canada has delivered a powerful share price run in recent years, so the live question for anyone looking at the stock today is whether that move lines up with the returns the business earns on its capital.
- Over the past 3 years, the stock has returned 224.2%. That puts a lot of weight on whether the underlying capital returns are strong enough to support that kind of rerating.
- The fresh CAD 164m commitment into Wealthsimple and related wealth platforms may support expectations for future capital deployment, earnings mix and cash generation that all feed into the returns Power Corporation of Canada can earn on each dollar it invests.
- Prefer to judge Power Corporation of Canada on earnings? See why Power Corporation of Canada's 23.4x P/E tells a different valuation story.
The issue now is whether the returns Power Corporation of Canada earns on its capital are strong and durable enough to justify where the share price sits today.
If you are weighing Power Corporation of Canada after this Wealthsimple move, it can help to compare it with other holdings-focused groups that have broad wealth exposure by scanning solid balance sheet and fundamentals stocks screener (6 results)
Where Does Power Corporation of Canada Sit on Excess Returns?
The Excess Returns model looks at how much profit Power Corporation of Canada can generate above the cost of its equity base. On this view, the group is working with a book value of CA$37.74 per share and a stable book value estimate of CA$43.96 per share, against a stable EPS figure of CA$4.44 per share built from its five year median return on equity. With an average return on equity of 10.10% and a cost of equity of CA$2.83 per share, the framework attributes CA$1.61 per share to excess return above that required return.
For investors weighing today’s CA$98.05 share price, that pattern points to a business priced broadly in line with what its ongoing return on equity profile suggests. The recent CAD 164m commitment into Wealthsimple and related wealth platforms helps explain why the market appears comfortable valuing Power Corporation of Canada close to where the Excess Returns model lands. Find out what Power Corporation of Canada could be worth using our Excess Returns estimate.
The Power Corporation of Canada Narrative: What Would Justify Today's Price?
Power Corporation of Canada’s recent share price run raises a simple follow up question for you as an investor. What would need to be true about its future earnings power for that level to look either conservative or stretched? Narratives on Simply Wall St’s Community page are built to answer exactly that by spelling out the growth, profitability and risk paths that would have to play out. Each narrative frames its numbers around a specific view of where revenue, margins and potential downsides go next, which you can revisit as fresh information comes through.
One of the top community narratives on Power Corporation of Canada: 57% overvalued
"Heavy reliance on core financial subsidiaries, regulatory risk, fintech disruption, and unproven alternative investments threaten earnings stability and long-term profitability..."
Discover why this Narrative puts Power Corporation of Canada at 57% overvalued.
The share price is only one signal in the Power Corporation of Canada story
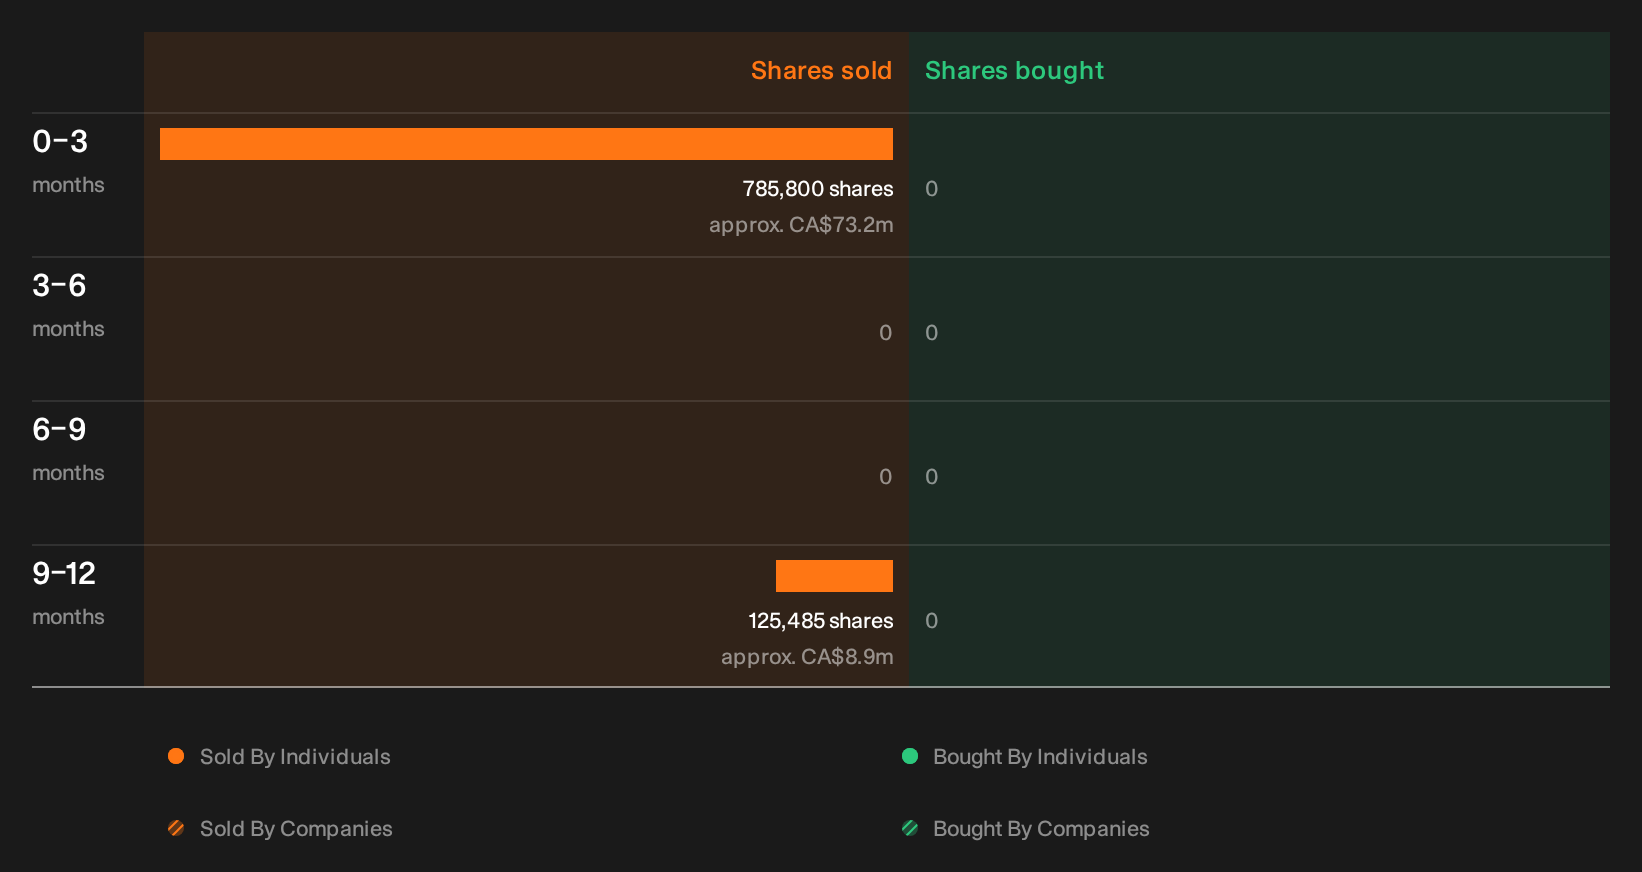
Price, book value and return metrics tell only part of what you need to know about Power Corporation of Canada, since recent activity by people on the inside has been flagged by our checks and still needs a closer look from you. See the recent insider selling flagged for Power Corporation of Canada.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com