
What Has Actually Changed At Twilio After A 114% Jump
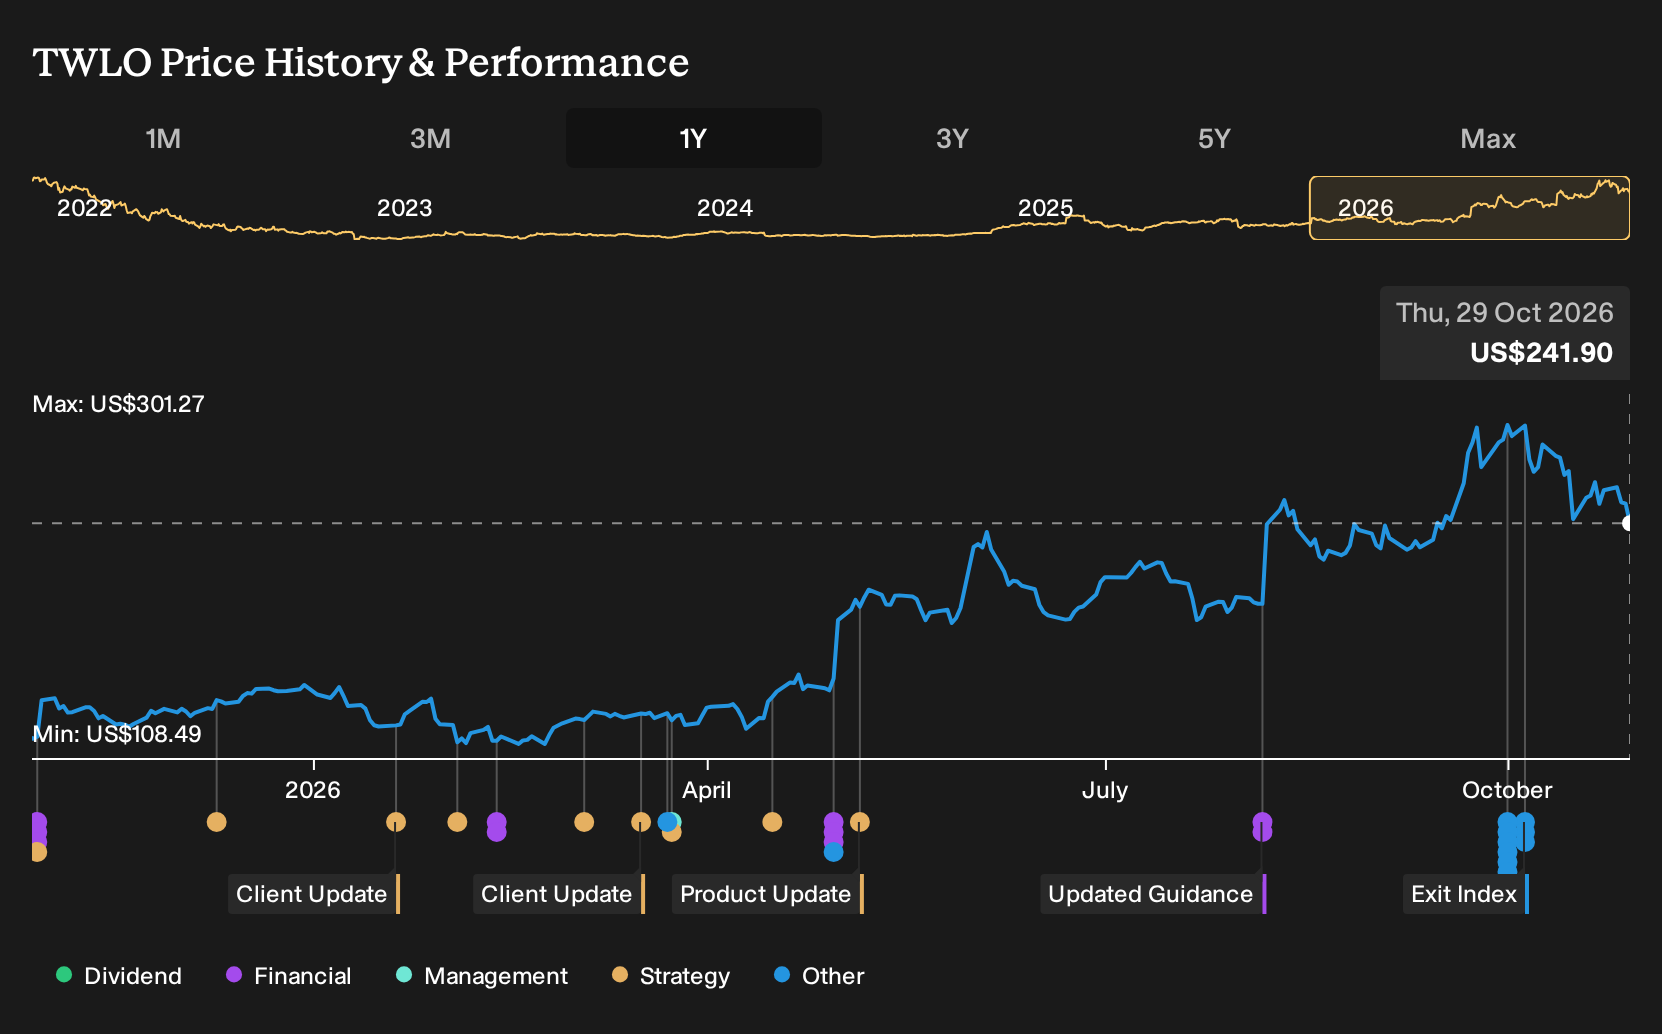
If you had picked Twilio on 29 October 2025 and simply held on, the result would look very different in your portfolio today. Holding Twilio over the past year would have returned 114.3%, including dividends. That headline figure is eye catching, but it raises a harder question. If you faced the same split between bullish AI expansion hopes and concerns over regulation, competition, and low margin messaging again, what would you have done differently?
The move put Twilio in the middle of this trade. Scan 54 AI infrastructure stocks for other companies exposed to it.
The Two Stories Twilio Investors Were Balancing
The shares cost US$112 at the start of the period, which required anyone looking at Twilio to decide how much confidence to place in the competing stories around AI and regulation.
On the more optimistic side, the bull case put Fair Value at US$131, a price implied by a scenario where AI driven communications, 7.9% revenue growth, and a 7.6% profit margin support global expansion and stronger returns.
The more cautious view pointed to a Fair Value of US$85.91, based on expectations of rising compliance costs, tougher CPaaS competition, and only a 5.5% margin assumption despite 7.5% growth.
What The Results Changed For The Twilio Thesis
Twilio’s Q2 2026 numbers gave the clearest test of the AI growth story. Total revenue reached US$1,499.1m compared with US$1,228.4m a year earlier, while net income moved from US$22.4m to US$1,067.2m and net margin from 1.8% to 71.2%. That scale of profitability shift leaned toward the optimistic case, although valuation concerns in later coverage meant the cautious view on pricing power stayed alive.
The key assumption was that AI driven products would translate into healthier margins, not just higher sales. For any other company, you would check the same thing by tracking the relationship between new product launches, revenue mix by segment, and the reported net margin over several reporting periods.
What Twilio’s Run Already Assumes
Twilio now trades at US$242 after a 114.3% gain over the past year. The selected Narrative’s Fair Value sits below that price, implying its authors see recent enthusiasm as generous compared with their own assumptions.
The Narrative hinges on AI driven workloads and self serve tools continuing to support a richer software mix. Anyone paying today’s level is effectively judging whether that AI led, higher margin usage can keep offsetting weaker messaging economics.
"The main factor that has to go right is that Twilio converts early traction in AI voice, conversational infrastructure and its integrated data stack into durable, high margin multiproduct growth that offsets carrier fee headwinds and low margin messaging mix."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 38% below our estimate - uses AI tools and stricter carrier screening to tighten claims control and fraud risk.
- Company 2 - 20% below our estimate - extends franchised teahouses overseas while balancing same-store GMV with franchisee returns.
- Company 3 - 26% below our estimate - embeds custom silicon and networking chips at critical bottlenecks in large scale computing.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com