
Does Raised 2026 Outlook Change The Bull Case For PTC Therapeutics Stock (PTCT)?
- PTC Therapeutics reported third quarter 2026 revenue of US$357.81 million and a net loss of US$51.69 million, then raised full year revenue guidance to a range of US$1.29 billion to US$1.32 billion, with product revenue now expected at US$960 million to US$990 million.
- Behind the headline numbers, strong demand for key rare disease treatments, pipeline progress such as the Fabry gene therapy acquisition, and management’s decision to lift guidance all show how execution on core products and late stage assets is shaping PTC Therapeutics' operating profile.
- The focus now turns to how PTC Therapeutics' upgraded 2026 revenue outlook might influence the broader investment narrative around the business.
Scan how PTC Therapeutics' raised guidance compares with other rare disease and biotech players by checking the hand picked 18 high quality undiscovered gems that might be flying under most investors' radar.
PTC Therapeutics Investment Narrative Recap
To own PTC Therapeutics, you need to believe the core rare disease portfolio, led by Sephience and Translarna, can support a transition from periodic losses to steadier cash generation. The raised 2026 revenue outlook suggests near term demand is tracking ahead of internal expectations, although the reported third quarter net loss highlights that the path to sustained profitability is not yet resolved.
The key short term catalyst remains execution on the Sephience rollout and maintaining country level access for Translarna while late stage programs move forward. The biggest risk stays the same. Heavy reliance on a handful of drugs and ongoing losses could intersect with regulatory or reimbursement setbacks and pressure funding needs.
The most relevant update for this earnings release is the higher 2026 revenue guidance to US$1.29b to US$1.32b, with product revenue now expected at US$960 million to US$990 million. That uplift is tied to current operating momentum rather than distant pipeline outcomes, so it feeds directly into how you think about near term cash flow and balance sheet flexibility.
This guidance shift sits next to a third quarter where PTC Therapeutics posted US$357.81 million in sales and a net loss of US$51.69 million. The mix of stronger top line and continuing losses keeps execution risk front and center. It also sharpens the focus on whether upcoming milestones such as the planned ST 920 filing can broaden revenue and reduce dependence on a few assets.
PTC Therapeutics' current analyst narrative points to revenues of US$1.7b and earnings of US$361.8 million by 2029. That outlook implies 18.1% yearly revenue growth and an earnings swing of roughly US$400 million, from earnings today of a US$38.4 million loss to the 2029 consensus level.
Uncover why PTC Therapeutics' fair value indicates a 52% potential upside to its current price that could close sooner than many investors expect.
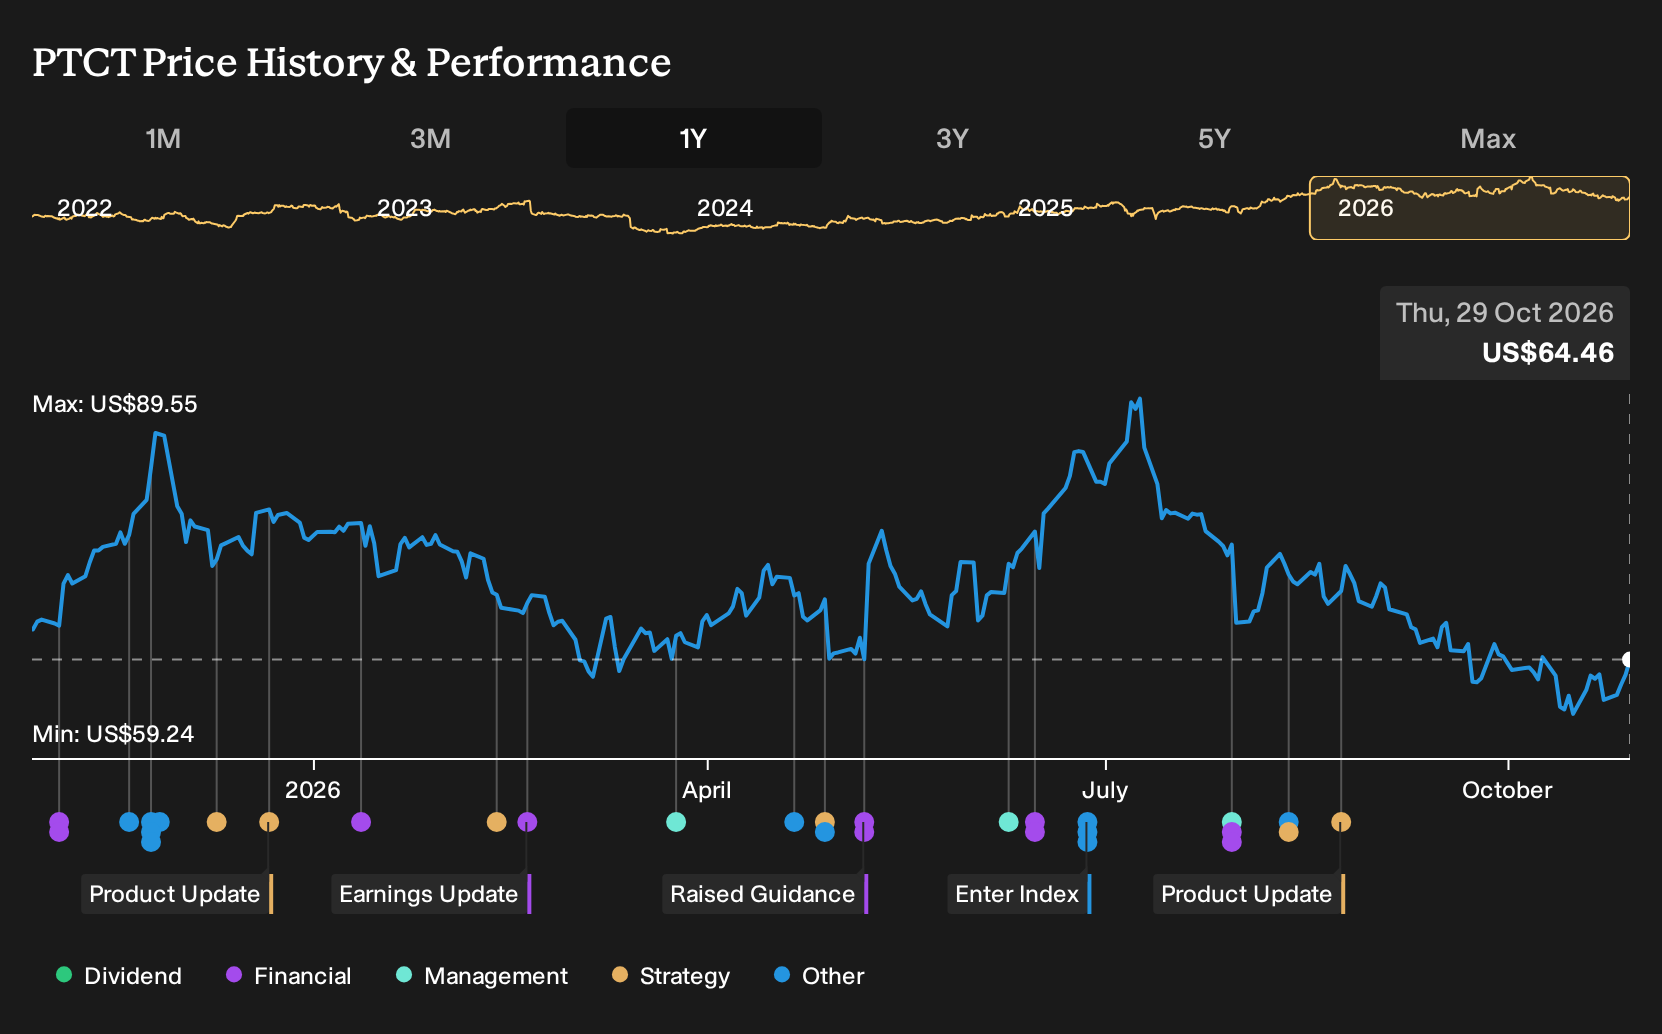
Exploring Other Perspectives
One bullish angle on PTC Therapeutics leans heavily on the cash position and rare disease pipeline. Before this earnings release, the most optimistic analysts were already working off 2029 revenue near US$2.1b and earnings around US$638.1 million. Those targets are far above the consensus US$1.7b and US$361.8 million and may shift again once this new guidance is fully absorbed. That range of views is wide, so consider it an opportunity to compare different scenarios and decide which story appears more realistic to you.
Explore 2 other PTC Therapeutics fair value estimates, including one that suggests as much as 256% above the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your PTC Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for PTC Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PTC Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond PTC Therapeutics?
Once you have a view on PTC Therapeutics, it can help to widen the lens and compare it with other potential opportunities that fit different portfolio roles. Use the Simply Wall St Screener to scan these hand picked sets of stocks and see how they stack up against your own criteria.
- If you want potential upside with tighter downside risk, start by reviewing a group of companies screened as having resilient profiles through the 30 resilient stocks with low risk scores.
- If steadier income is your priority, focus on businesses screened for robust yield and consistency by checking the 7 dividend fortresses.
- If your goal is to spot quality that might be overlooked, search through our curated 18 high quality undiscovered gems that combine strong fundamentals with less crowded attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com