
Galderma Group (SWX:GALD) Could Be 6% Undervalued After Raised Sales Guidance
Galderma Group (SWX:GALD) has drawn fresh attention after reporting third quarter net sales of US$1,632 million and updating its 2026 net sales growth guidance to a range of 22.5% to 23.5% at constant currency.
That backdrop has been reflected in the ticker over the past year, with the share price at CHF189.7 and an 18.49% year to date share price return. The 1-year total shareholder return of 28.89% suggests momentum has been building as recent guidance and product news filtered through.
Scan beyond Galderma Group and find other dermatology and healthcare names showing similar momentum with our hand-picked 130 healthcare AI stocks screened for quality and strong fundamentals.
Galderma Group appears to be a focused dermatology specialist with fresh product launches and higher guidance now reflected in expectations. After this strong run, the key question is whether the current CHF189.7 price still offers value.
Most Popular Narrative: 6% Undervalued
Against the last close at CHF189.7, the most followed narrative pegs Galderma Group's fair value nearer CHF202.22, which frames the recent share price strength as still leaving some upside according to that model.
The strong uptake and market share gains of newly launched products like Nemluvio and Relfydess, driven by their differentiated clinical profiles and positive physician reception, are likely to accelerate Galderma's top-line growth and expand the addressable market, especially as global population aging and heightened focus on appearance drive continued demand for dermatological and aesthetic treatments, positively impacting future revenues.
See why 14 investors see Galderma Group as 6% undervalued.
That assessment uses a 3.95% discount rate and assumes annual revenue growth of about 16.5%, with profit margins moving from 14.6% to around 20.7% over the next few years. It also builds in a future P/E of roughly 32.5x, compared with a current multiple of 62x, as well as earnings rising from US$863.0m to about US$1.9b by 2029.
Analysts behind this narrative also factor in share count shrinking by roughly 0.59% per year and a net profit margin of 20.68% in their model. Those inputs, combined with the discount rate, are what produce the CHF202.22 fair value output rather than any single headline datapoint or short term trading move.
Result: Fair Value of CHF202.22 (UNDERVALUED)
Still, Galderma Group’s reliance on Nemluvio and Relfydess, along with pressure in injectable aesthetics from pricing and regulation, could quickly challenge this underpriced story.
Find out about the key risks to this Galderma Group narrative.
Another View: What Galderma Group’s P/E Is Telling You
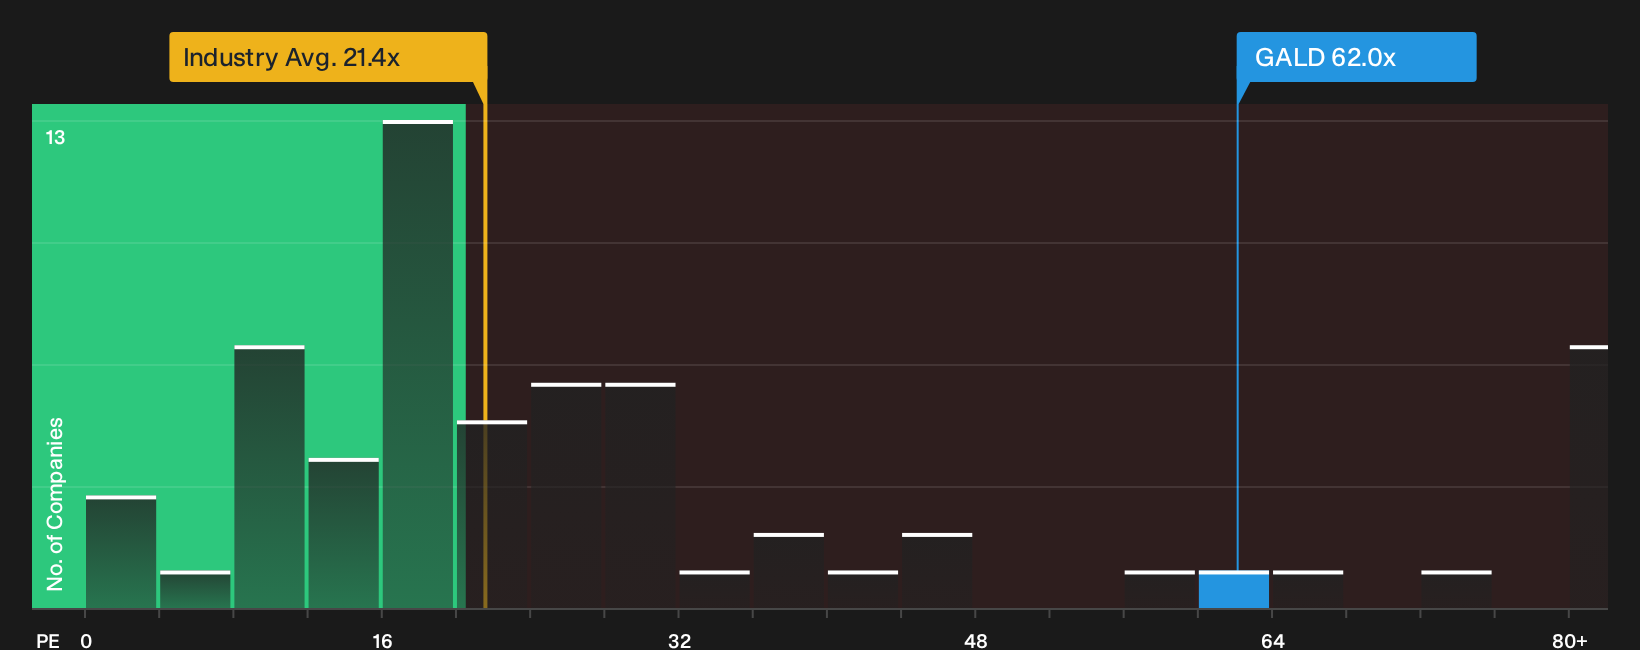
The DCF work points to upside for Galderma Group, yet the market is paying a rich 62x P/E. That is nearly three times the European pharmaceuticals average of 21.3x and above an estimated fair ratio of 44.7x, which pushes more of the risk onto execution assumptions.
Investors weighing that gap between a high current multiple and a lower fair ratio may want to ask whether they are being paid enough for the possibility that sentiment cools if expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
After all this optimism around Galderma Group, the real edge comes from testing the numbers yourself instead of inheriting the crowd’s mood. To see which potential upsides our model has flagged and judge them against your own expectations, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Galderma Group?
If Galderma Group has sharpened your curiosity, do not stop here. Use the data to spot fresh setups, compare opportunities, and pressure test where your next franc goes.
- Target potential mispricing by scanning a curated pool of 195 high quality undervalued stocks that pair attractive valuations with solid financial footing.
- Strengthen your income stream by reviewing 228 dividend fortresses that combine higher yields with business models built around consistent payouts.
- Dial back risk without sitting in cash by focusing on 228 resilient stocks with low risk scores designed to prioritize resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com