
What AtkinsRealis Group (TSX:ATRL)'s US Infrastructure Contract Wins Mean For Shareholders
- AtkinsRéalis Group has been engaged on multiple large scale US infrastructure and energy initiatives, including new General Engineering Consultant contracts with the Florida Department of Transportation, a traffic management center mandate for TxDOT's Austin District and a nuclear focused Memorandum of Understanding in Indiana.
- These wins expand AtkinsRéalis Group's foothold in long dated transportation and nuclear programs, which can influence backlog mix, execution risk and the timing of future capital needs.
- We will now look at how AtkinsRéalis Group's expanding US transportation program work could influence the broader investment narrative investors focus on.
AtkinsRéalis Group Investment Narrative Recap
To own AtkinsRéalis Group, you need to believe the company can keep turning a very large, long dated backlog into cleaner, higher quality earnings while gradually putting legacy issues behind it. The fresh US transportation wins fit that story by reinforcing the shift toward fee based engineering and operations work. In the near term, the key catalyst still hinges on converting this contracted work into steady cash generation rather than headline backlog alone.
The biggest risk remains execution on complex projects and the impact of any cost overruns, especially with margins already compressed and one off items affecting reported profitability. The Texas TMC and Florida GEC mandates add operational complexity but do not fundamentally change that risk reward debate. They matter most if AtkinsRéalis Group runs them on time, on budget and with consistent margins.
The Indiana CANDU reactor Memorandum of Understanding feels most relevant for investors weighing long term catalysts. It signals that AtkinsRéalis Group is being invited into early stage thinking on potential multi unit nuclear programs in the US, which aligns closely with existing nuclear revenue of about CA$2.6b and the stated focus on full cycle services.
Because the MOU is still exploratory, it does not reshape the near term picture on its own. It does, however, sit alongside record nuclear revenue in early 2026 and a CA$4.2b nuclear backlog as an indicator of where future work could come from. For you, the operational question is whether the firm can pursue opportunities of this scale without stretching delivery teams or re introducing the kind of project risk investors are watching so closely.
Analysts outline a scenario in which AtkinsRéalis Group reaches CA$14.1b in revenue and CA$904.7m in earnings by 2029, with this scenario implying revenue growing at 6.4% a year and earnings rising by about CA$474.5m from CA$430.2m today.
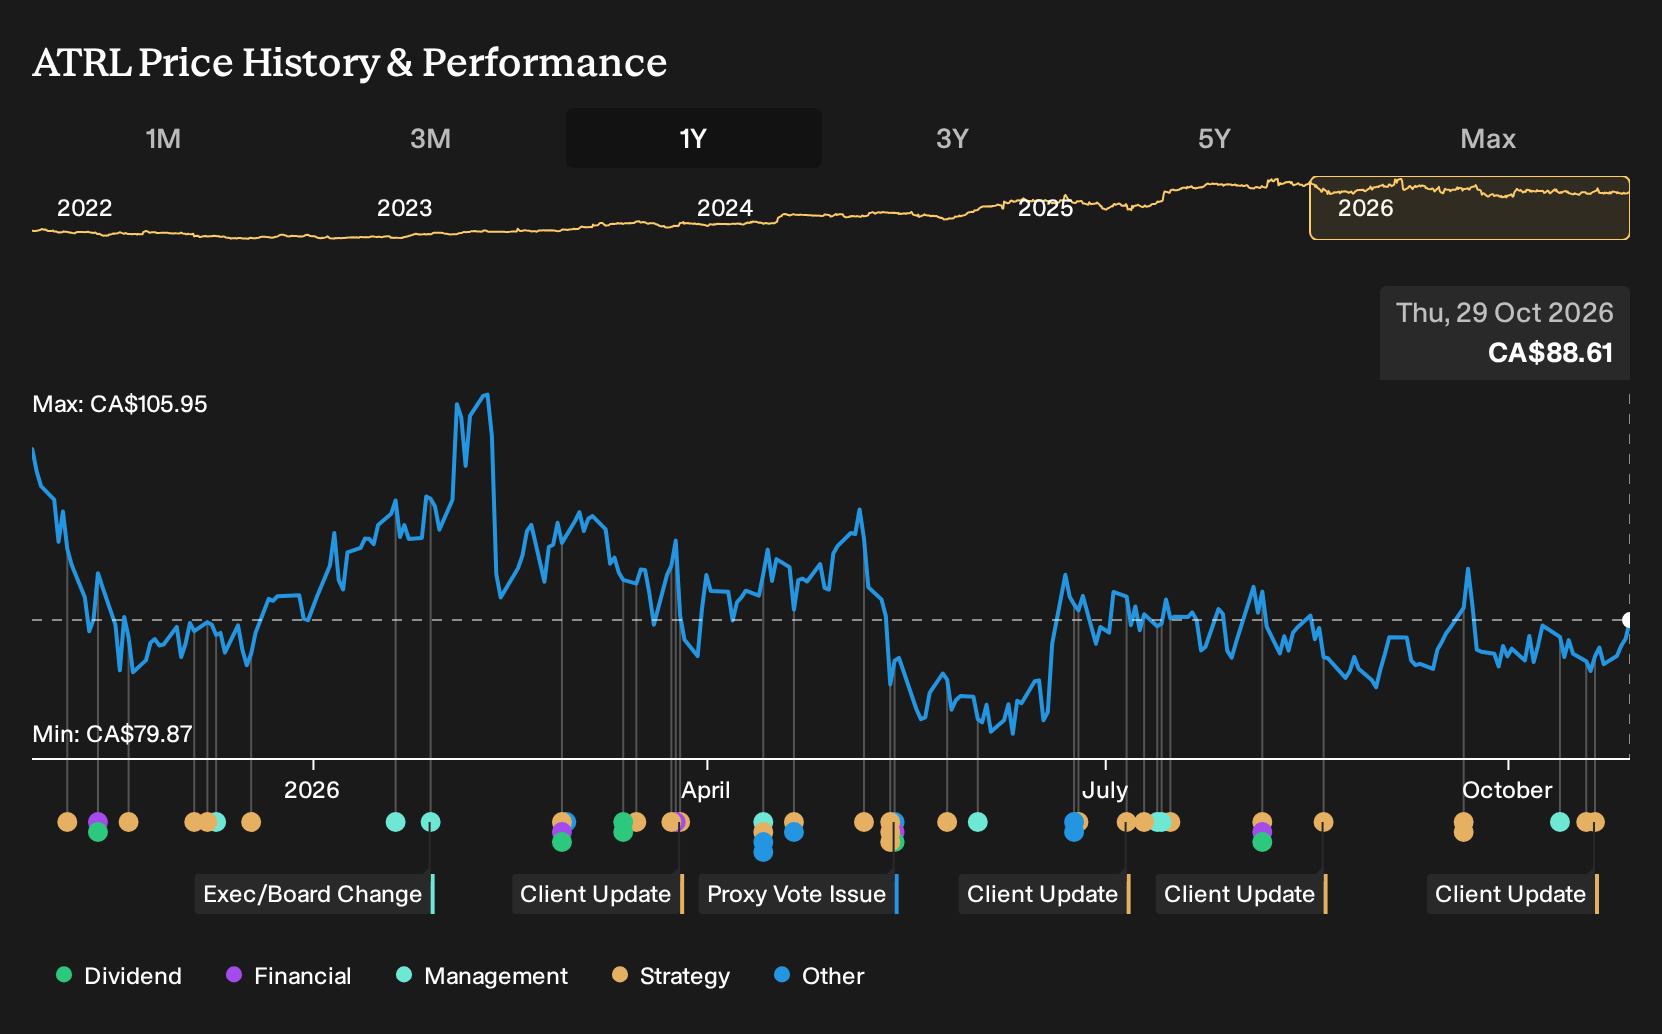
Uncover why AtkinsRéalis Group's fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster in a tight band between $105.48 and $117.29, yet those private investors still disagree on what AtkinsRéalis Group is worth. New US transportation and nuclear contracts could shift that range over time, particularly if changes in project execution or EMEA weakness affect earnings quality. Explore the different opinions before setting your own anchor.
Explore 3 other AtkinsRéalis Group fair value estimates, including one that suggests it could be worth just CA$105.48.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AtkinsRéalis Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AtkinsRéalis Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtkinsRéalis Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond AtkinsRéalis Group?
If the AtkinsRéalis Group story has sharpened your thinking about long dated projects and risk control, you can use that same lens to hunt for other opportunities. The Simply Wall St Screener can help you quickly filter for businesses that match the balance of quality, resilience and potential you are aiming for.
- If capital preservation is high on your list, you may want to start with a focus on resilience and review 8 resilient stocks with low risk scores that may better fit a steadier risk profile.
- For investors who care most about financial strength, you could scan a list of solid balance sheet and fundamentals (6 results) and see which companies pair robust finances with consistent fundamentals.
- If you prefer ideas that the market may be overlooking, you might cast a wider net with a 8 high quality undiscovered gems that already show strong underlying business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com