
Chemours (CC) Stock Still Looks Undervalued After Legal Scrutiny
Chemours has had a tough few years in the market, and that track record puts extra focus on whether the current share price lines up with what its sales actually support. With fresh legal headlines and an ongoing debate about its refrigerants business, the question for investors is how much revenue power the stock is really pricing in today.
- Chemours shares have fallen 47.2% over the past 5 years, which puts long term holders in the red and makes the link between the current valuation and its sales profile a live issue.
- The securities class action over alleged misstatements about Opteon demand and inventory suggests earlier expectations for refrigerant sales and earnings quality may have been misaligned with reality, which can change how much investors are willing to pay for each dollar of revenue.
- There is a second opinion on Chemours worth weighing. See what analysts think Chemours's shares could be worth.
The issue now is whether Chemours' current US$13.19 share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
For a broader sense of how this sales based valuation question plays out beyond Chemours, compare it with companies in the 30 high quality undervalued stocks
Is Chemours a Bargain on Sales?
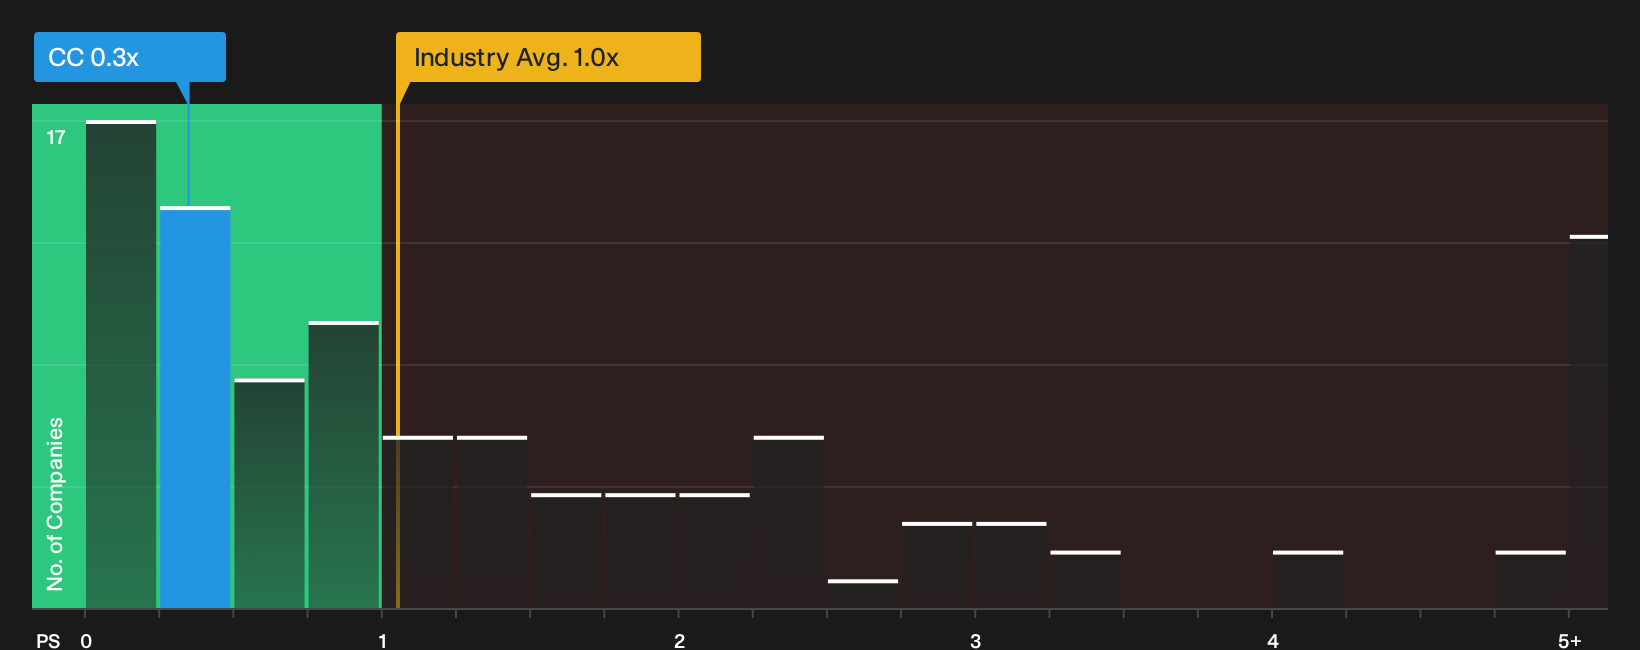
The P/S ratio fits Chemours because revenue tends to track the health of its chemicals franchises more steadily than near term earnings. On this lens, Chemours trades at about 0.3x P/S, compared with roughly 1.0x for the wider Chemicals industry and about 0.7x across its direct peers, so the stock changes hands at a much lower price tag per dollar of sales than similar businesses.
Because the Fair Ratio framework adjusts for Chemours' specific growth profile, profitability, size and risk, its current P/S multiple screens below what that tailored model would imply, which points to the shares being undervalued on this metric. Despite the class action over Opteon disclosures weighing on sentiment since 2026, the market is still valuing Chemours sales at a clear discount to both the sector and that Fair Ratio benchmark. This puts the burden on investors to judge whether the legal and refrigerants issues fully justify such a low revenue multiple. Explore the numbers behind Chemours's P/S valuation.
The Chemours Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Chemours valuation puzzle leaves off and spell out the future paths for growth, margins and earnings that would need to hold for the stock to be worth meaningfully more or less than today’s price. Instead of just giving you a single number from a ratio or model, they lay out the underlying assumptions so you can watch how Chemours' actual progress lines up with the scenario that figure depends on over time.
One of the top community narratives on Chemours: 22% undervalued
"Increasing traction in new cooling solutions, including initial commercial sales and a 70% rise in product trials for two phase liquid cooling…"
Discover why this Narrative puts Chemours at 22% undervalued.
One more Chemours angle worth checking before you move on
Before you stop at the current price tag and sales multiples, it is worth asking who is steering Chemours, how their incentives line up with shareholders, and what that might mean for future decisions. See who runs Chemours and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com