
VF Stock Has The Bull Case Changed After An Earnings Beat
- V.F. Corporation reported Q2 fiscal 2027 revenue of US$2.7b and net income of US$285.3m, beating consensus EPS, reaffirming full year guidance, and continuing its US$0.09 quarterly dividend declared for payment on 17 December 2026.
- Brand mix and execution remain central. The North Face, Timberland, and Altra are growing, while Vans lags, as management pursues a turnaround built on product refreshes and higher margin direct to consumer and e commerce channels.
- We will look at how VF Corporation's investment narrative is shaped by this guidance reaffirmation and brand level turnaround progress.
Scan how V.F's brand turnaround compares to other consumer stocks trying to balance earnings resilience and debt reduction with our hand picked 30 resilient stocks with low risk scores list.
What Is V.F's Investment Narrative?
To own V.F, you need to believe the turnaround is real at the operating level, not just in the share chart. The latest quarter gives you a mixed but usable proof point. Revenue for the period was US$2.7b, slightly behind last year, yet net income and EPS stepped up, helped by margin work and cost control. Reaffirmed fiscal 2027 guidance for revenue growth of 2% or better and a continued US$0.09 dividend suggest management is leaning into a story of steady repair rather than reset.
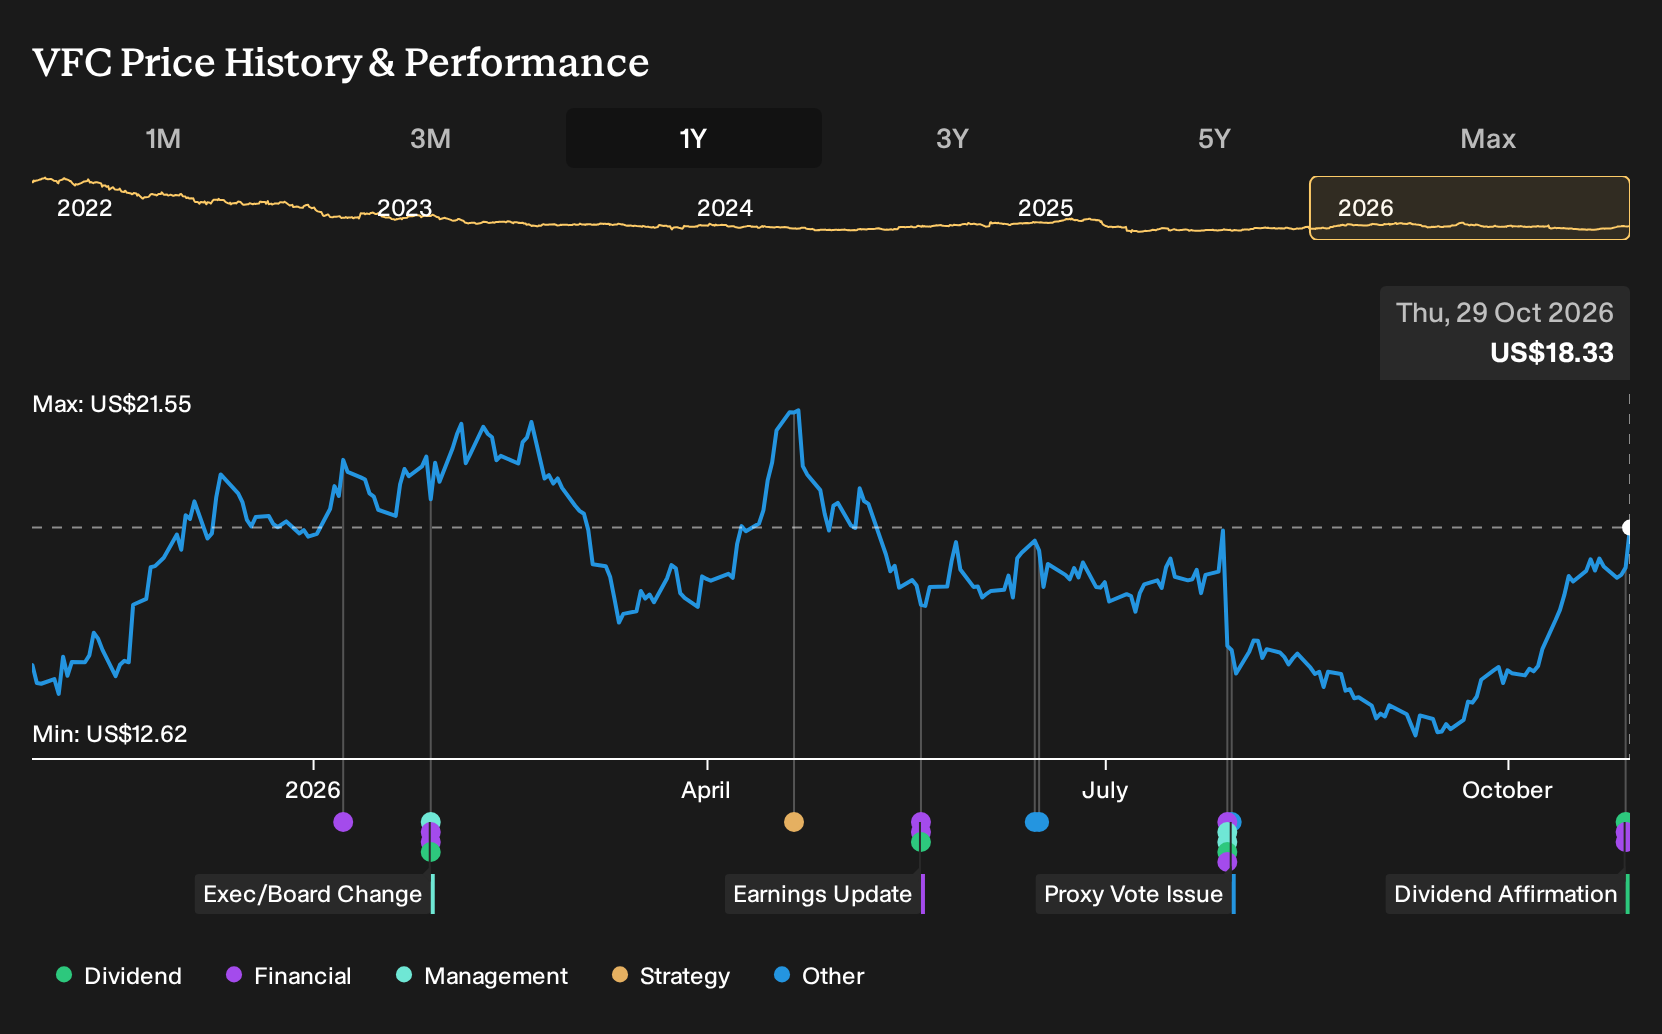
In the short term, the real swing factors are execution at Vans, continued demand for The North Face, Timberland and Altra, and how quickly more sales move into direct to consumer and e commerce. Those channels tend to require ongoing investment but can support better profitability, which matters for a business carrying a meaningful debt load and targeting lower leverage. The stock’s recent rise and the upgrade to a more neutral stance from one broker show the market is starting to price in progress. However, a history of one off items, slower forecast revenue growth and an uneven dividend record keep the risk side of the ledger very much alive.
Even so, there is one uncomfortable piece of the V.F story that still hangs over all of this progress...
There's only one way to know the right time to buy, sell or hold V.F. Head to Simply Wall St's company report for the latest analysis of V.F's Fair Value.
Exploring Other Perspectives
One alternate story on V.F. Corporation focuses squarely on revenue pressure. The most pessimistic analysts were pencilling in fairly flat sales near US$9.3b and earnings of about US$414.3m, or US$1.02 per share, by 2029. That is a stricter bar than consensus and it shows how sharply opinions can diverge. You are seeing pre news estimates, so use this quarter as a prompt to compare those harsher assumptions with your own view of the turnaround and to explore several different analyst takes.
Explore 2 other V.F fair value estimates, including one that suggests it could be worth just $19.65.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your V.F research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for V.F. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate V.F's overall financial health at a glance.
Looking For More Investment Ideas Beyond V.F?
Once you have a view on V.F, it can help to compare that thinking with other opportunities that match your risk, income, and balance sheet preferences using the Simply Wall St Screener.
- If capital preservation sits high on your list, start by reviewing a group of companies with steadier profiles through our 30 resilient stocks with low risk scores.
- If value is your focus, weigh V.F against businesses that pair stronger fundamentals with pricing that looks more modest using the 30 high quality undervalued stocks.
- If you prefer to hunt for earlier stage opportunities, contrast this turnaround with a carefully filtered set of smaller stocks screened for resilience via the 9 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com