
Is Georgia Capital (LSE:CGEO) Undervalued As Net Income Jumps In Q3?
Why Georgia Capital’s latest earnings matter now
Georgia Capital (LSE:CGEO) put fresh numbers on the table with third quarter and nine month results, reporting GEL 794.22 million in Q3 net income and GEL 1,514.86 million for the year to 30 September 2026.
Those figures compare with GEL 215.75 million and GEL 1,247.96 million in the same periods a year earlier. For investors, the size of that gap is hard to ignore when weighing what the current £45.50 share price implies.
Recent trading tells its own story. Georgia Capital’s share price is up 3.53% over the past day and 9.11% over the week, yet down 3.60% over the month. The year-to-date share price return of 47.25% sits alongside a very large 5-year total shareholder return of 654.56%, which points to momentum that has been building rather than fading.
Scan how Georgia Capital compares with other potential breakouts by checking a curated list of 10 high quality undervalued stocks that pair upside potential with solid fundamentals.
Bulls see Georgia Capital’s earnings jump and long run of strong shareholder returns and argue the stock still looks cheap. Bears point to the rapid share price move and ask whether the valuation already reflects the good news.
Price-to-earnings of 2.1x: Is it justified for Georgia Capital?
On a simple earnings lens, Georgia Capital looks inexpensive, with a P/E of 2.1x at a £45.50 share price while peers change hands at far richer levels.
The P/E ratio compares what investors pay today for each unit of current profit. For an investment group like Georgia Capital, which is posting profits and has a track record of earnings growth over the past year and the past five years, this yardstick gives a direct read on how the market is pricing those profits.
Here, the gap is wide. The stock trades on a 2.1x P/E against a peer average of 8.7x and a UK Capital Markets industry average of 12.2x. That kind of discount implies investors are paying far less for each unit of Georgia Capital’s earnings than they are for comparable businesses, even though earnings grew 25.6% over the past year and have risen strongly over five years.
Given that spread, the market is assigning a low earnings multiple relative to both peers and the wider industry. This points to the current valuation looking undemanding based on this measure.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 2.1x (UNDERVALUED)
Still, if Georgia Capital’s earnings prove cyclical or portfolio exits slow, the low P/E could linger, and sentiment around the £1.33b group could cool.
Find out about the key risks to this Georgia Capital narrative.
Another view on Georgia Capital’s value
The story shifts when you look at Georgia Capital through the SWS DCF model. From this perspective, the £45.50 share price sits below an estimated future cash flow value of £67.05, which suggests the shares are trading at a clear discount. Is the market underestimating that cash generation, or pricing in risks that are not yet visible?
Look into how the SWS DCF model arrives at its fair value.
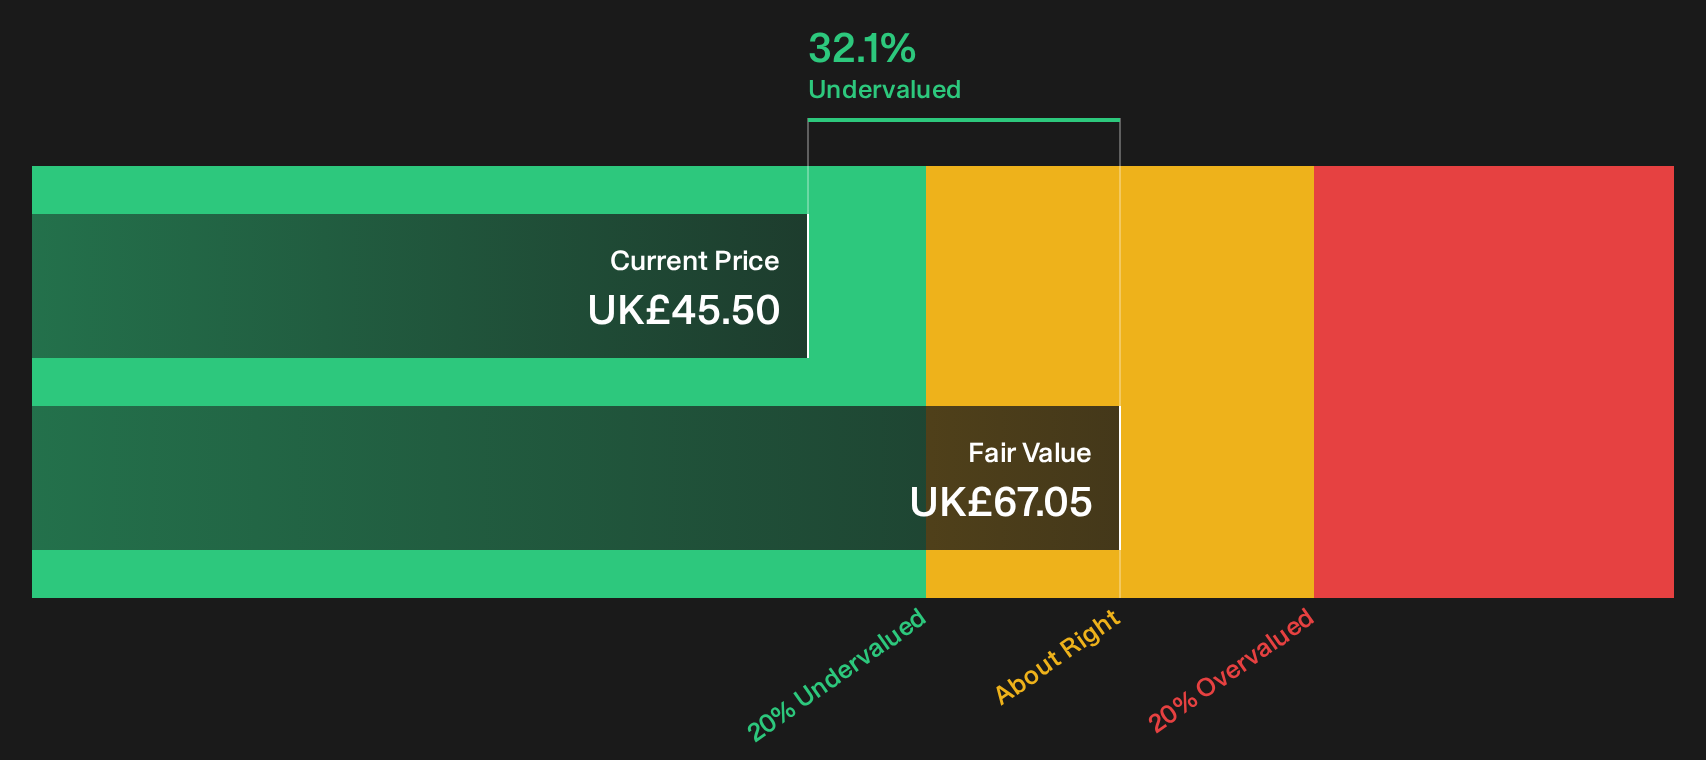
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Georgia Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 10 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear opportunity? If the debate around Georgia Capital has you on the fence, move quickly, review the full picture, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Georgia Capital?
Broaden the opportunity set and pressure test Georgia Capital against other candidates by scanning a wider pool of stocks through the Simply Wall Street Screener.
- Chase underappreciated quality by scanning a curated set of 10 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Build a sturdier core in your portfolio by zeroing in on a list of solid balance sheet and fundamentals (10 results) that can better handle shocks when conditions change.
- Get ahead of the crowd by searching a 5 high quality undiscovered gems where strong fundamentals have not yet attracted broad market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com