
Fortinet (FTNT) Stock Price Sinks After Q3 Results Cut Through Growth
Fortinet just dropped its Q3 2026 scorecard and the market did not like it. The stock shed about 20% in a single session, sliding to around US$139, even though the company posted roughly US$2.08b in quarterly revenue and about US$0.87 in basic earnings per share. For a cybersecurity heavyweight that trades on premium expectations, this looks less like a collapse in the business and more like a sentiment reset as investors rethink how much they are willing to pay for that growth profile.
Love Fortinet's scale in cybersecurity but uneasy about paying a premium after a 20% one day slide? You can benchmark this reaction against peers by checking a curated 30 resilient stocks with low risk scores.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$2,078.4m vs. US$1,724.9m (up about 20%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$635.5m vs. US$473.9m (up about 34%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.87 vs. US$0.63 (up about 38%)
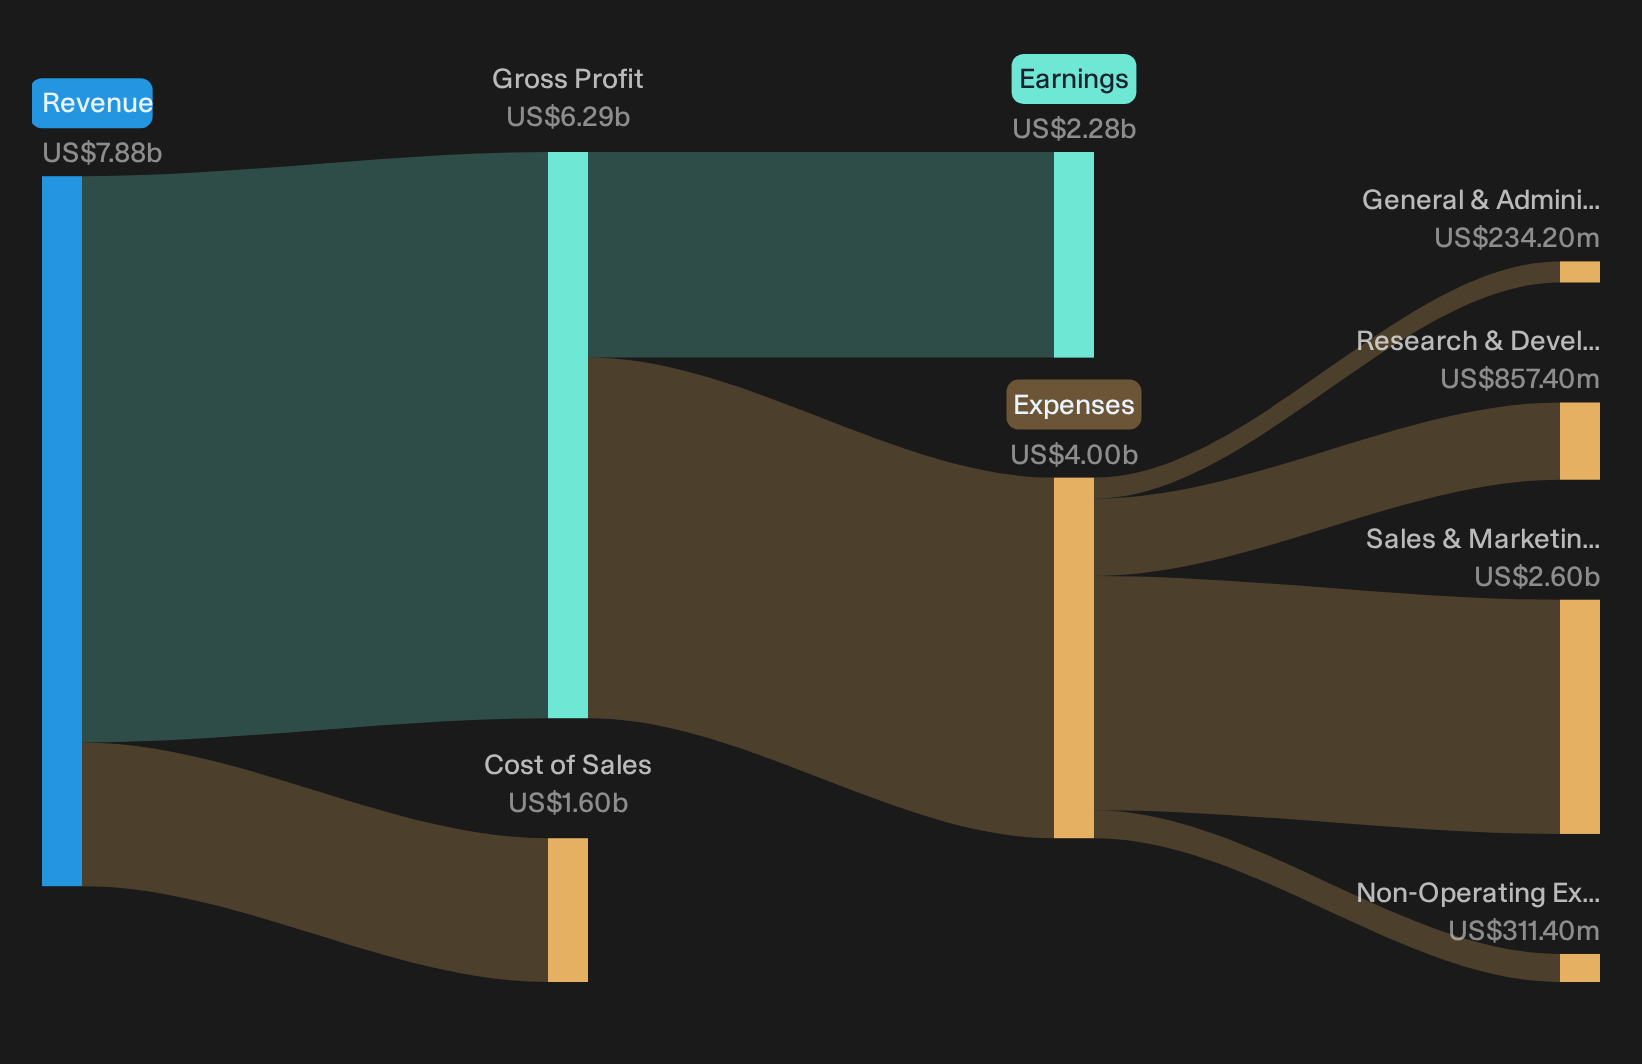
- Trailing 12-Month Net Income, Excl. Extra Items (Q3 2026 TTM vs Q3 2025 TTM): US$2,282.3m vs. US$1,873.6m (up about 22%)
Fortinet raised guidance again on a surge in AI-focused demand. Ask Charlie what Fortinet’s AI security cycle really changes for growth.
Evaluating Fortinet’s Recurring Security Scale Milestone
Fortinet’s bullish narrative hangs on turning security scale into a richer subscription engine rather than just selling more boxes.
"The main factor that has to go right is that Fortinet continues to convert its secure networking, Unified SASE, OT security, and post quantum features into expanding service adoption and attached subscriptions on its FortiGate base."
Q3 billings show real progress toward that target. Service billings grew 26% with double digit gains in total deferred revenue and the strongest short term deferred balance in five quarters. That pattern signals more FortiGate customers signing up for subscriptions, even as reported service revenue growth and full year guidance lag product driven hardware demand.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Fortinet Bear Case: Service Momentum Still On Trial
Bears argue Fortinet’s hardware led model will struggle if buyers pivot harder to cloud delivered suites and weaker service attachment. That risk is squarely about mix and durability of recurring income, not just headline growth.
"Bearish analysts expect Fortinet’s hardware led model to see pressure as more security budgets shift toward cloud delivered platforms and consolidated suites, which can limit pricing power and long term revenue contribution from FortiGate appliances."
Q3 results cut against that thesis on volume and profitability, with billings up 29% and non GAAP operating margin at 38.2%. The miss is in the composition. Service revenue grew only 13% and full year service guidance was trimmed, so high margin recurring scale still has to prove itself.
Hunt For Mispriced Growth Stories
Fortinet recently showed how reported results can still clash with shifting expectations. The real opportunity sits in finding stocks that could be undervalued before fresh information forces a reprice.
- Company 1 - 36% below our estimate - uses new high horsepower capacity and HELM engines to secure long term power contracts.
- Company 2 - 32% below our estimate - supplies AI superclusters that a leading model developer relies on to scale training workloads.
- Company 3 - 20% below our estimate - expands production and access for incretin based obesity and cardiometabolic drugs and develops oncology and neuroscience therapies.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com