
McGrath RentCorp (MGRC) Stock Shrugs Off Q3 Earnings Strength
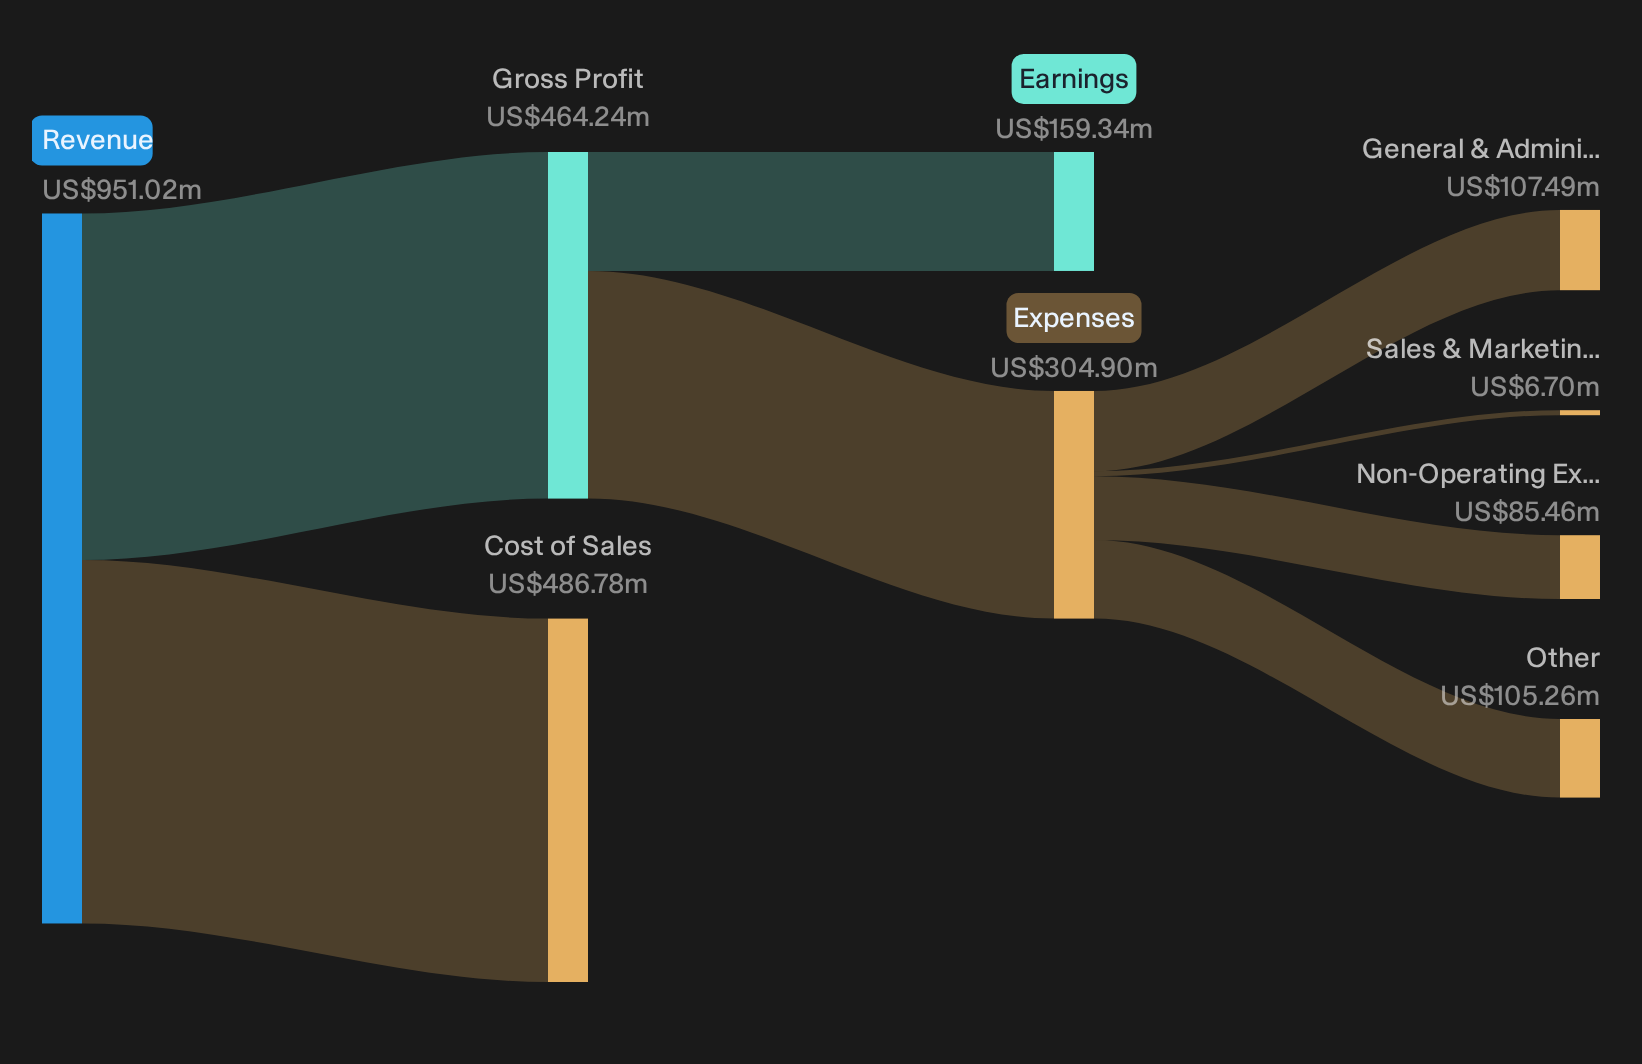
McGrath RentCorp stock barely budged after Q3 2026 earnings, ticking up just 0.7% to about US$119.60. That is a muted move for a quarter where revenue reached roughly US$274.6 million and basic earnings per share landed near US$2. The market treated it as business as usual. The financials tell a different story.
Short timers will focus on the modest price reaction. Long horizon investors will look at the stronger rental driven engine underneath, the 16.8% net margin over the last year, and a P/E of 18.3x that sits well below rental peers. The tension between those two lenses is where both the opportunity and the risk live.
Like the combination of McGrath RentCorp’s 16.8% net margin and rental driven model, but wary that an 18.3x P/E could still leave room for error? Compare it with a curated list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Total Revenue, Q3 2026 vs Q3 2025: US$274.6 million vs. US$256.4 million (up about 7%)
- Net Income, Q3 2026 vs Q3 2025: US$48.8 million vs. US$42.3 million (up about 15%)
- Basic EPS, Q3 2026 vs Q3 2025: US$2.00 vs. US$1.72 (up about 16%)
- Net Margin, Trailing 12 Months vs Prior Year: 16.8% vs. 15.6% (net profitability improved year over year)
Prefer clean visuals instead of another wall of earnings tables and ratios. See McGrath RentCorp’s full financial picture, including how its valuation lines up with recent profit trends, in a streamlined company report for McGrath RentCorp..
McGrath RentCorp rental engine clears key growth bar
Optimists argue McGrath RentCorp can turn project wins into durable rental momentum, not just a good year.
"The main thing that has to go right is that Mobile Modular and TRS-RenTelco continue to convert early traction in expansion markets, higher revenue per unit, and mega project demand into sustained utilization and EBITDA growth, while Portable Storage and Enviroplex gradually stabilize."
Q3 points in that direction. TRS rental revenue rose 26% with utilization near 70% and materially higher rental margins. Mobile Modular rental revenue grew even as modular sales softened, helped by higher revenue per unit and expansion projects. Enviroplex swung back to solid sales and EBITDA, easing the drag concern.
Portable Storage and utilization keep the bear case alive
On the risk side, the worry is that weaker pockets never really heal and quietly cap McGrath RentCorp’s earnings power.
"Portable Storage continues to face weak small local commercial construction activity and low industry utilization, with flat rental revenue of US$17 million, utilization at 58.3% and a 23% decline in adjusted EBITDA in Q2 2026. This could limit McGrath RentCorp’s ability to grow consolidated revenue and may keep EBITDA margins under pressure if these end markets do not recover."
Q3 shows only a partial offset. Portable Storage revenue slipped 3%, EBITDA fell 20% and utilization stayed below prior year despite a sequential uptick. Consolidated EBITDA guidance held, yet it relies heavily on TRS outperformance to counter this lingering drag.
The price and this Narrative do not agree. → Uncover what this Narrative says McGrath RentCorp is actually worth.
Hunt For Quiet Mispricings
McGrath RentCorp just showed how a steady rental engine and a flat share price can coexist. The real opportunity is hunting for companies that could be undervalued before the market closes the gap.
- Company 1 - 36% below our estimate - uses government backed trade in programs and refurbishing tech to pull more used devices into organized recommerce channels.
- Company 2 - 24% below our estimate - sells diagnostic gear and components utilities adopt as they upgrade grids, electrify transport and harden critical systems.
- Company 3 - 25% below our estimate - ties networking hardware and consumption based services to rising AI data center demand and long term infrastructure contracts.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com