
Amotiv Shares Slid Even Though It Turned A Profit
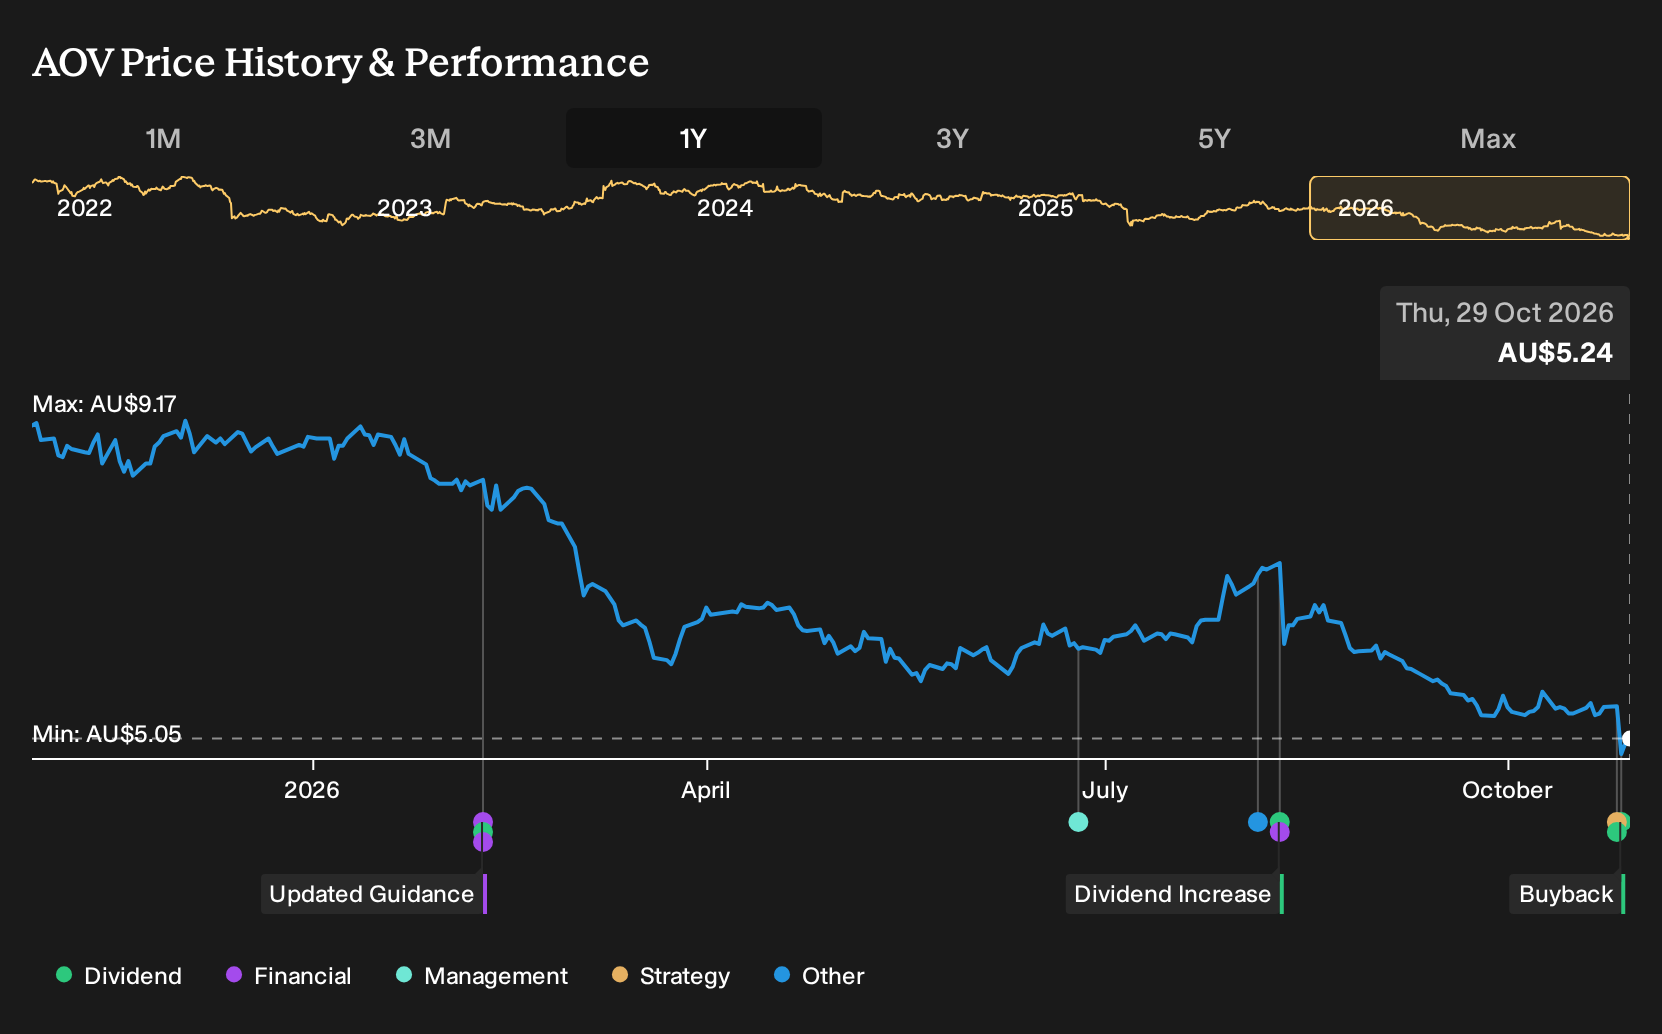
Amotiv was not short of strong opinions when the period began, with bulls focused on electrification and ADAS exposure and bears worried about legacy exposure and customer concentration. Holding Amotiv over the past year would have meant a 39.1% loss, including dividends. If you had bought on those August 2025 research views, what did the original case miss about execution risk, capital allocation and the mix between high-tech and legacy segments?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Amotiv. Zero in on 2 high quality undervalued stocks for companies trading below our estimates.
The Two Amotiv Stories Investors Had To Weigh
The shares cost A$9.11 at the start of the period, and anyone looking at Amotiv then was really choosing between two grounded but very different stories.
The bullish narrative put fair value at A$13 and leaned on electrification and ADAS. Supporters focused on offshore expansion, the new South African facility ramping ahead of schedule, and Amotiv Unified programs aimed at a leaner cost base.
The bearish view pinned fair value at A$7.5 and stressed legacy exposure. Critics highlighted reliance on internal combustion components, customer concentration with large OEMs, and rising regulatory costs that could squeeze profitability.
What The Results Changed For Amotiv
The swing from a net income loss of A$139.3 million in H2 2025 to a profit of A$29.1 million in H2 2026 gave Amotiv bulls fresh support on execution and cost control, especially with net margin improving from a 28.2% loss to a 5.8% profit. The newly announced buyback plan for up to 5% of shares reinforced capital discipline, so the evidence cut both ways for the more cautious case on legacy risk.
The key assumption investors can apply to other stocks is execution on profitability. When a story hinges on better capital allocation and cost efficiency, investors can track net margin trends and actual buyback authorisations against the original claims, rather than focusing only on revenue lines or share price moves.
What You Are Paying For In Amotiv Today
At A$5.24, Amotiv is priced well below where it traded a year ago. The selected Narrative’s Fair Value sits above the current price and reflects a more optimistic view of its electrification and offshore mix.
This argument leans on Amotiv Unified cost savings, offshore earnings breadth and disciplined reinvestment. A buyer today must judge whether those efficiency gains and portfolio shifts can be maintained.
"The main thing that has to go right is continued delivery of Amotiv Unified cost savings and disciplined capital allocation so that efficiency gains, portfolio reshaping and offshore expansion together support earnings and cash generation."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Amotiv
With Amotiv, you see how electrification reshapes what actually gets built. The visible focus is hardware, yet drivers also need confidence and convenience.
Here, another business quietly steps in. It builds electric vehicles closely linked to charging, swapping and bundled service packages.
Customers are not simply buying a car. They are choosing a way to keep it powered, maintained and upgraded with less hassle.
As more buyers care about the full ownership experience, a model built around recurring energy and service usage could become far more important.
That argument has a Narrative and a number behind it. → See the company one Narrative values 88% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com