
3 Eurozone Bank Stocks For Higher ECB Rates
Eurozone bank stocks sit at a tricky crossroads as the ECB holds its deposit rate at 2.5% while inflation and energy costs heat up, and that mix can quietly reshuffle winners and laggards in your portfolio. Higher policy rates affect funding costs, loan demand and credit quality in very different ways. This piece walks through how that backdrop links to three specific Eurozone bank stocks exposed to these forces and why they might deserve a closer look now.
The stocks highlighted next are just a small sample, and the full screen surfaced 18 more Eurozone bank companies with similarly detailed stories that are not covered here.
If you want to quickly identify which Eurozone bank stocks best fit your own thesis on ECB policy, head straight into the Eurozone Bank Stocks screener to filter, analyze, and focus on your highest conviction ideas.
Banca Monte dei Paschi di Siena (BIT:BMPS)
Overview: Banca Monte dei Paschi di Siena is an Italian lender focused on classic deposit taking, mortgages, and corporate lending that closely link its earnings to ECB interest rate decisions.
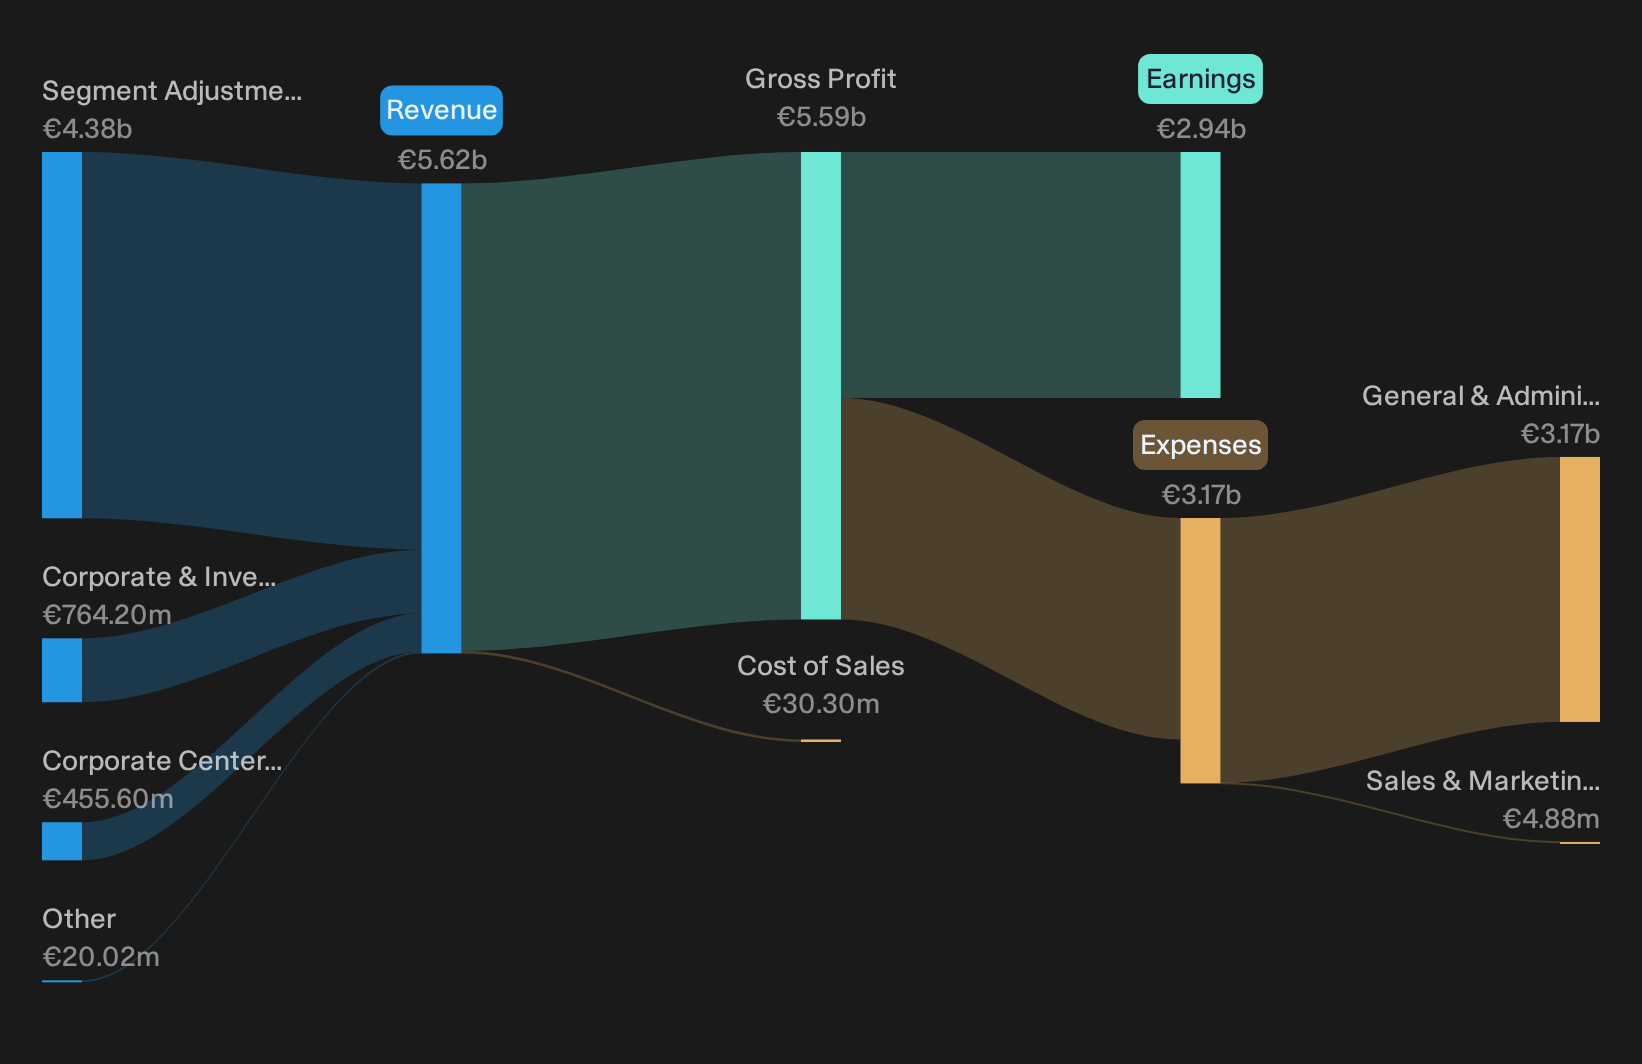
Operations: The group reports €4.4b from Segment Adjustment, €456m from the Corporate Center and €764m from Corporate & Investment Banking activities.
Market Cap: €33.1b
For the Eurozone Bank Stocks theme, Banca Monte dei Paschi di Siena is a focused way to gain exposure to higher-for-longer ECB rates feeding into a traditional loan and deposit engine, with an additional narrative around how it reshapes its cost base and fee mix through large bank combinations.
"Execution of the Mediobanca integration, with targeted annual synergies of €700 million by 2028 and early progress already reported, is set to affect Banca Monte dei Paschi di Siena’s cost base and support net margin resilience."
The impact on future earnings power could be significant if a single assumption about how quickly that broader consolidation plan comes together changes.
If that integration timing is what you are watching, read the full narrative for Banca Monte dei Paschi di Siena to see how capital actions and fee shifts could be accelerating under the surface.
Bankinter (BME:BKT)
Overview: Bankinter is a Madrid based lender that serves retail, SME and corporate clients across eurozone markets, closely tying its earnings to ECB interest rate decisions.
Operations: Bankinter generates €1.32b from Wealth Management and Retail Banking, €1.03b from Corporate & SME Banking, €380 million from Portugal and €123 million from Ireland, with smaller contributions from other segments.
Market Cap: €12.7b
Bankinter matters for this Eurozone Bank Stocks theme because its retail and SME focused model links earnings closely to ECB policy, so any shift in the rate path quickly feeds through to what it earns on loans versus what it pays on deposits.
"Accelerating adoption of digital and AI technology, supported by Bankinter investing over 10% of gross revenues in technology and AI, is allowing customer volumes to expand far faster than headcount and branches."
How that digital efficiency interacts with ongoing pressure on funding costs could be a key factor for future margins.
That pressure point is exactly what the full narrative for Bankinter unpacks in depth, highlighting where funding costs, digital scale and capital allocation may be quietly decoupling.

Banco BPM (BIT:BAMI)
Overview: Banco BPM is an Italian universal bank that ties eurozone interest rates directly into everyday lending, savings, insurance and investment services for households and businesses.
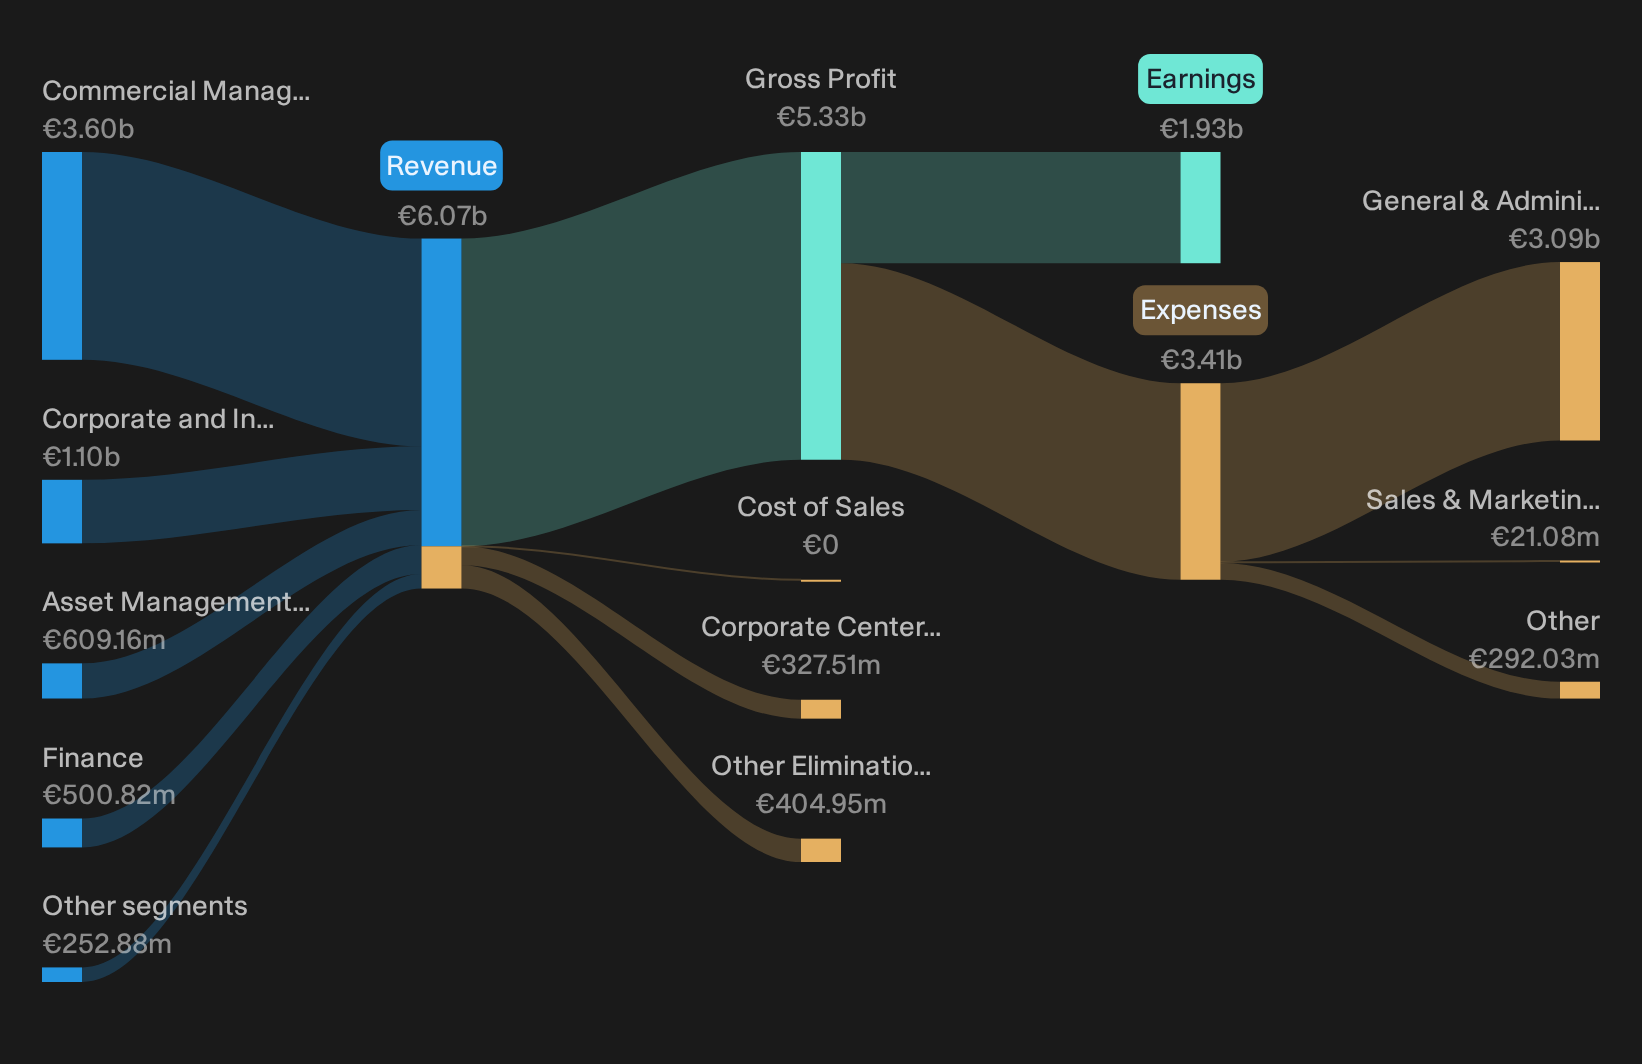
Operations: Banco BPM earns most of its €5.7b revenue from Commercial Management at €3.6b and Corporate and Investment Banking at €1.1b, with Finance and Asset Management adding about €1.1b together.
Market Cap: €20.7b
Banco BPM is one of the clearest Eurozone Bank Stocks plays on higher ECB rates feeding into Italian retail and corporate lending. Its story now also leans heavily on how fee income and capital strength can soften the impact if that rate tailwind fades.
"Expansion of Banco BPM’s fee and insurance offering through its product factories, after non net interest income reached 52% to 53% of total revenues in H1 2026 and product factory revenues moved close to the 2027 target, could continue to support revenue mix resilience and reduce earnings sensitivity to net interest income."
What happens if a single pressure point in that balance between loan spreads and risk costs shifts will matter a lot for Banco BPM’s margins.
When that risk reward balance feels finely poised, the full narrative for Banco BPM shows how Banco BPM’s fee engine, capital moves and rate sensitivity could be quietly accelerating.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes attract momentum traders, then liquidity thins and spreads widen once everyone has caught on. Scan these under the radar lists while it matters and get in early.
- Spot income workhorses built on steady cash flows and payout history through the 229 dividend fortresses before yield hunters push the strongest options out of reach.
- Track early leaders supplying the physical backbone of AI demand with the 54 AI infrastructure stocks while core beneficiaries are still priced as ordinary industrials.
- Target miners that can participate in any renewed metal momentum through the 35 elite gold producer stocks before stronger margins and project upgrades draw broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com