
Gen Digital (GEN) Stock Rallies As Q2 Results Deliver Margin Strength
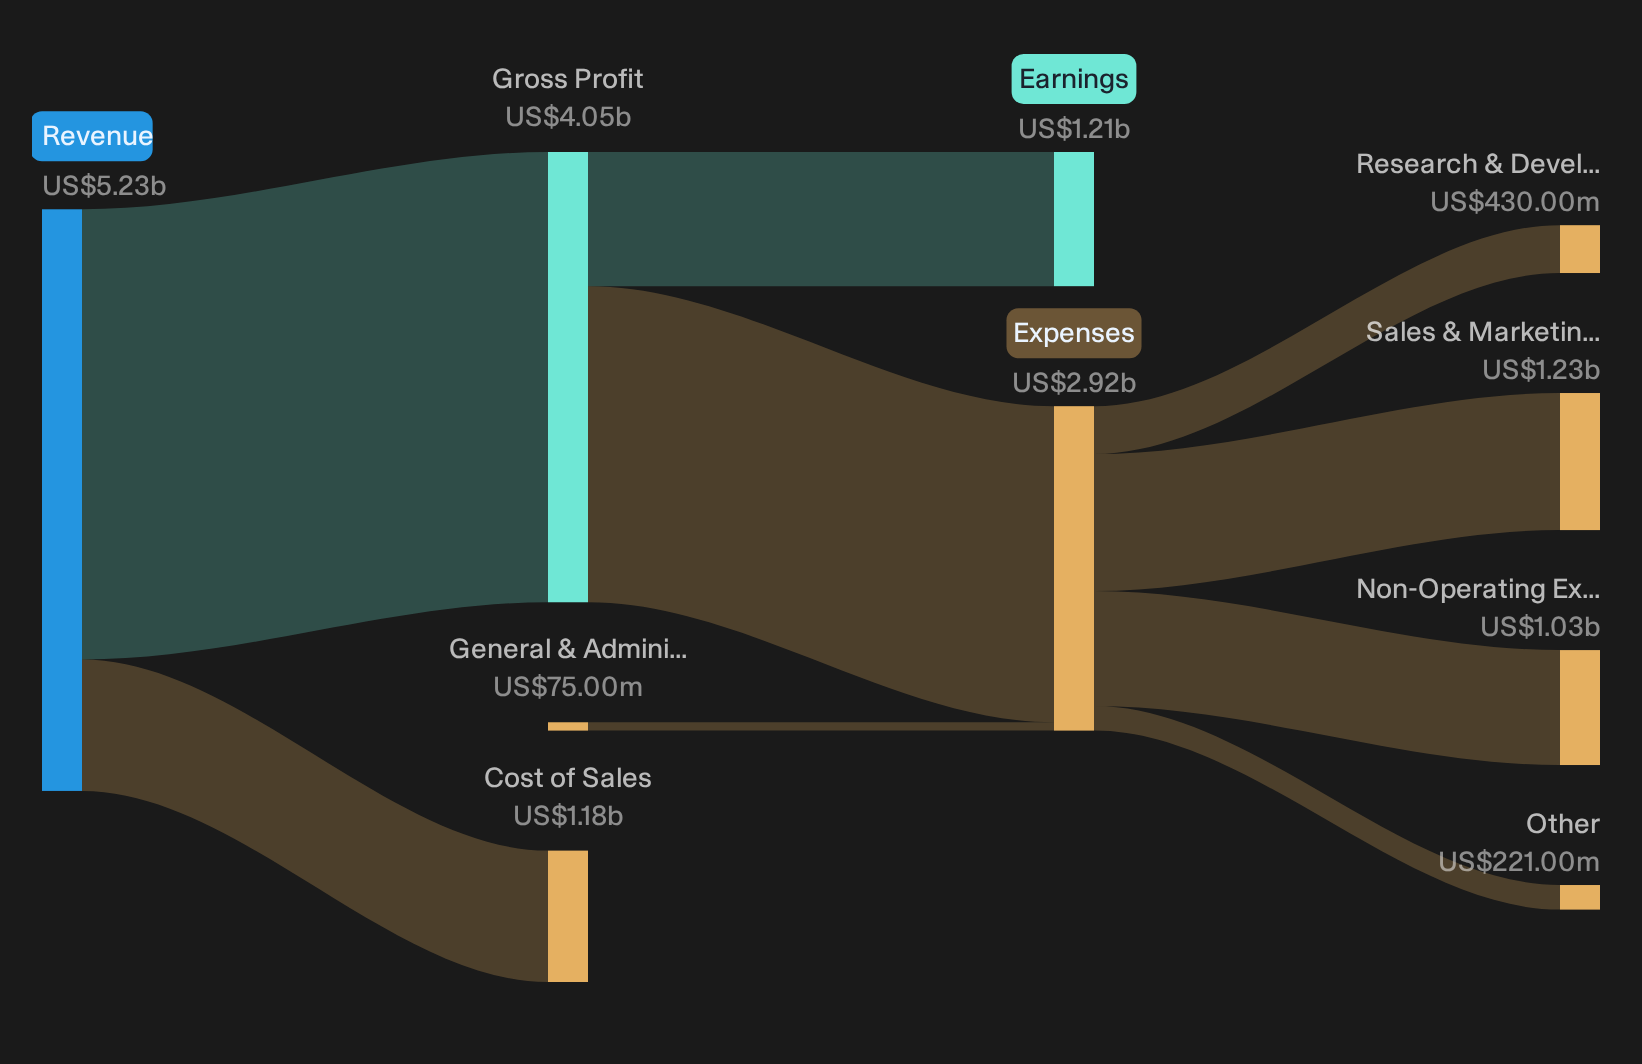
Gen Digital just released Q2 2027 results and the stock jumped 15.8% to close at US$28.20. That is a big move for a cyber security and consumer privacy business in a single session. The headline story is straightforward: revenue reached US$1.37b and non GAAP earnings per share came in at US$0.74, both aligned with a strong quarter rather than a one off spike. The key sentiment driver is profitability. Investors appear to be paying up for a richer margin profile and treating this jump in the share price as a catch up, not a sugar high.
Like the look of Gen Digital’s strong margins but want a richer mix of quality security stocks with resilient balance sheets too? You can filter for peers with both profitability and solid fundamentals using our list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$1,369m vs. US$1,220m (up 12.2%)
- Net Income, excl. extra items (Q2 2027 vs. Q2 2026): US$287m vs. US$134m (up 114%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.48 vs. US$0.22 (up 121.3%)
- Non GAAP Operating Margin (Q2 2027 company level vs. segment benchmark): approximately 50% company margin compared with 62% Cyber Safety segment margin and approximately 30% Trust Based Solutions segment margin (higher profitability in Cyber Safety, solid margin in Trust Based Solutions)
Earnings give you the headline, but investors who care about Gen Digital's valuation often focus on the cash flowing through the business over time. On Gen Digital's recent cash flows alone, the stock could be a whopping 43% undervalued.
Gen Digital’s Membership Flywheel Clears Key Hurdles
The bullish pitch hangs on whether Gen Digital can really scale richer memberships and embedded channels without losing momentum with users and partners.
"The main thing that has to go right is that Gen Digital continues to scale its higher value membership and embedded marketplace models across Cyber Safety and Trust Based Solutions without eroding customer trust or partner momentum."
Q2 points in the right direction. Paid customers rose to 83 million, and higher tier upsells lifted ARPU in Cyber Safety, while that segment held a 62% operating margin. Trust Based Solutions revenue and bookings both grew in the mid 20s. Partner channels reached about US$295m, more than 20% of total revenue, with 40% growth that suggests healthy distribution rather than fatigue.
The price and this Narrative do not agree. → Uncover what this Narrative says Gen Digital is actually worth.
Gen Digital Bear Case: Security Wobbles, Pricing Power Intact
Bearish investors argue Gen Digital risks losing pricing power as free tools and baked in device protection keep getting better. That concern focuses squarely on the paid membership engine.
"Bearish analysts expect free cybersecurity tools and native device protections to keep pressuring Gen Digital's core subscription business and limit its ability to charge premium pricing for stand-alone products."
Q2 data does not yet back that up. Paid customers reached 83 million and higher tier upsells in Cyber Safety lifted ARPU while the segment still carried a 62% operating margin. That combination of more subscribers, richer bundles and record profitability leaves the pricing pressure thesis unproven in this quarter.
Hunt For Mispriced Earnings Power
Gen Digital just showed how quickly sentiment can reset when a profit story aligns with stronger membership traction. The real opportunity is spotting stocks that could be undervalued before more investors focus on their earnings power.
- Company 1 - 40% below our estimate - expand a solar tracker and control platform as storage, inverters and newer offerings deepen project relationships.
- Company 2 - 20% below our estimate - grow a teahouse network as overseas venues, membership programs and supply services reshape franchise and company store economics.
- Company 3 - 26% below our estimate - add banking customers as card spending, digital engagement and new-market breakeven pull more activity onto one platform.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com