
Chipotle (CMG) Stock Price Jumps As Q3 Results Tighten Margins
Chipotle Mexican Grill just dropped its Q3 2026 scorecard, and the share price fired 8.9% higher to US$31.28 the very next trading day. That kind of spike screams enthusiasm. The twist is that adjusted earnings per share landed at US$0.27 while restaurant level margin sat at 23.3%, both under pressure from higher wages and heavier marketing.
What you are seeing is a sentiment rally wrapped around a margin squeeze. Traders are responding to the story and the growth playbook, even as the profit engine looks tighter than the headline move suggests.
Love the Chipotle momentum but concerned that higher wages and heavier marketing are eating into those restaurant level margins? Check out the list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,293.2m vs. US$3,003.4m (up about 9.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$339.9m vs. US$382.1m (down about 11.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.27 vs. US$0.29 (down about 6.2%)
- Restaurant Level Margin (Q3 2026 vs. Q3 2025): 23.3% vs. about 24.5% (down about 120 basis points)
Earnings tell part of Chipotle Mexican Grill's story, but investors who care about what they are paying for usually focus on the cash flowing through the business over time. When you line up Chipotle Mexican Grill's cash flows against the current share price, the stock could be a slight 10% overvalued.
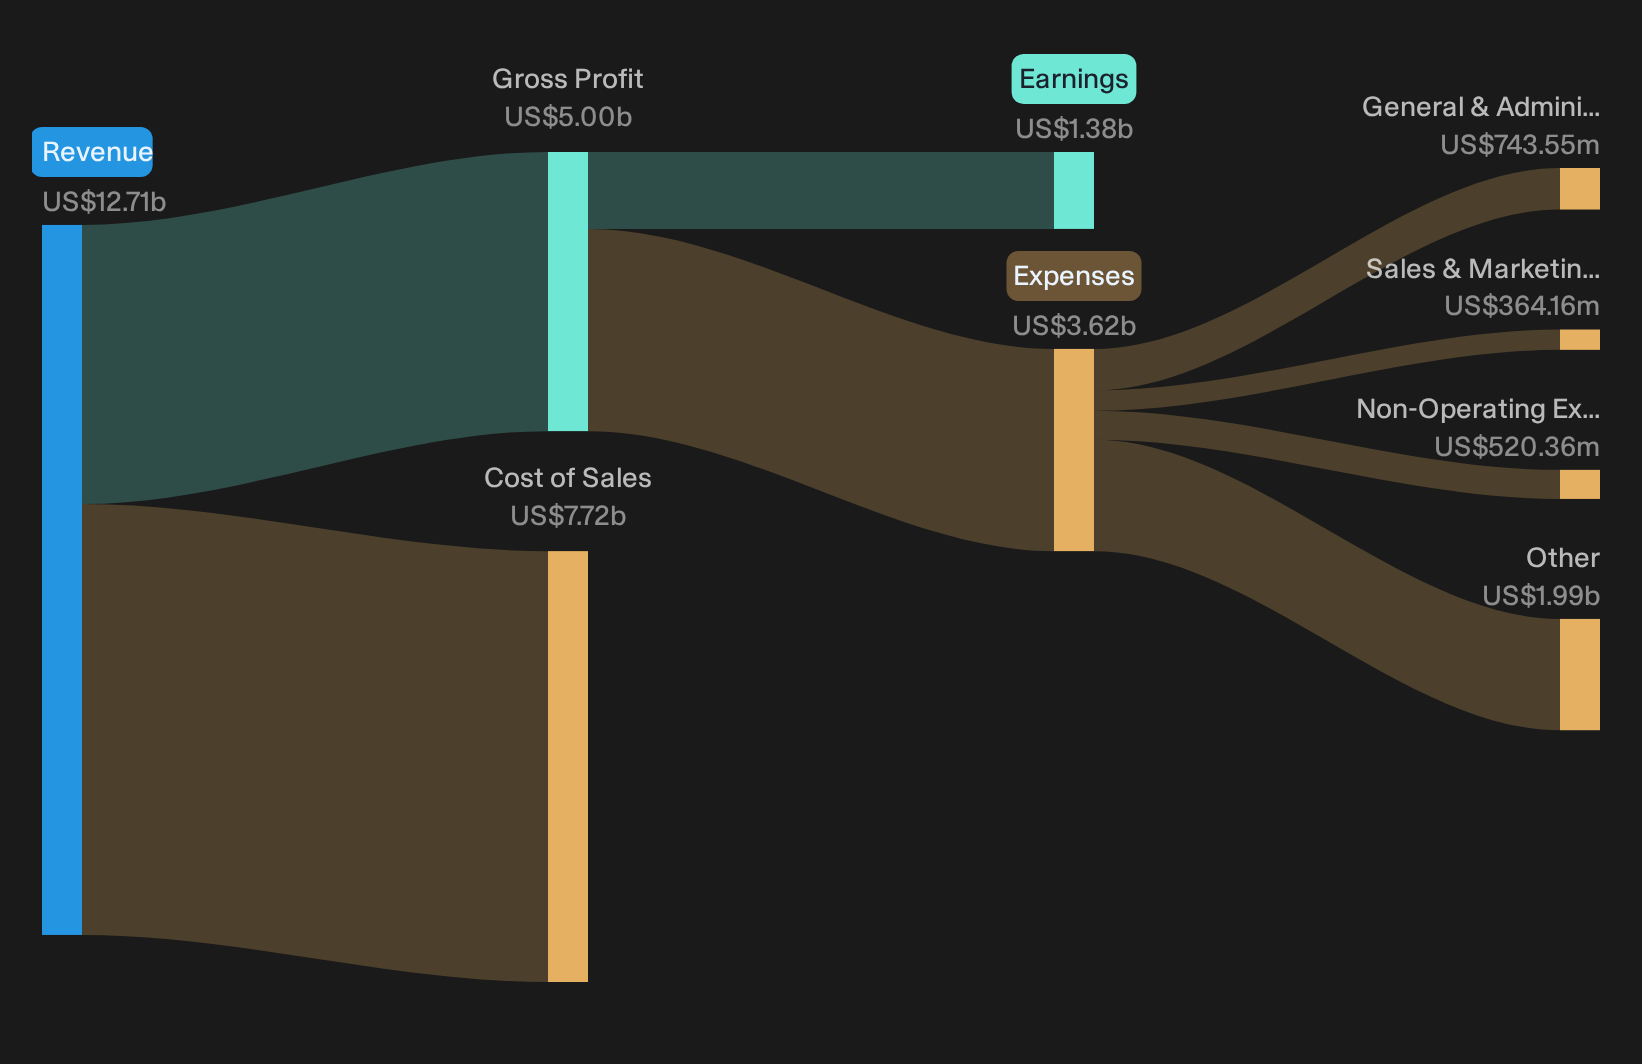
Evaluating Chipotle’s Growth Levers Against Q3 Milestones
"The main thing that has to go right is that investments in equipment, staffing, food safety, and loyalty translate into higher transactions and sustained new restaurant productivity, despite current margin pressure and softer traffic."
Chipotle Mexican Grill is starting to put points on the board against that ambition. HEEP now covers about 1,700 locations, with management citing several hundred basis points of comp uplift. Q3 transactions still edged up 0.8% and comps were 2.1% despite margin compression. Rewards passed 24 million active members and touched roughly one third of sales, supporting frequency even as promotions and redemptions lean on average check.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Chipotle Bear Case: Traffic Support, Margin Strain
The skeptical view argues Chipotle Mexican Grill is leaning too hard on promos and loyalty to keep guests coming, with little to show in sustainable traffic. That concern centers on how much discounting is required to win visits.
"Heavier dependence on digital engagement, gamified loyalty programs and promotions to reaccelerate visits among younger and lower income guests may drive costly incentive spend without sustainably restoring frequency. This would pressure both revenue quality and net margins."
Q3 data partly validates that worry. Transactions only grew 0.8% and comps were 2.1%, yet restaurant level margin slipped 120 bps while marketing and delivery related costs climbed, suggesting frequency help is coming with a profitability haircut.
Hunt For Disconnected Fundamentals
Chipotle Mexican Grill recently highlighted how share sentiment can outpace underlying profit margins. The real opportunity is focusing on stocks that could be undervalued when operational execution brings fundamentals closer to sentiment.
- Company 1 - 26% below our estimate - positions high performance connectivity, custom silicon and security as core infrastructure for data intensive workloads.
- Company 2 - 50% below our estimate - builds a focused aviation aftermarket platform by integrating acquisitions and expanding engine repair and distribution programs.
- Company 3 - 32% below our estimate - ties advanced accelerators to a proprietary AI software stack embedded in long term data centre infrastructure.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com