
Standex (NYSE:SXI) beats Q3 CY2026 sales expectations
Industrial manufacturer Standex (NYSE:SXI) reported calendar Q3 2026 (fiscal Q1 2027) results beating Wall Street’s revenue expectations, with revenue up 7% year on year to $232.6 million. Its non-GAAP profit of $2.41 per share was 3.2% above analysts’ consensus estimates.
For more on Standex, read our free full research report.
Standex (SXI) Q3 CY2026 highlights:
- Revenue $232.6 million vs S&P analysts’ consensus estimates of $229.5 million (7% year-on-year growth, 1.3% beat)
- Adjusted EPS $2.41 vs S&P analysts’ consensus estimates of $2.34 (3.2% beat)
- Adjusted EBITDA $51.2 million vs analysts’ consensus estimates of $51.78 million (22% margin, 1.1% miss)
- Operating margin 17.4%, in line with the same quarter last year
- Free cash flow margin 3.9%, similar to the same quarter last year
- Market capitalization $2.96 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Standex’s revenue grew at a tepid 5.9% compounded annual growth rate over the last five years, falling short of the rest of the industrials sector. Still, there are things to like about Standex.
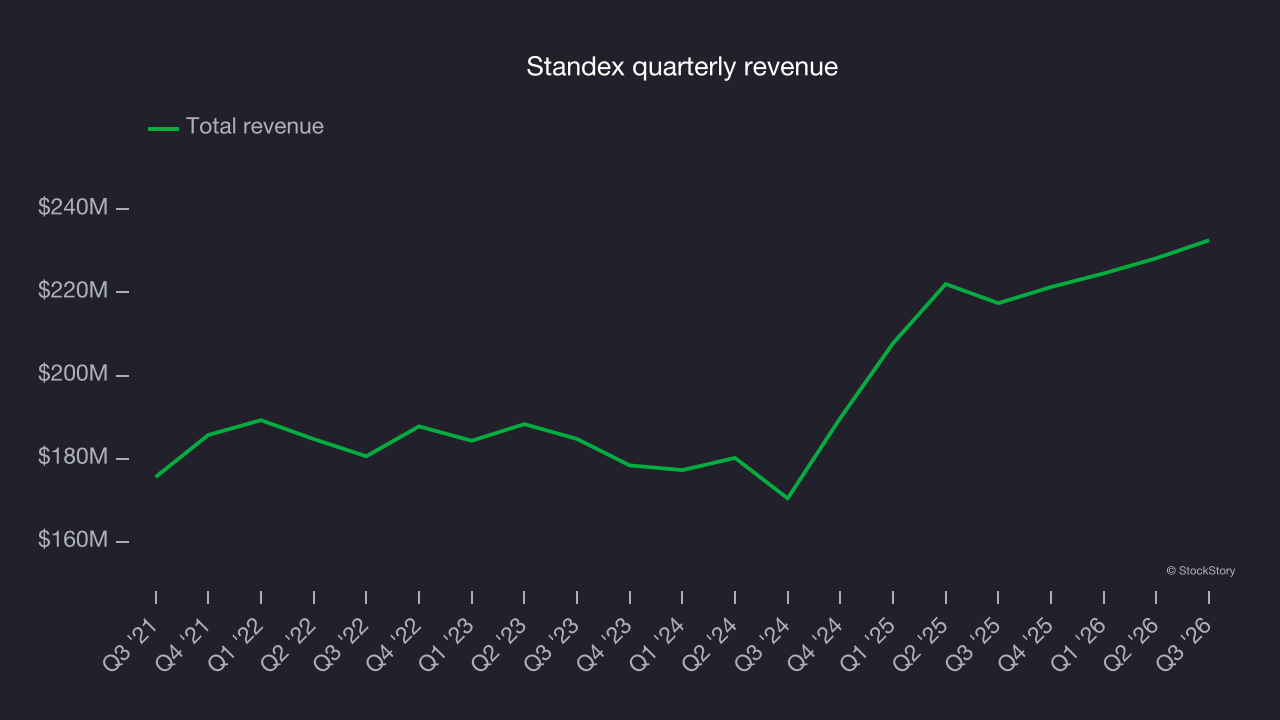
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Standex’s annualized revenue growth of 13.3% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 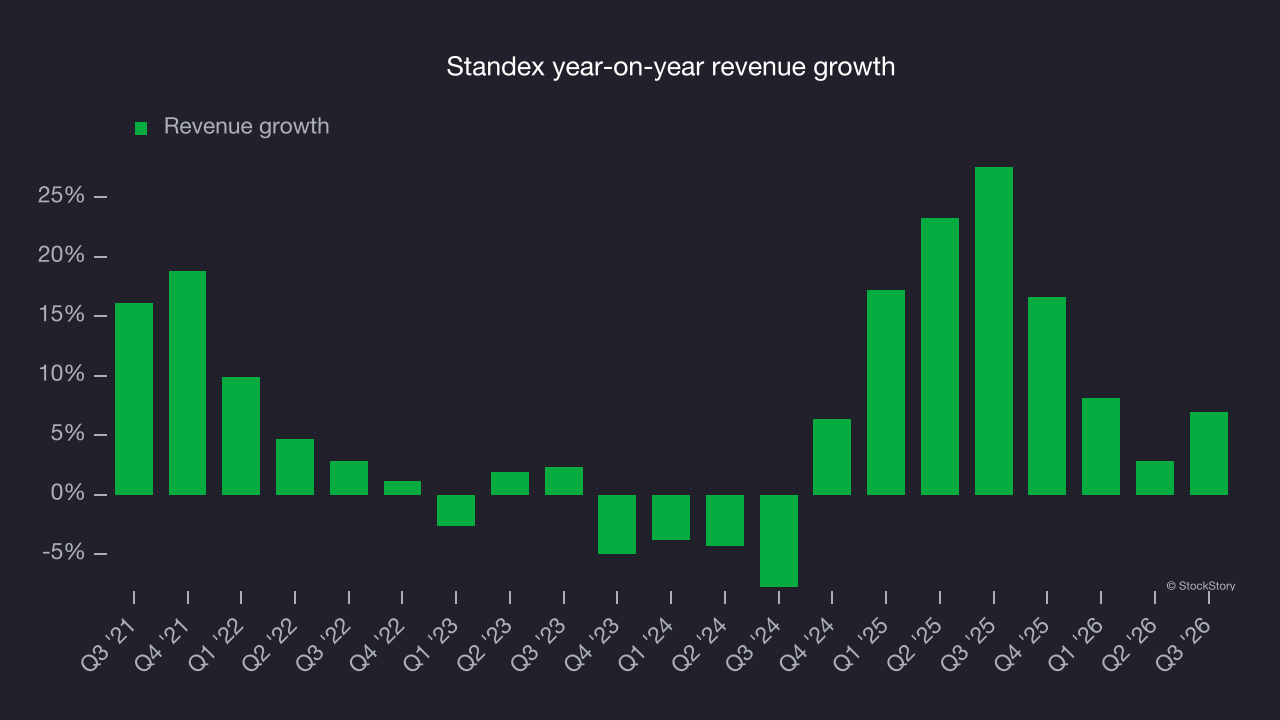
This quarter, Standex reported year-on-year revenue growth of 7%, and its $232.6 million of revenue exceeded Wall Street’s consensus estimates by 1.3%.
Looking ahead, sell-side analysts expect revenue to grow 6.8% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Standex has performed well over the last five years. It demonstrated strong profitability for an industrials business, with an average operating margin of 15.7%. This result is unsurprising given its favorable gross margin baseline.
Looking at the trend in its profitability, Standex’s operating margin rose by 3.2 percentage points over the last five years, as its revenue growth gave it operating leverage.
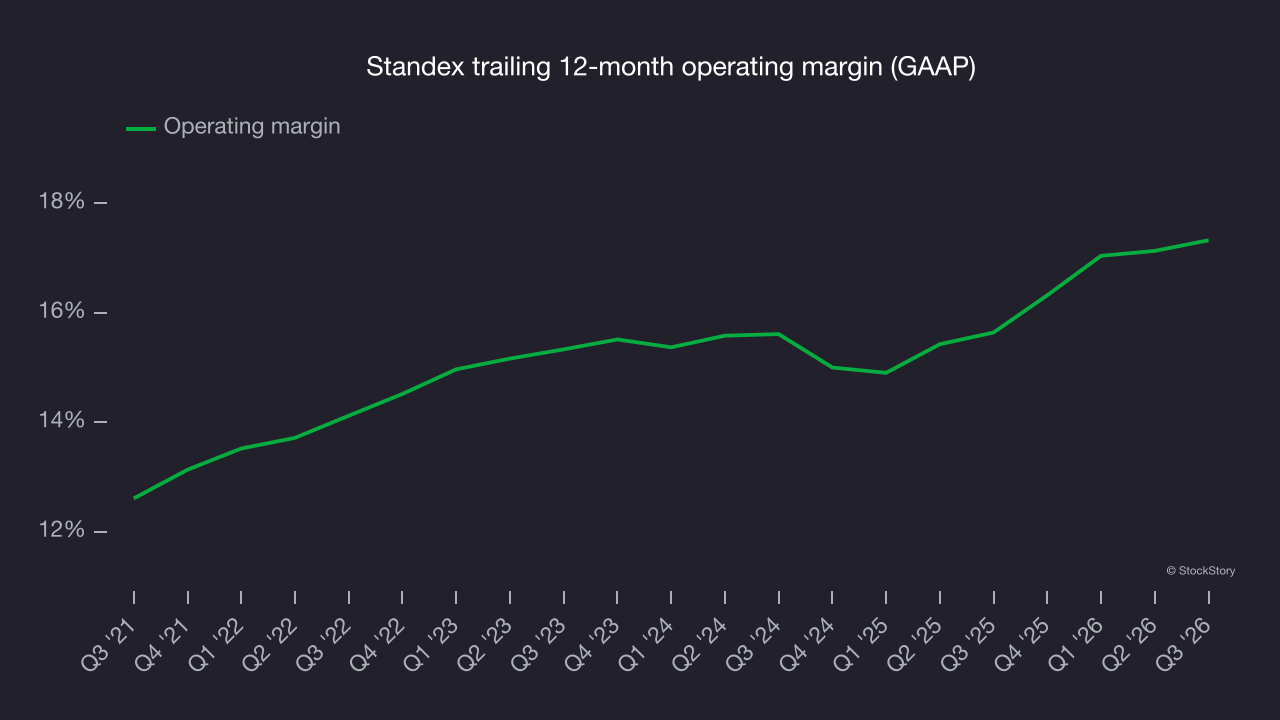
This quarter, Standex generated an operating margin of 17.4%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Standex’s EPS grew at a 12.9% compounded annual growth rate over the last five years, higher than its 5.9% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
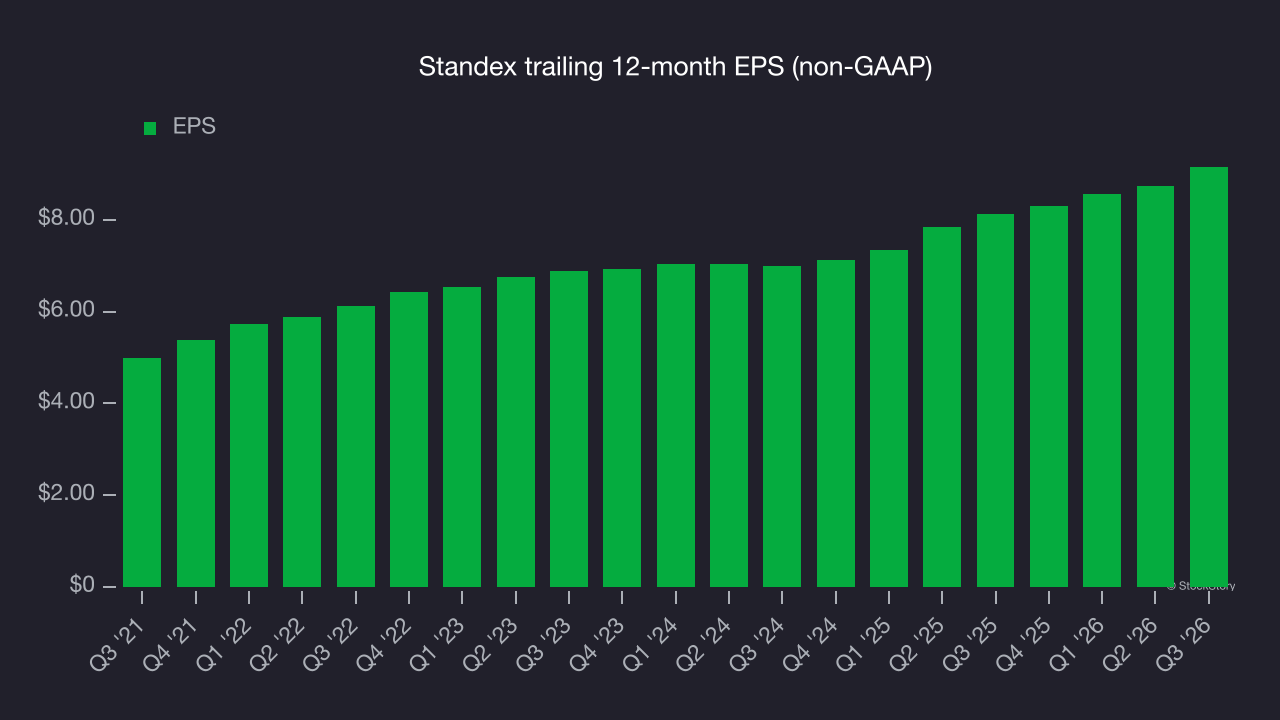
We can take a deeper look into Standex’s earnings to better understand the drivers of its performance. As we mentioned earlier, Standex’s operating margin was flat this quarter but expanded by 3.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Standex, its two-year annual EPS growth of 14.3% was higher than its five-year trend. That acceleration is a positive sign, especially from an already high base.
In Q3, Standex reported adjusted EPS of $2.41, up from $1.99 in the same quarter last year. This result beat analysts’ consensus estimates by 3.2%. Over the next 12 months, Wall Street expects Standex’s full-year EPS to grow 11.9% from $9.15 to $10.23, according to S&P.
Key takeaways from Standex’s Q3 results
Standex’s quarter was mixed: Revenue narrowly topped analysts’ consensus estimates and EPS beat Wall Street’s estimates, but EBITDA fell slightly short. Shares edged higher 1.4% to $251.52 immediately after the report.
Is Standex a buy at the current price? The latest quarter is only one piece of the longer-term business quality puzzle. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Standex, read our full research report here (it’s free).