
First Community Bankshares (FCBC) Stock Dips Despite Firmer Q3 Results
First Community Bankshares just reported Q3 2026, and the stock slipped 1.5% on the day. The move looks more like mood than math. The headline here is credit quality. Non performing loans came in at about US$15.8 million, below recent quarters, while the net interest margin held at 4.46%, a solid level for a regional bank.
Short term traders focused on the softer quarterly earnings per share. Longer term holders will likely pay closer attention to the improving problem loan trend and what that indicates about risk in the loan book.
Impressed by Love First Community Bankshares' solid 4.46% net interest margin but concerned about softer earnings per share this quarter? See how other banks combine firm credit quality with consistent profitability in our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$47.832 million vs. US$42.186 million (higher reported quarterly revenue)
- Net Income, excl. extra items (Q3 2026 vs Q3 2025): US$15.423 million vs. US$12.266 million (higher reported quarterly profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.82 vs. US$0.67 (higher earnings per share on a quarterly basis)
- Net Interest Margin, NIM (Q3 2026 vs Q3 2025): 4.46% vs. 4.43% (slightly stronger reported lending spread)
Earnings jumped, but forecasts now point downhill. Ask Charlie which risk stands out at First Community Bankshares.
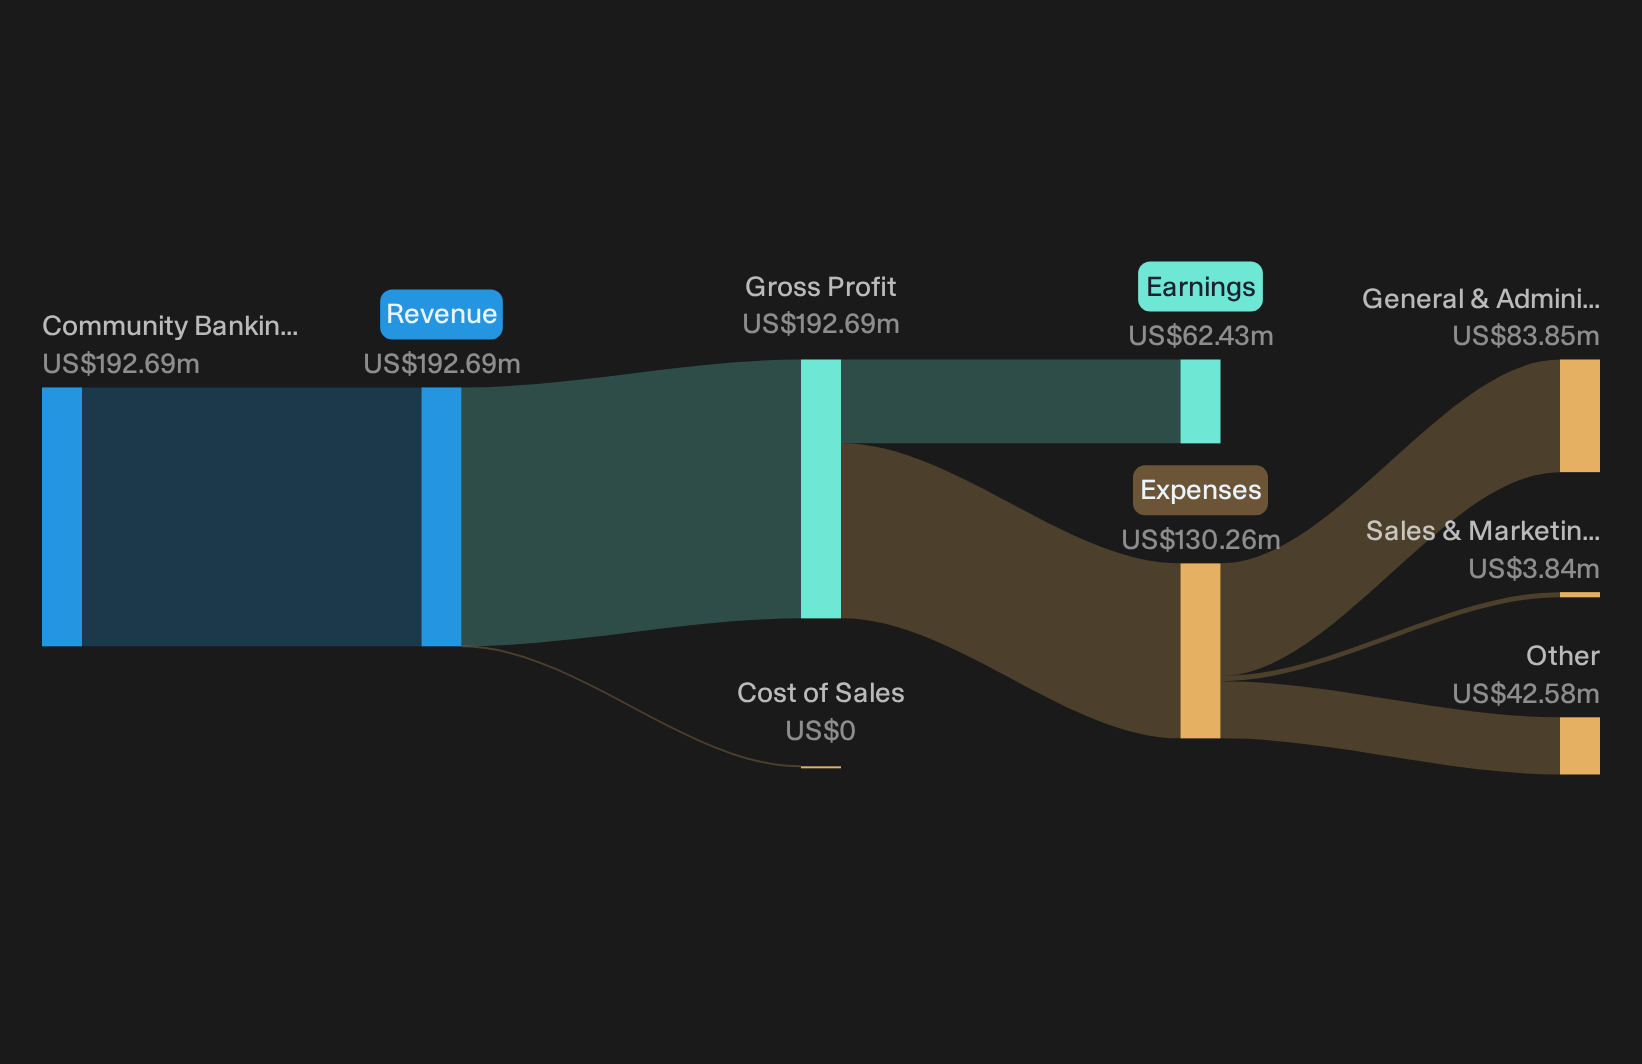
First Community Bankshares results backing cautious optimism
For anyone leaning optimistic on First Community Bankshares, the latest quarter gives some support. Revenue and net income are both higher than a year ago, and basic EPS moved from US$0.67 to US$0.82. That sits alongside a steady 4.46% net interest margin and a lower level of non performing loans at about US$15.8 million. The share price slipped 1.5% after the release, and the operating story reads as a reasonably stable regional lender that is growing earnings while keeping credit issues in check.
Bearish worries tested by softer earnings mood
On the cautious side, the market reaction and recent share price drift matter. The stock is down about 6% over 7 days, 2% over 30 days, and 3% over 90 days, and it eased 1.5% on these results. That suggests investors are not rushing to reward the higher revenue and profit. Concerns around regional concentration and acquisition execution after the planned Main Street Financial Services deal can still weigh, even though current credit quality and margin performance look relatively firm.
After a softer earnings mood and concerns about the Main Street Financial Services acquisition, it is fair to ask if these are isolated issues or hints of deeper structural pressure on First Community Bankshares. Review the independent risk analysis for First Community Bankshares which shows 1 important warning signHunt For Balance Sheet Clues
First Community Bankshares just showed how sentiment can diverge from reported performance in a hurry. The real opportunity is finding stocks that could be low debt before the market reflects that.
- Company 1 - 36% below our estimate - turns shorter brownfield tieback timelines into higher margin subsea equipment orders and long duration services contracts.
- Company 2 - 32% below our estimate - targets data centre customers that standardize on its GPUs and software stack as AI workloads expand power use.
- Company 3 - 23% below our estimate - embeds paid AI assistants into existing productivity, developer and business software subscriptions supported by its cloud infrastructure.
That is three of the list. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com