
Learn Why The Bull Case For Accor (ENXTPA:AC) Could Change Following Verdi Hotels Deal
- Accor and The Corinthia Group have agreed that several Verdi Hotels in Malta, Portugal, Tunisia, Hungary and the Czech Republic will join Accor's Handwritten Collection under a franchise model, giving these properties access to Accor's distribution, marketing and loyalty systems.
- The move expands Accor's fee-based portfolio in multiple European and Mediterranean markets, adding more third party franchised rooms that can support its focus on higher margin management and franchise operations.
- We will now look at how Accor's investment narrative could be influenced by folding Verdi Hotels into its Handwritten Collection franchise platform.
Scan how Accor's franchise-focused shift compares with other hotel and travel operators by reviewing the hand picked 194 high quality undervalued stocks that combine resilient cash flows with stronger balance sheets.
Accor Investment Narrative Recap
To own Accor, you need to believe its asset light push in management and franchise fees can turn a relatively low 4.1% net margin into stronger, more consistent cash generation despite uneven regions like the Middle East and China. The Verdi Hotels deal fits that story but looks small beside the wider pipeline and loyalty ambitions.
The key near term swing factor remains whether management and franchise EBITDA momentum lines up with its 2023 to 2027 plan. The biggest risk is that weaker RevPAR in the Middle East and ongoing pressure in China keep fee growth subdued, leaving earnings progress and any valuation re rating below what some investors expect.
The Verdi Hotels agreement ties directly into Accor's broader shift toward management and franchise revenue, where new hotels are guided to earn roughly twice the fee per room of churned ones and net unit growth is guided at about 3.5% for 2026. Folding these franchised rooms into the Handwritten Collection leans into that higher fee mix without adding balance sheet strain.
That approach matters when profit margins sit at 4.1%, down from 10.3% last year, and when the group already carries a high level of debt and a dividend that is not well covered by earnings. Execution on asset light growth, including transactions such as the Essendi stake sale and partnerships like Verdi, is central to supporting margins, reducing risk in the capital structure and giving the ALL loyalty base more destinations to feed future fee income.
What The Verdi Deal Means Against Accor's 2029 Targets
Accor's Verdi Hotels move only really makes sense when you line it up against what analysts already expect from the group by 2029. The broader story in the consensus numbers is simple. More fee based rooms, a lighter balance sheet and a fatter margin profile are all already baked into the forecasts.
On the top line, analysts are working off a 6.6% annual revenue growth assumption over the next three years and a view that profit margins can move from 4.1% today to 10.5% in that window. By about 2029, those inputs roll up into forecast revenues of €6.9b and earnings of €723.2m, compared with earnings today of €230.0m. That is a little more than a tripling of the profit pool on current estimates, even before you factor in the small lift from Verdi branded franchises plugging into Accor's loyalty engine and distribution rails.
The valuation side of the consensus then leans on those future earnings to justify current pricing. At a current P/E of 45.0x on today's earnings, the analyst framework assumes the multiple would ease to 23.9x on 2029 forecast earnings, which is slightly below the quoted 24.5x for the wider GB Hospitality industry. For that to hold together, Accor needs to deliver the planned margin uplift and revenue expansion while still convincing the market that earnings tied to more cyclical regions such as the Middle East and China are not structurally impaired.
Verdi's inclusion under the Handwritten Collection umbrella contributes to this by adding more third party franchised rooms that pay ongoing fees without pulling extra weight onto the balance sheet. Those extra contracts align with the margin step up that analysts are assuming over the next few years and they support the case that higher fee management and franchise income can fill the gap between the current 4.1% net margin and the 10.5% level pencilled into the models. For readers, the key question is not whether Verdi alone can move the needle, but whether it reflects the kind of repeatable, franchise heavy growth that Accor is already priced to deliver.
Accor's narrative projects €6.9b revenue and €723.2m earnings by 2029, based on analyst estimates, which implies 6.6% yearly revenue growth and an increase in earnings of about €493m from €230.0m today.
Uncover why Accor's fair value indicates an 18% potential upside to its current price that could narrow quickly.
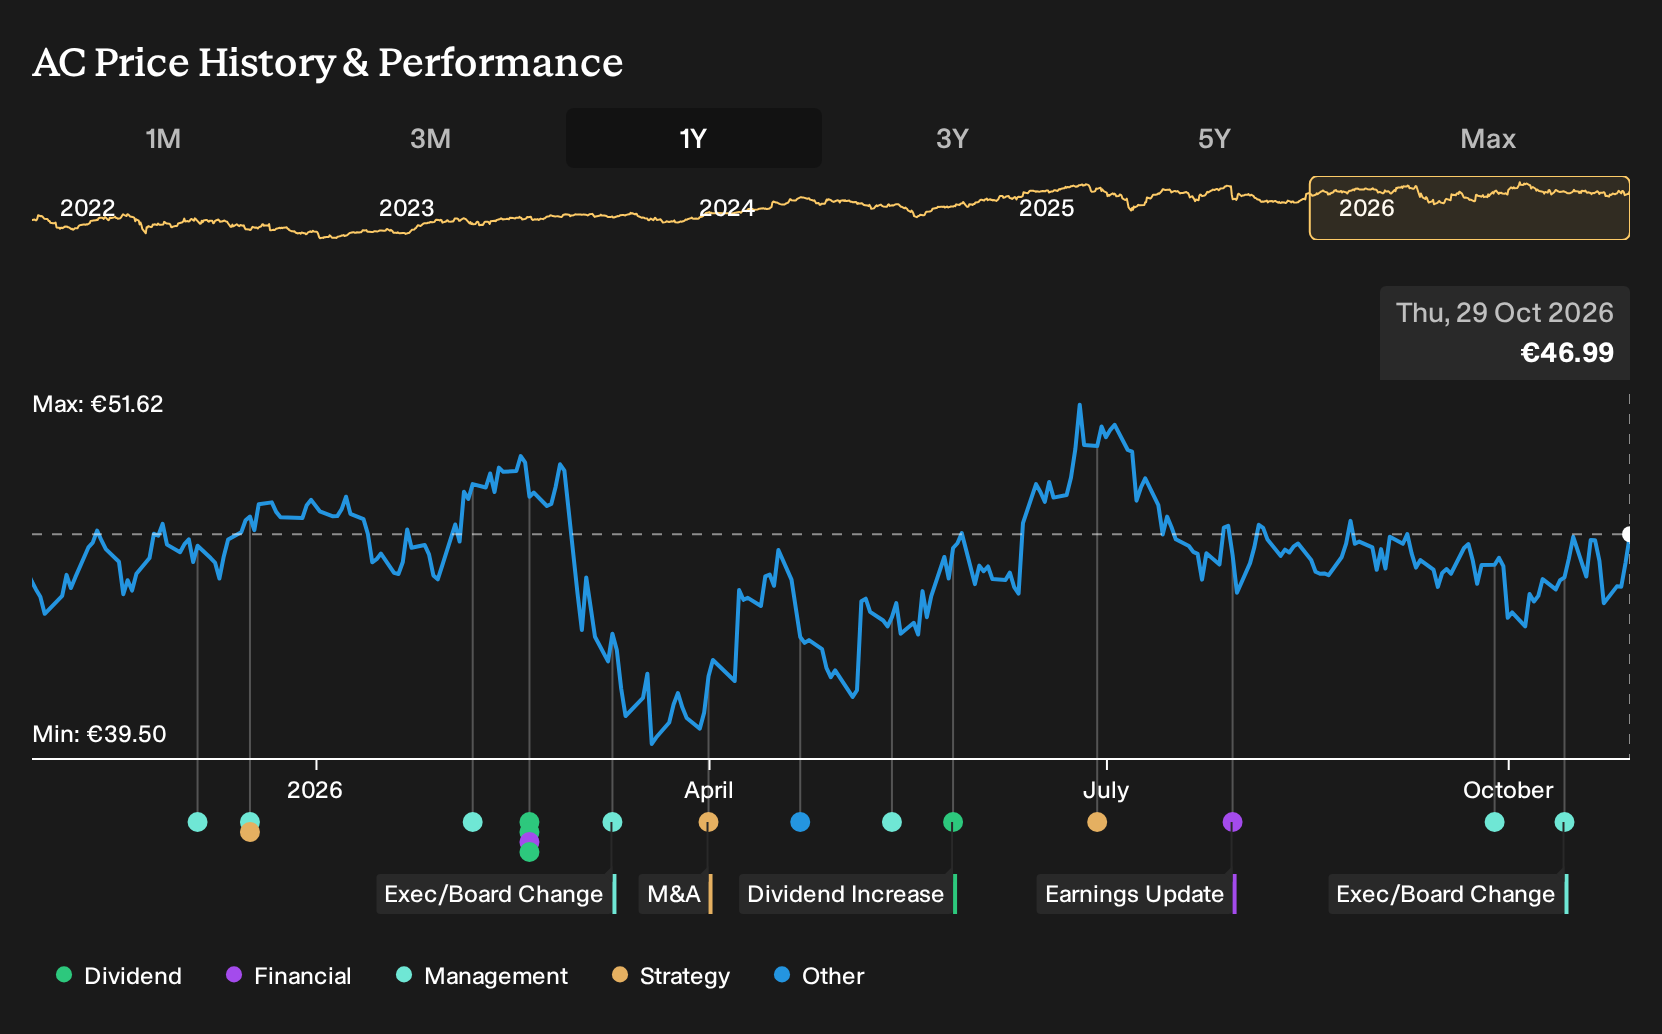
Exploring Other Perspectives
Some of the most optimistic analysts already pencilled in €7.1b of revenue and €863.5m of earnings by 2029 for Accor before this Verdi Hotels franchise move. They leaned heavily on faster net unit growth as a catalyst. If you see that as ambitious, this new deal might either validate or soften that view once forecasts update.
Explore 2 other Accor fair value estimates, including one that suggests as much as 70% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Accor research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Accor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Accor?
If the Accor story has sharpened your thinking about margins, balance sheets and fee based models, it can be useful to compare it with other businesses that match different risk and income profiles. The Simply Wall St Screener helps you quickly sort through plenty of alternatives so you can pressure test your thesis rather than just watching a single ticker.
- For investors who care most about stability and capital preservation, start with companies that score strongly on resilience by checking the 227 resilient stocks with low risk scores.
- If balance sheet strength is your first filter and you want businesses with room to invest without stretching their finances, consider the list of solid balance sheet and fundamentals (206 results) as a way to narrow the field.
- Income focused readers who prioritise cash returns over headline growth can scan for higher yielding opportunities by reviewing the 228 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com