
Hamilton Insurance Group (NYSE:HG) delivers impressive Q3 2026

Specialty insurance company Hamilton Insurance Group (NYSE:HG) announced better-than-expected revenue in Q3 2026, with revenue up 24% year on year to $828 million. Its non-GAAP profit of $1.78 per share was 96.5% above analysts’ consensus estimates.
For more on Hamilton Insurance Group, read our full research report, available free.
Hamilton Insurance Group (HG) Q3 2026 highlights:
- Net premiums earned $591.3 million (13.1% year-on-year growth)
- Revenue $828 million vs S&P analysts’ consensus estimates of $688.5 million (24% year-on-year growth, 20.3% beat)
- Combined ratio 97.3% vs analysts’ consensus estimates of 97.6% (30 basis point beat)
- Adjusted EPS $1.78 vs S&P analysts’ consensus estimates of $0.91 (96.5% beat)
- Book value per share $29.80 (10.1% year-on-year growth)
- Market capitalization $3.42 billion
Revenue growth
Insurers earn revenue three ways. The core insurance business itself, often called underwriting and represented in the income statement as premiums earned, is one way. Investment income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities is the second way. Fees from various sources such as policy administration, annuities or other value-added services are the third. Hamilton Insurance Group’s revenue grew at a strong 26% compounded annual growth rate over the last four years. Its growth beat the average insurance company and shows its offerings resonate with customers.
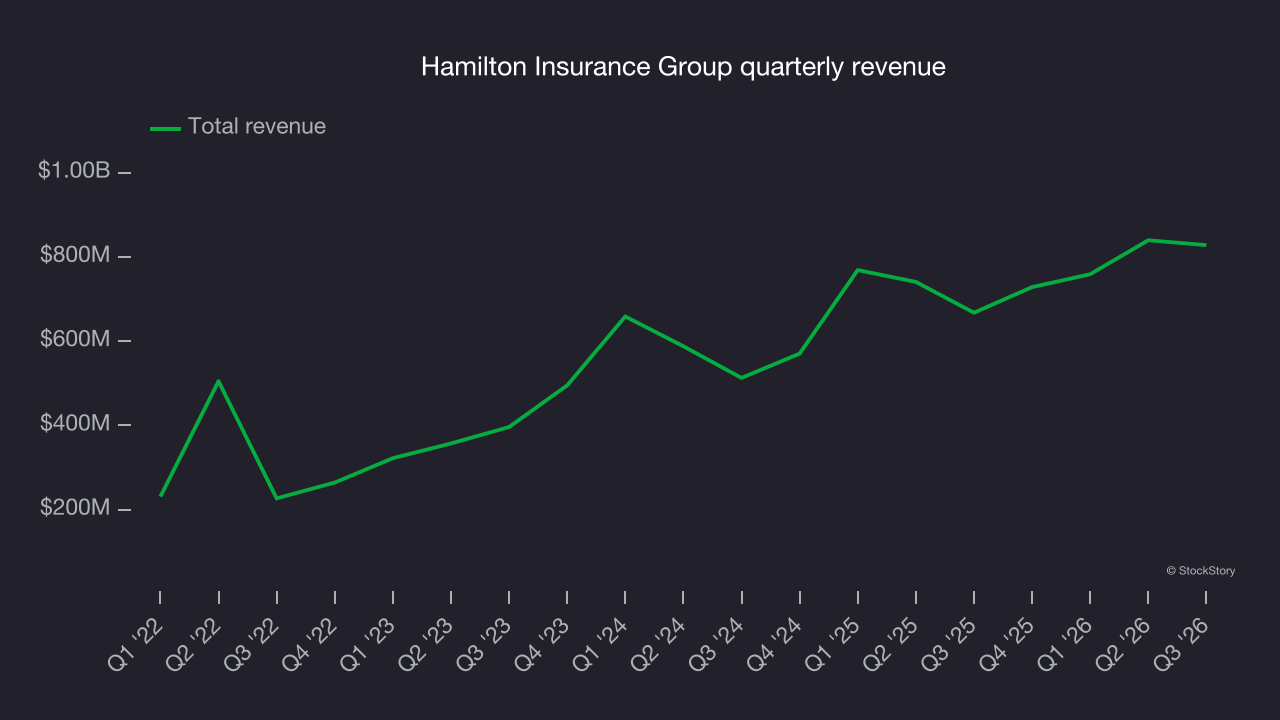
Long-term growth matters the most, but within financials, a longer historical view may miss recent interest rate changes, market returns and industry trends. Hamilton Insurance Group’s annualized revenue growth of 18.3% over the last two years is below its four-year trend, but the results still suggest healthy demand. 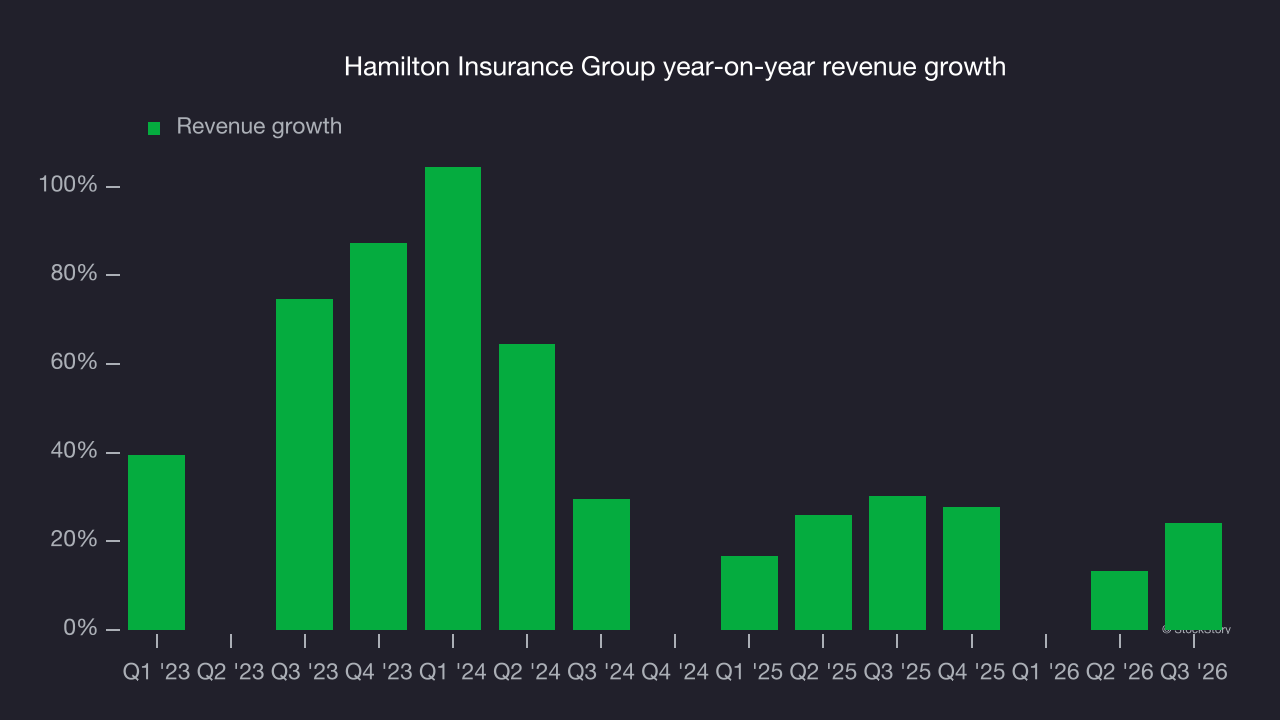 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Hamilton Insurance Group reported year-on-year revenue growth of 24%, and its $828 million of revenue topped Wall Street’s consensus estimates by 20.3%.
Net premiums earned made up 77% of the company’s total revenue during the last five years, meaning insurance operations are Hamilton Insurance Group’s largest source of revenue.
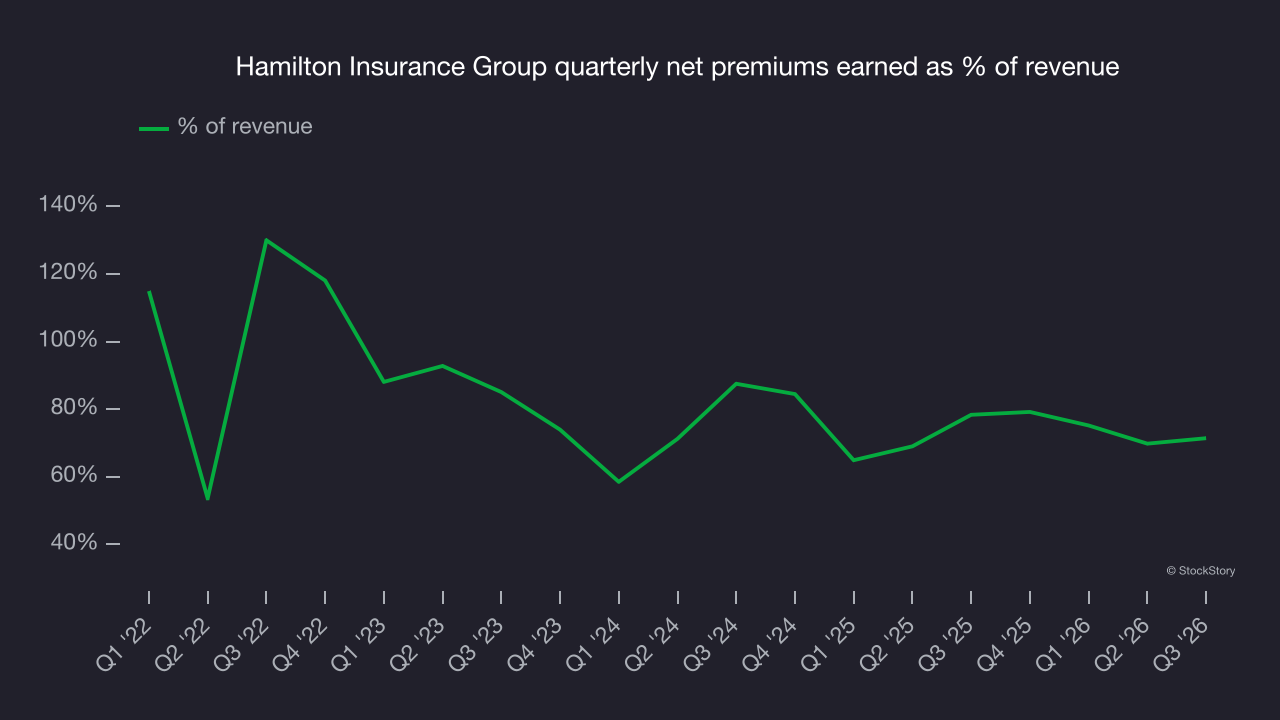
Net premiums earned command greater market attention due to their reliability and consistency, whereas investment and fee income are often seen as more volatile revenue streams that fluctuate with market conditions.
Book value per share (BVPS)
Insurance companies are balance sheet businesses, collecting premiums upfront and paying out claims over time. The float – premiums collected but not yet paid out – is invested, creating an asset base supported by a liability structure. Book value captures this dynamic by measuring:
- Assets (investment portfolio, cash, reinsurance recoverables) - liabilities (claim reserves, debt, future policy benefits)
BVPS is essentially the residual value for shareholders.
BVPS is therefore an important metric to track for insurers and sheds light on business quality because it reflects long-term capital growth and is harder to manipulate than more commonly used metrics like EPS.
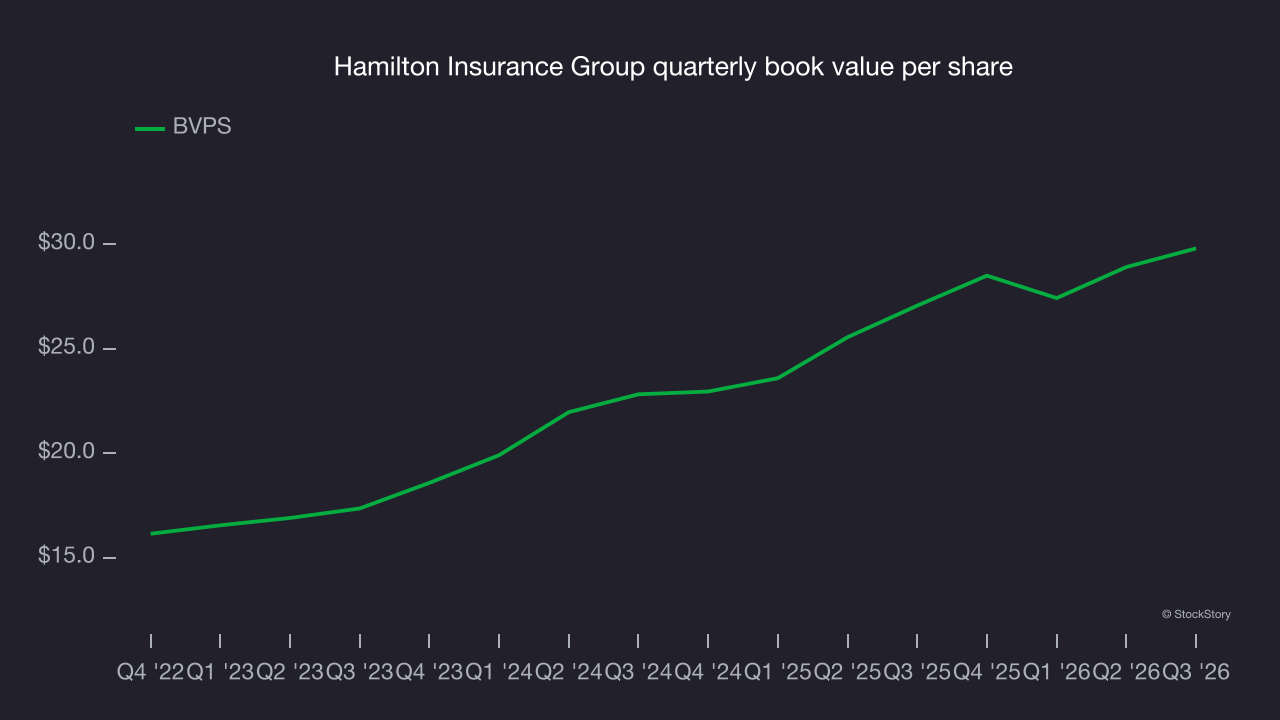
Hamilton Insurance Group’s BVPS grew at a decent annual rate of 14.3% over the last two years.
Key takeaways from Hamilton Insurance Group’s Q3 results
Hamilton Insurance Group delivered a solid quarter, with revenue topping Wall Street’s consensus estimates by a wide margin and EPS also beating analysts’ consensus estimates. Shares edged higher 1.7% to $35 immediately after the results.
Hamilton Insurance Group had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on those factors, read our full research report here (it’s free).