
Veralto’s (NYSE:VLTO) Q3 2026 sales beat estimates
Water analytics and treatment company Veralto (NYSE:VLTO) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 7.5% year on year to $1.51 billion. Its non-GAAP profit of $1.18 per share was 8.3% above analysts’ consensus estimates.
For more on Veralto, read our free full research report.
Veralto (VLTO) Q3 2026 highlights:
- Revenue $1.51 billion vs S&P analysts’ consensus estimates of $1.50 billion (7.5% year-on-year growth, 0.8% beat)
- Adjusted EPS $1.18 vs S&P analysts’ consensus estimates of $1.09 (8.3% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $4.51 at the midpoint, a 2.6% increase
- Operating margin 19.7%, down from 23.2% in the same quarter last year
- Free cash flow margin 20.1%, up from 18.4% in the same quarter last year
- Market capitalization $25.06 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Veralto grew its revenue at a tepid 4.9% compounded annual growth rate, falling short of the industrials sector benchmark.
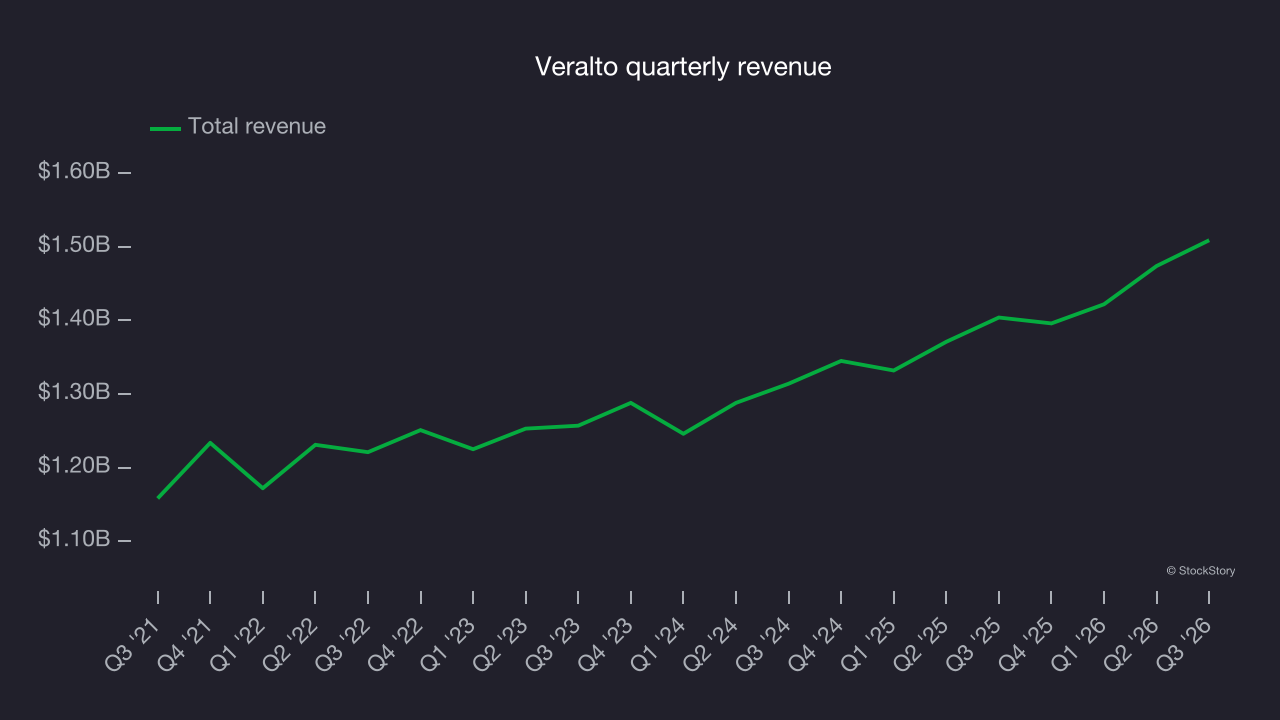
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Veralto’s annualized revenue growth of 6.3% over the last two years is above its five-year trend, a positive sign. 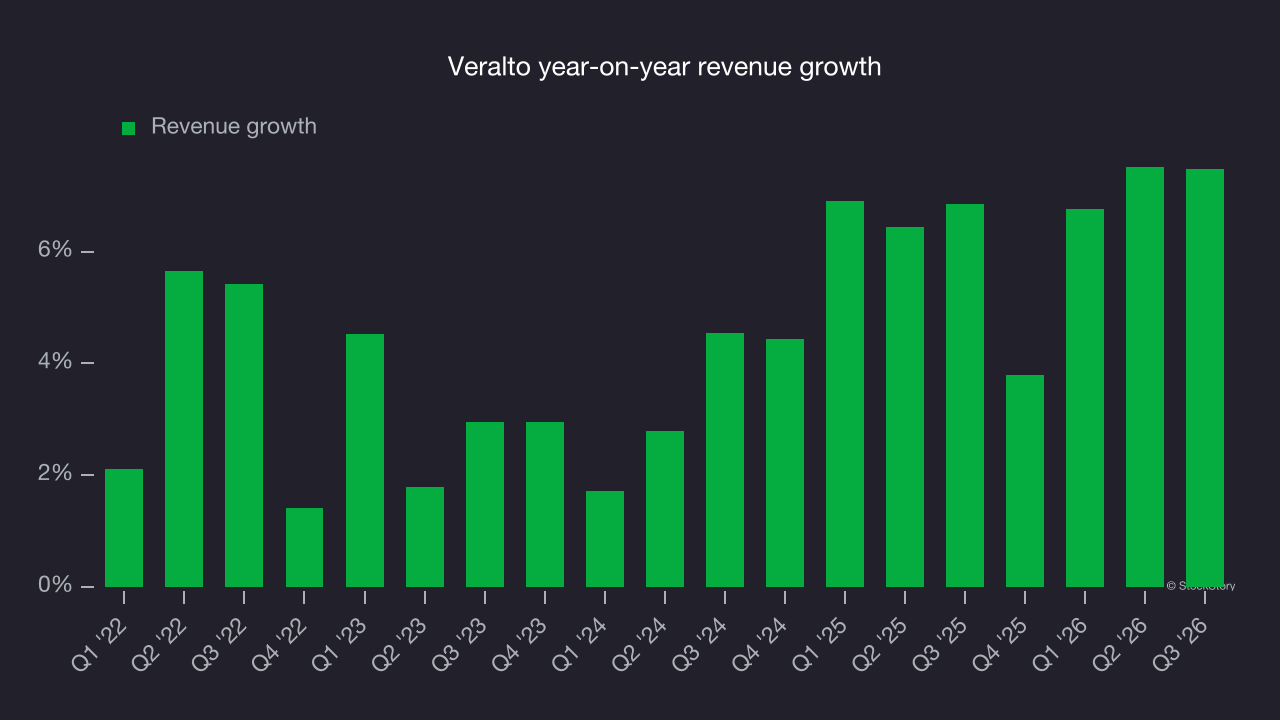
This quarter, Veralto reported year-on-year revenue growth of 7.5%, and its $1.51 billion of revenue exceeded Wall Street’s consensus estimates by 0.8%.
Looking ahead, sell-side analysts expect revenue to grow 6.1% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not lead to better top-line performance yet.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses – everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Veralto’s operating margin has remained largely unchanged over the last 12 months, averaging 22.6% over the last five years. This profitability was strong for an industrials business thanks to its efficient cost structure and economies of scale. That result is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Veralto’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
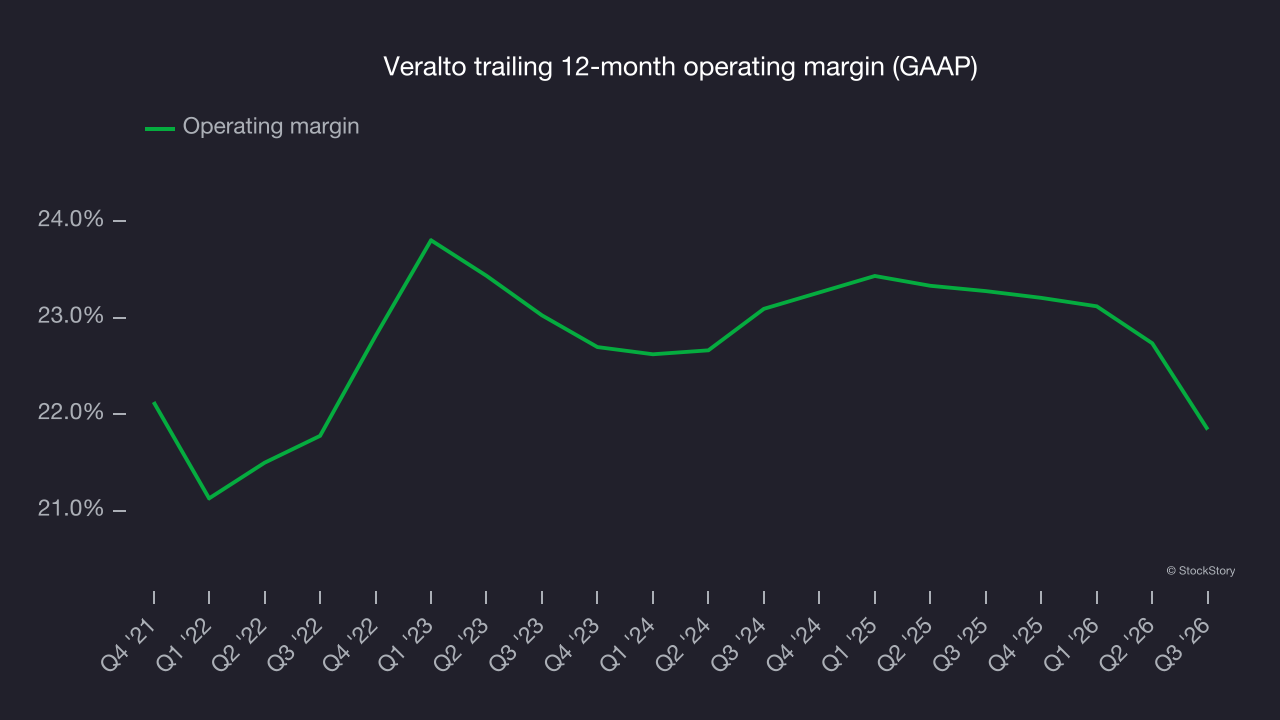
In Q3, Veralto generated an operating margin of 19.7%, down 3.5 percentage points year on year. Its operating margin decreased more than its gross margin, suggesting it was less efficient as expenses such as marketing, R&D and administrative overhead increased.
Free cash flow
Free cash flow matters because companies need cash, not accounting profits, to pay their bills.
Veralto has shown strong cash profitability, putting it in an advantageous position to invest in new products, return capital to investors and consolidate the market during industry downturns. The company’s free cash flow margin was among the best in the industrials sector, averaging 17.7% over the last five years.
Veralto’s margin expanded by 3.1 percentage points during that time. This shows the company is heading in the right direction and became a less capital-intensive business, as its free cash flow profitability rose while its operating profitability was flat.
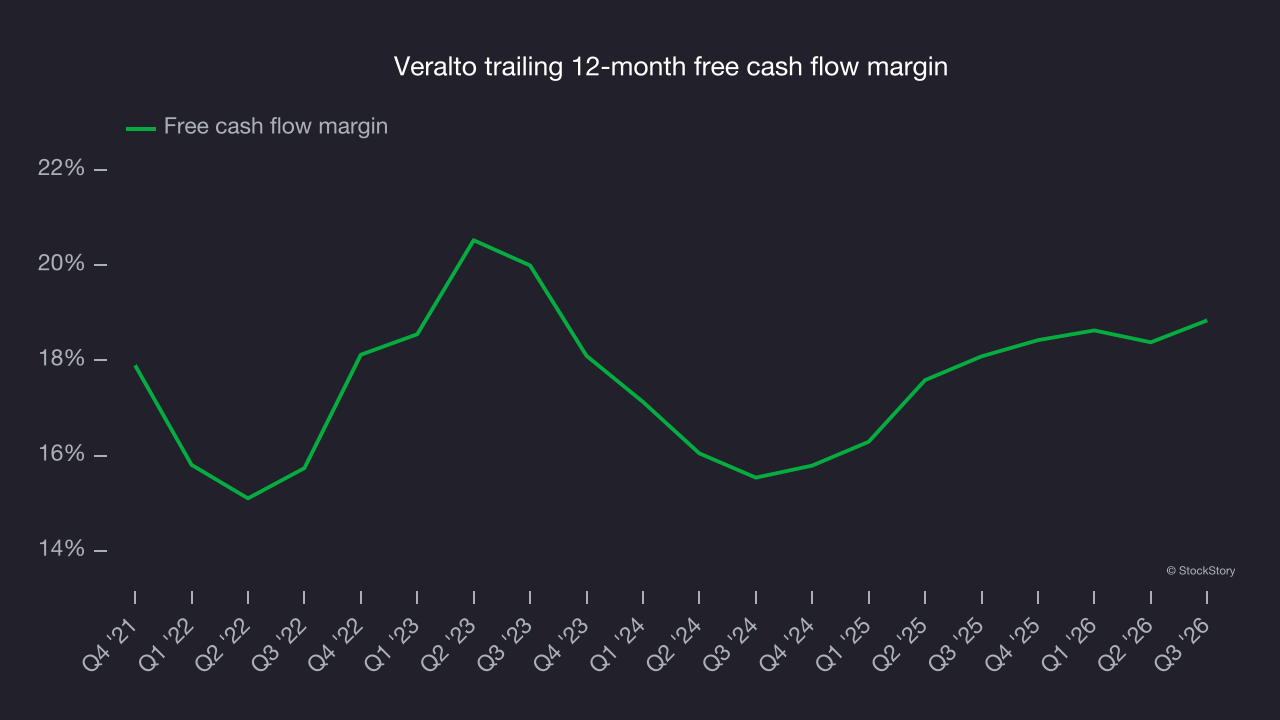
Veralto’s free cash flow totaled $304 million in Q3, equivalent to a 20.1% margin. This was a positive result, as its margin was 1.8 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from Veralto’s Q3 results
Veralto delivered a solid quarter, beating Wall Street’s consensus estimates for EPS and setting full-year EPS guidance above analysts’ consensus expectations. Those were key positives in the report. Shares edged higher 1.2% to $105.24 immediately after the release.
Veralto may have had a good quarter, but that alone doesn’t determine whether to invest. That decision should take valuation, business quality and the latest earnings into account. For more on those factors, read our full research report here (it’s free).