
Takara Holdings (TSE:2531) Could Be Overvalued As Raised Guidance Lifts The Story
Takara Holdings (TSE:2531) raised its earnings guidance for the six months to September 30, 2026, after tighter cost control, price adjustments abroad, tariff refunds, and foreign exchange effects improved expected profitability.
The raised guidance arrives after a strong run in Takara Holdings’ share price, with a 90 day share price return of 32.16% and a year to date gain of 70.46%. The 1 year total shareholder return of 79.61% suggests momentum has been building rather than fading.
Scan for other companies where tighter cost control and pricing power are already showing up in the numbers by checking our curated list of 71 high quality undiscovered gems alongside Takara Holdings.
Takara Holdings has issued a sharply higher forecast, and its share price has raced ahead. Is this mostly better fundamentals showing through, or has sentiment simply run hotter than the underlying value justifies?
Price-to-Earnings of 47.3x for Takara Holdings: Is it justified?
The market is currently valuing Takara Holdings at a P/E of 47.3x, using the last close of ¥2,761.5 as the reference point, which sits well above the broader Asian beverage sector.
A P/E ratio compares what investors are paying for each unit of earnings. For a diversified group like Takara Holdings, which spans alcohol, seasonings, biotech, and logistics, this measure effectively captures how much the market is willing to pay for its current profit stream.
That 47.3x figure comes against an Asian beverage industry average of 15.9x, so the stock trades at a materially richer level than many peers. Profit trends do not offer an easy explanation either, with earnings declining by 9% per year over the past 5 years and falling 26.3% over the last twelve months, and current net margin of 2.8% lower than last year’s 4.1%. The market is therefore assigning a premium multiple in spite of weaker recent profitability rather than because of it.
Within a closer peer set, Takara Holdings looks cheaper, since the 47.3x P/E is below the peer average of 53.6x. That still represents a substantial premium to the sector as a whole, which suggests the current valuation leaves little room for further disappointment in earnings quality, margin trends, or execution.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 47.3x (OVERVALUED)
Still, the narrative around Takara Holdings could be tested if cost savings fade, or if higher prices start to pressure demand in key categories.
Find out about the key risks to this Takara Holdings narrative.
Another View on Takara Holdings Using Cash Flows
The P/E ratio points one way for Takara Holdings, while the cash flow model points another. Our DCF model, which estimates the value of future cash flows, suggests a value of ¥764.3 per share against a market price of ¥2,761.5. That comparison implies Takara Holdings could be overvalued. Which signal do you consider more informative?
Look into how the SWS DCF model arrives at its fair value.
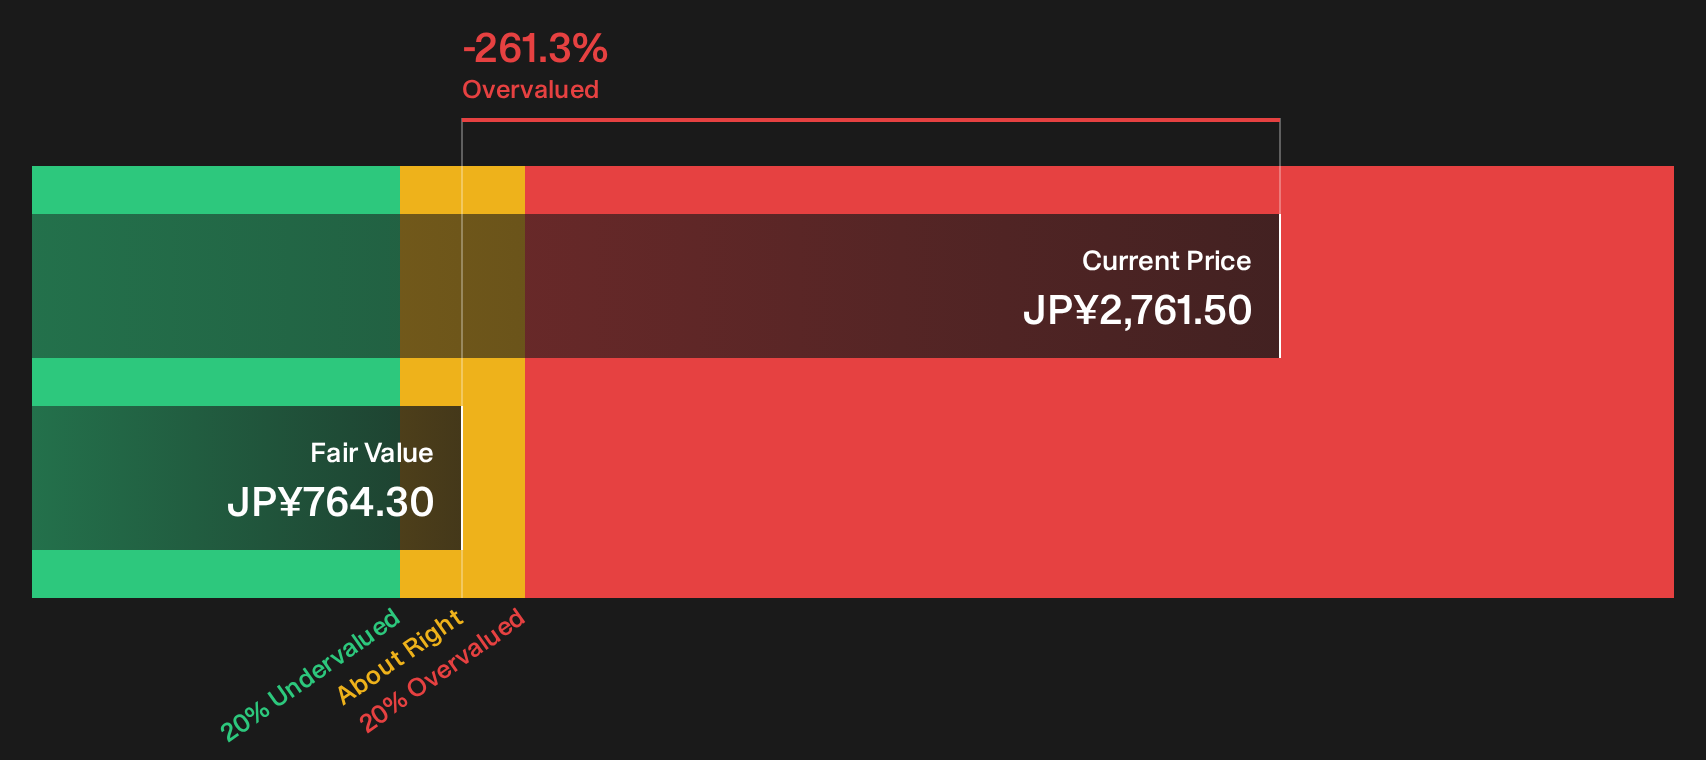
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takara Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Confident about the story so far, or starting to question the price Takara Holdings trades at today? Move quickly, review the full risk rundown, and weigh those 3 important warning signs.
Looking for more ideas beyond Takara Holdings?
If Takara Holdings has you rethinking what you own, then casting a wider net with a few focused stock screens could help you move from reacting to taking a more proactive approach.
- Target resilience first by running your eye over a 26 resilient stocks with low risk scores that filters for businesses with more stable profiles when markets feel unpredictable.
- Hunt for value gaps by checking a 15 high quality undervalued stocks that highlights companies where solid fundamentals and current pricing appear out of sync.
- Prioritise financial strength by scanning a list of solid balance sheet and fundamentals (23 results) that spotlights firms with sturdier balance sheets and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com