
What Budweiser APAC Doubters Saw Before The Drop
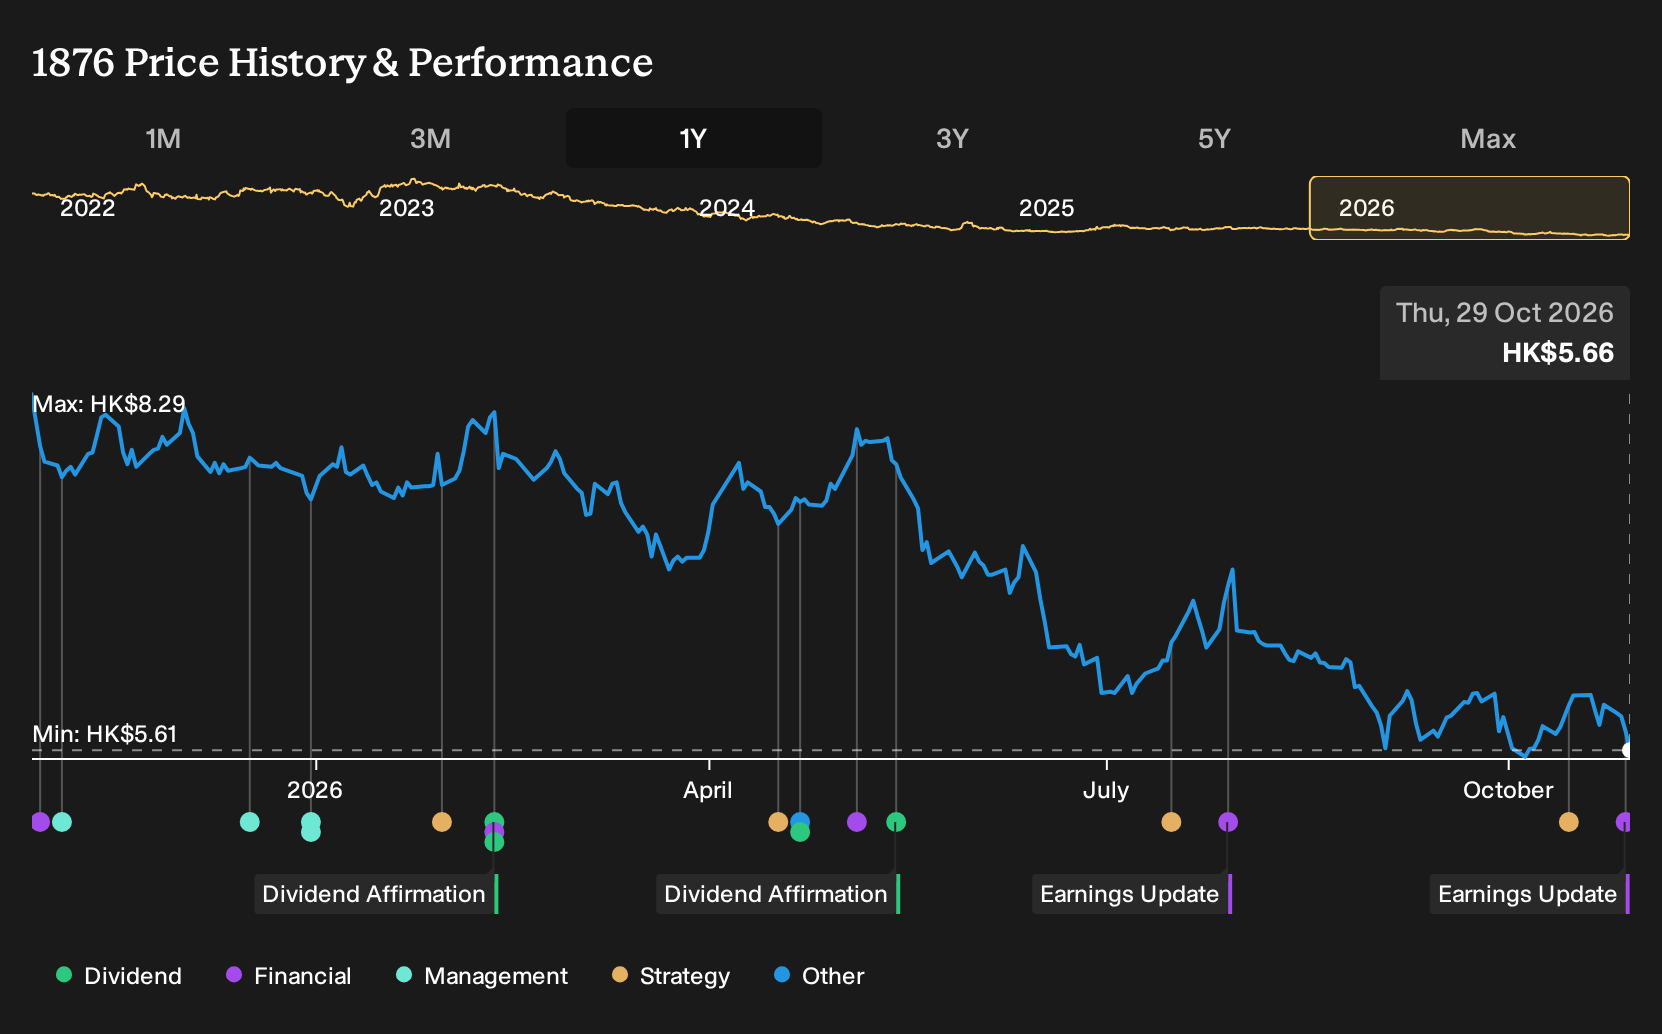
Budweiser Brewing Company APAC spent the past year juggling modest volume growth with falling margins as it poured more cash into China to push its in-home channels and megabrands. For Budweiser Brewing Company APAC shareholders, the loss over the past year was 24.8%, including dividends. If you had committed fresh capital in late October 2025, that outcome now raises a blunt question: Were the early bullish and bearish arguments about this brewer fairly framed against what actually played out?
The easy part of this move is behind Budweiser Brewing Company APAC. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
The Two Futures Investors Saw For Budweiser Brewing Company APAC
The shares cost HK$8.4 at the start of the period, and anyone looking at Budweiser Brewing Company APAC then had to choose between two very different stories about what came next.
The bullish view argued that premium brands and digital commerce across urbanizing Asian markets would reshape the business. On that logic, a Fair Value of HK$15, which is simply the price implied if those expectations played out, rested on assumptions like revenue growing 8.9% a year and profit margins rising from 9.9% to 16.2% by 2028.
The bearish camp saw more limits than upside. It focused on rising health consciousness and regulation across APAC and treated a Fair Value of HK$7.9 as more realistic, anchored in assumptions such as only 1.6% annual revenue growth and margins reaching 13.1% as beer demand and pricing power stayed under pressure.
What The Results Changed For Budweiser Brewing Company APAC
Budweiser Brewing Company APAC eventually reported Q2 2026 net income of US$247 million on US$1,678 million of revenue, with net margin at 14.7% compared with 10.4% a year earlier. That supported the optimistic margin narrative more than the cautious one, although modest volume gains and earlier pressure from China investment meant the evidence still pointed in both directions.
The key assumption that really mattered here was margin expansion rather than just sales growth. For a different brewer, you would track net income and net margin together against any premiumization or channel-mix story to see if the promised profitability actually shows up.
What You Are Paying For In Budweiser Brewing Company APAC Today
With Budweiser Brewing Company APAC now at HK$5.66, the selected Narrative’s Fair Value sits above the current price and leans on a recovery story rather than a simple re-rating argument.
The pitch centers on premium brands, in-home and O2O channels, and stronger contributions from India and South Korea. A buyer today would need to believe China can shift from a drag to a contributor through better mix, pricing, and returns on recent investment.
"The main requirement is that Budweiser Brewing Company APAC turns China from a drag into a contributor by stabilising volumes, lifting revenue per hectoliter, and earning an adequate return on higher brand and route to market investment, despite weaker on premise demand and higher input costs."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another Way To Play Premium Drinks
Looking at Budweiser Brewing Company APAC, you are really weighing premium beer, channels, and mix. One step away sits a business built around spirits and stout.
That operator chases a similar shift toward higher value drinks. It adds something else, a full price ladder using smaller packs and ready to drink formats.
The idea is simple. Give drinkers more ways to trade up or stay in the franchise without walking away on price.
It is tying that to a big simplification effort across its own operations. If the plan works, the role of cost cuts and format choice in alcohol could look different from here.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com