
Will Oral Pellet Approval Change BioCryst Pharmaceuticals (BCRX) Narrative
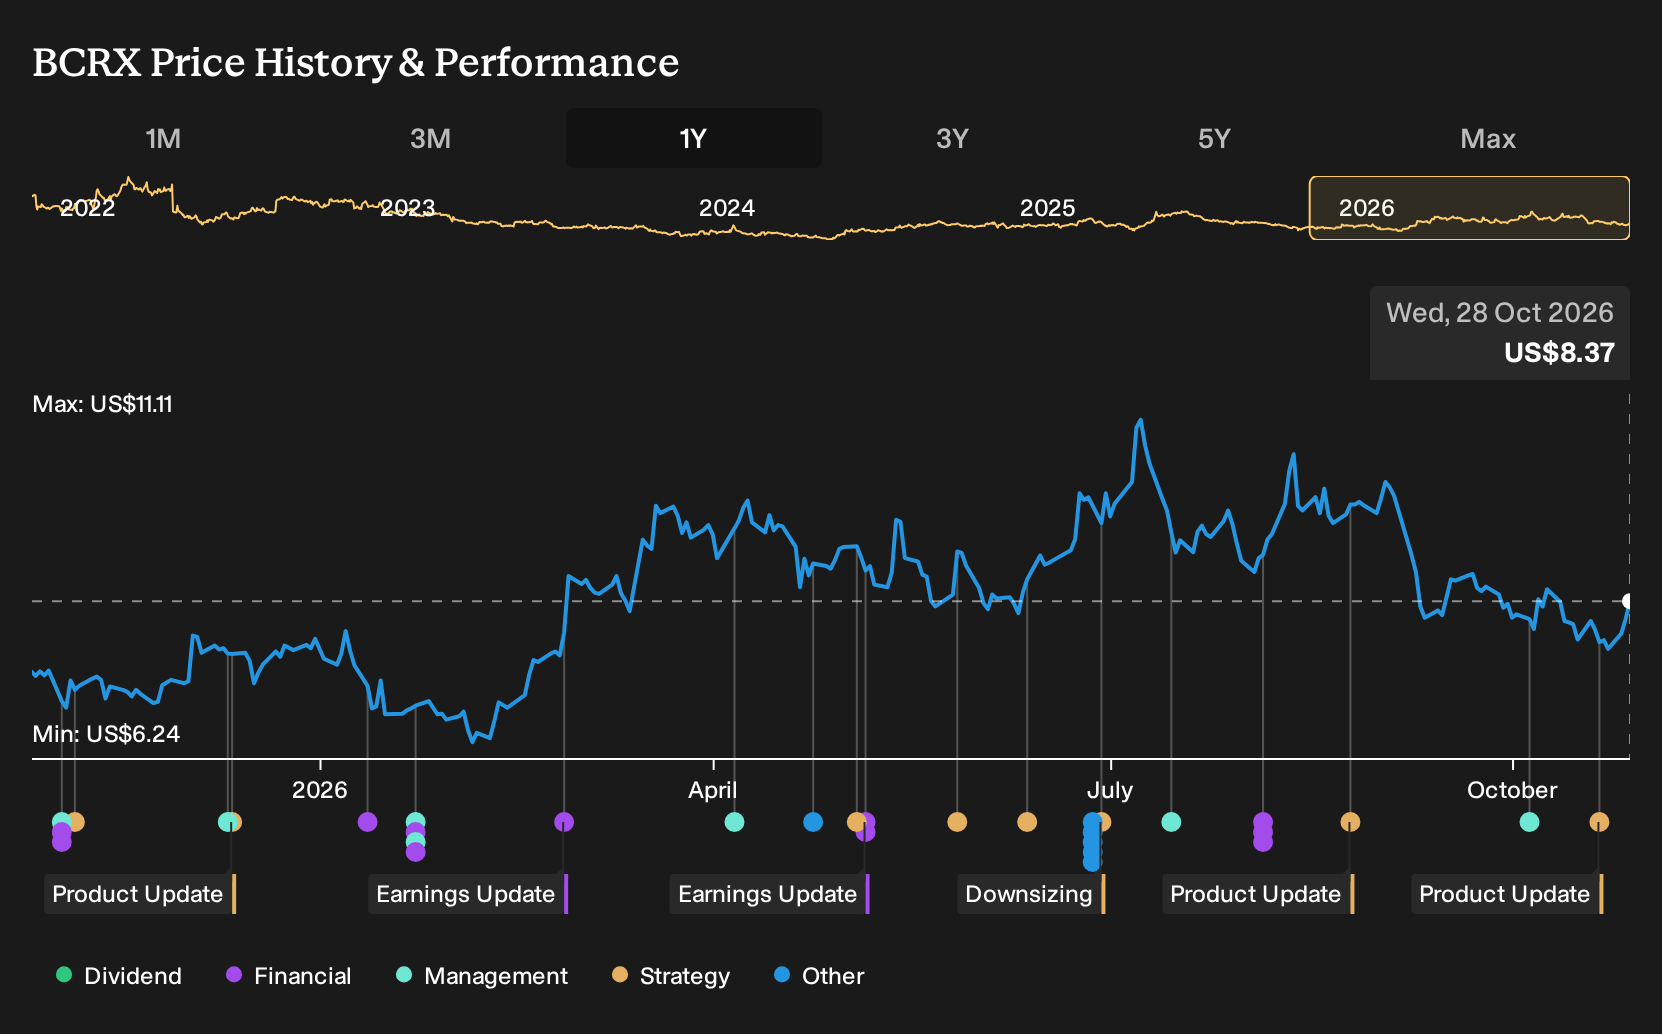
- BioCryst Pharmaceuticals reported two October 2026 milestones as the FDA cleared a once daily ORLADEYO oral pellet for adults and adolescents and the firm prepared to showcase four hereditary angioedema data sets at the American College of Allergy, Asthma & Immunology meeting.
- The new pellet formulation directly targets patients who struggle with capsules, while fresh ORLADEYO and navenibart data may influence how clinicians view long term prophylaxis choices and real world treatment patterns.
- The focus now turns to how BioCryst Pharmaceuticals' investment narrative could shift as ORLADEYO adds a pellet option for patients who have difficulty swallowing capsules.
Scan beyond BioCryst Pharmaceuticals and explore other rare disease players that could be approaching their own inflection points with our hand picked 36 healthcare AI stocks
BioCryst Pharmaceuticals Investment Narrative Recap
To own BioCryst Pharmaceuticals, you effectively need to believe ORLADEYO can support the business while the broader rare disease pipeline matures. The short term story still revolves around keeping hereditary angioedema patients on therapy and attracting new ones in a crowded category where alternatives already exist and more competitors are emerging.
The main near term swing factor is how well BioCryst manages this concentration risk on ORLADEYO while operating with negative shareholders’ equity and ongoing losses. The October news looks additive rather than transformational. It refines the commercial pitch and scientific narrative but does not fundamentally change the dependency on one product.
The FDA approval of the once daily ORLADEYO oral pellet for adults and adolescents is the clearest operational link to current catalysts. It gives prescribers an extra administration choice for patients who dislike or struggle with capsules, which may help with adherence and retention in a market where BioCryst is already facing newer options.
For an investor watching execution, the pellet formulation mainly matters as a tool to defend ORLADEYO’s share and keep the prescription base stable while navenibart advances. It does not reduce competition or R&D spend, but it slightly broadens BioCryst Pharmaceuticals’ flexibility in how it serves hereditary angioedema patients in the coming years.
BioCryst Pharmaceuticals’ current analyst storyline points to forecast revenue of US$930.1 million and earnings of US$131.3 million by 2029. That profile assumes revenue growth of 1.6% per year and an earnings swing of about US$589.3 million from an earnings loss of US$458.0 million today.
Uncover how BioCryst Pharmaceuticals' fair value indicates a 154% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the lowest BioCryst Pharmaceuticals forecasts lean hard into competition risk. Those analysts were modeling revenue of US$704.1 million and earnings of US$112.3 million by 2029, well below the bullish views. You can read that as a more cautious story. These new ORLADEYO and navenibart data could eventually shift those expectations.
Explore 3 other BioCryst Pharmaceuticals fair value estimates, including one that suggests it could be worth just $20.55!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your instincts.
- A great starting point for your BioCryst Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioCryst Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioCryst Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond BioCryst Pharmaceuticals?
If the BioCryst Pharmaceuticals story has sharpened your thinking about risk, concentration and upside potential, it can help to compare it with a broader watchlist of opportunities. The Simply Wall St Screener lets you line up different types of stocks side by side so you can see which ones best fit your own risk tolerance and return goals.
- If capital preservation is front of mind, start with companies that screen as relatively resilient by reviewing 32 resilient stocks with low risk scores and see which profiles feel more comfortable than BioCryst Pharmaceuticals.
- For investors who want financial strength to be the anchor of their thesis, focus on businesses with sturdy finances using the list of solid balance sheet and fundamentals (24 results) and compare their balance sheets to what you see at BioCryst.
- If you are hunting for potential mispriced stories that the wider market might not be focused on yet, look through the 19 high quality undiscovered gems and see which ideas you want to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com