
Chugai Pharmaceutical (TSE:4519) Beats Nine Month Forecasts, Is The Recent Rebound Already Priced In?
Chugai Pharmaceutical (TSE:4519) just posted nine month 2026 earnings that topped its own forecasts, with higher sales, revenue, and net income alongside fresh FDA progress on key pipeline drugs.
The latest nine month beat and FDA milestones have arrived after a mixed year for Chugai Pharmaceutical’s shareholders, with the share price down 21.9% year to date despite a 9.1% 1 month share price return and a 5 year total shareholder return of 72.5%. This suggests that long term holders have still seen meaningful value creation even as recent momentum has only started to recover.
Compare how other large healthcare and pharma stocks with solid balance sheets are priced today by viewing Chugai Pharmaceutical alongside our curated list of solid balance sheet and fundamentals (23 results)
Chugai Pharmaceutical now pairs a strong product engine with a share price that has lagged this year. After that recent rebound, is there still much value remaining in the current valuation, or has the gap mostly closed?
Most Popular Narrative: 9% Overvalued
On the most followed view, Chugai Pharmaceutical screens as modestly overvalued, with a fair value of ¥6,100 against a last close of ¥6,653, even after the recent earnings beat and share price rebound.
While Chugai Pharmaceutical is filing what it describes as a record number of projects in 2026, the company is also discontinuing multiple in-house programs such as tominersen, BRY10, several Tecentriq indications and GYM329 in SMA and FSHD. This raises the risk that headline pipeline breadth masks a thinner pool of late-stage assets that can replace Hemlibra and Actemra once current royalty and export revenue peaks roll off and could weigh on medium term revenue and earnings.
See why 3 investors see Chugai Pharmaceutical as 9% overvalued.
Result: Fair Value of ¥6,100 (OVERVALUED)
Still, if Chugai Pharmaceutical turns its late stage pipeline into approvals and royalty streams remain resilient, this bearish valuation gap could narrow.
Find out about the key risks to this Chugai Pharmaceutical narrative.
Another View: P/E Signals A Richer Price
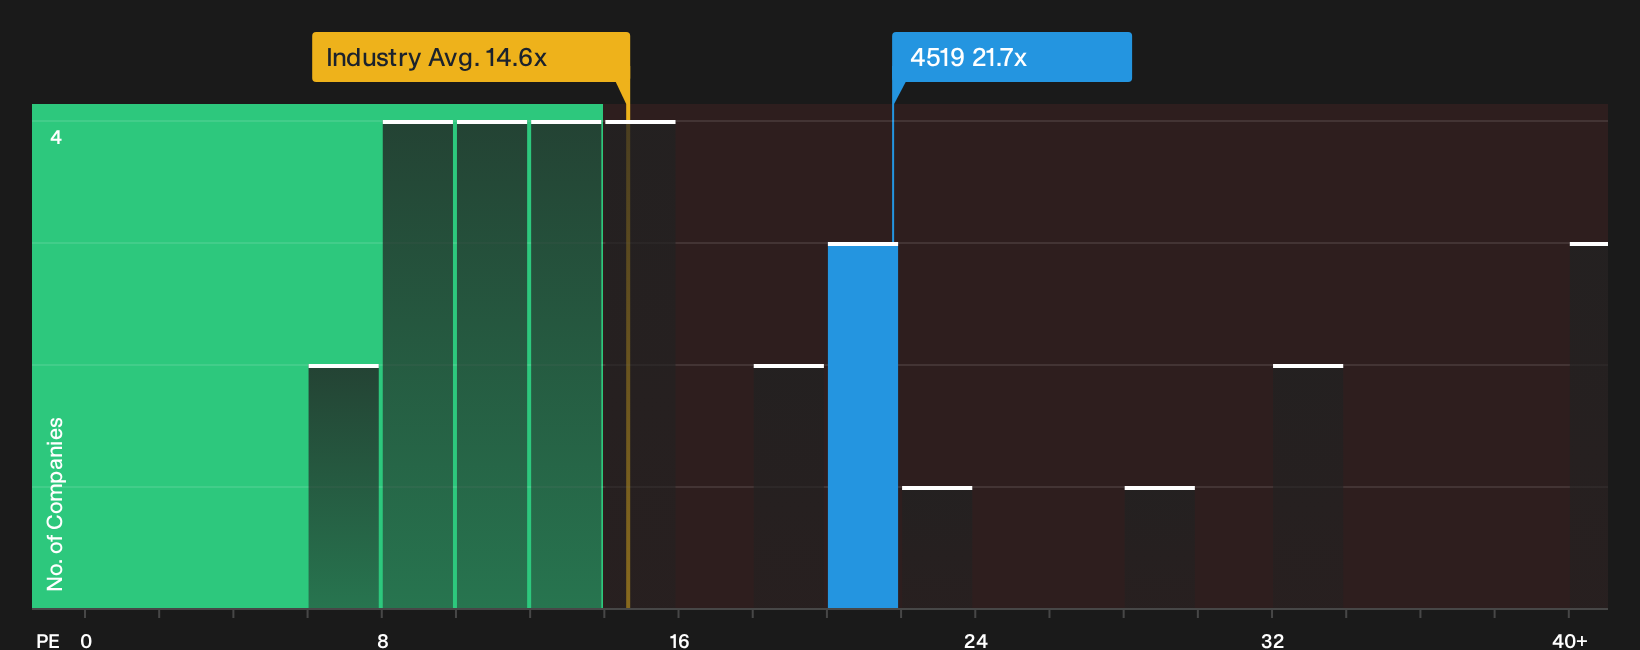
The SWS DCF model points to upside for Chugai Pharmaceutical, yet the P/E ratio tells a different story. The stock trades on 21.7x earnings, which is richer than both the JP Pharmaceuticals industry at 14.6x and the peer average at 14x, even though the fair ratio is 34.1x.
This mix of a discount to fair ratio alongside a clear premium to sector and peers suggests valuation risk in both directions. If sentiment cools or sector multiples compress, how comfortable are you holding a stock that already commands a higher P/E than much of its industry?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Chugai Pharmaceutical so far, right? If you want to move beyond headlines and form your own stance, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chugai Pharmaceutical?
If Chugai Pharmaceutical has sharpened your focus on valuation and quality, use that momentum and widen your watchlist with targeted ideas that match your style.
- Target stronger value opportunities by scanning a curated set of discounted quality businesses through the 15 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies that resemble fortress-style payers in the 30 dividend fortresses.
- Dial down portfolio risk by researching financially resilient businesses with the 26 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com