
Is Wealthsimple Funding Round Altering The Investment Case For IGM Financial (TSX:IGM)?
- IGM Financial took part as an existing shareholder in Wealthsimple's recent $425 million funding round, which was led by Singapore’s GIC at a $13.8 billion valuation, reinforcing its exposure to a large Canadian digital wealth platform.
- The fresh capital for Wealthsimple highlights IGM Financial’s ongoing commitment to technology driven wealth services, which can influence how its affiliate earnings mix and capital allocation story are viewed.
- We will now explore how IGM Financial's participation in Wealthsimple's $425 million raise could influence the broader investment narrative.
Scan a curated short list of wealth and fintech focused companies that are riding similar themes to IGM Financial in our 8 high quality undiscovered gems.
IGM Financial Investment Narrative Recap
To own IGM Financial, you need to believe the business can keep using its balance sheet and cost savings to fund technology, advisor support and affiliate growth in a way that offsets fee pressure. The Wealthsimple funding round and advisor study both sit around that core idea rather than changing it.
In the near term, the key swing factor is whether expense growth near 4% in 2026 produces enough efficiency gains and advisor productivity. The biggest risk remains pressure on advisory and fund fees, especially if ChinaAMC or other affiliates see uneven flows that limit the benefit of IGM Financial’s broader platform.
The advisor perception study around IG Wealth’s support for high net worth households is closely tied to the current catalyst narrative. Management is allocating resources into experiences such as IG Private Wealth Planning, which is aimed at giving advisors better tools to win and retain affluent clients and deepen planning relationships.
The key question for investors is whether those advisor-focused investments, combined with technology and AI spending, can strengthen revenue per advisor enough to offset fee compression. If dealer support for high net worth work lags advisor ambitions, that could slow progress in the segment that IGM Financial highlights as important for fee-based resilience.
How the IGM Financial Consensus Ties Back to Wealthsimple
Analysts are effectively asking you to look at IGM Financial as a slow top line story with a bigger focus on margins and mix. Revenue is expected to stay roughly flat over the next three years, while profit margins are assumed to move from 25.2% today to 30.1% by around 2029. That puts more weight on how efficiently management turns existing assets, affiliates and platforms like Wealthsimple into higher quality earnings.
Current consensus points to earnings of CA$1.2b today rising to CA$1.4b by about 2029, which is an increase of roughly 17%. That uplift is meant to come without a big revenue step up, so cost control, the shift toward higher margin advice and more contribution from affiliates carry a lot of the load. For you as an investor, the Wealthsimple stake sits inside that broader picture as one of several ways IGM Financial might influence its earnings mix rather than as a standalone growth story.
IGM Financial's narrative projects CA$4.5b revenue and CA$1.4b earnings by 2029. This points to relatively flat yearly revenue trends and an earnings increase of about CA$200m from CA$1.2b today.
On valuation, the consensus framework assumes those 2029 earnings of CA$1.4b support a P/E of 17.4x, compared with 15.8x today and a lower multiple for the wider Canadian capital markets peer group at 6.9x. The gap implies that analysts are comfortable with IGM Financial trading at a premium if the margin story plays out and if affiliates such as Wealthsimple and ChinaAMC keep contributing to diversification and fee based income. The share count is also expected to shrink by about 2.26% a year for the next three years, which would lift earnings per share if the profit pool grows as forecast.
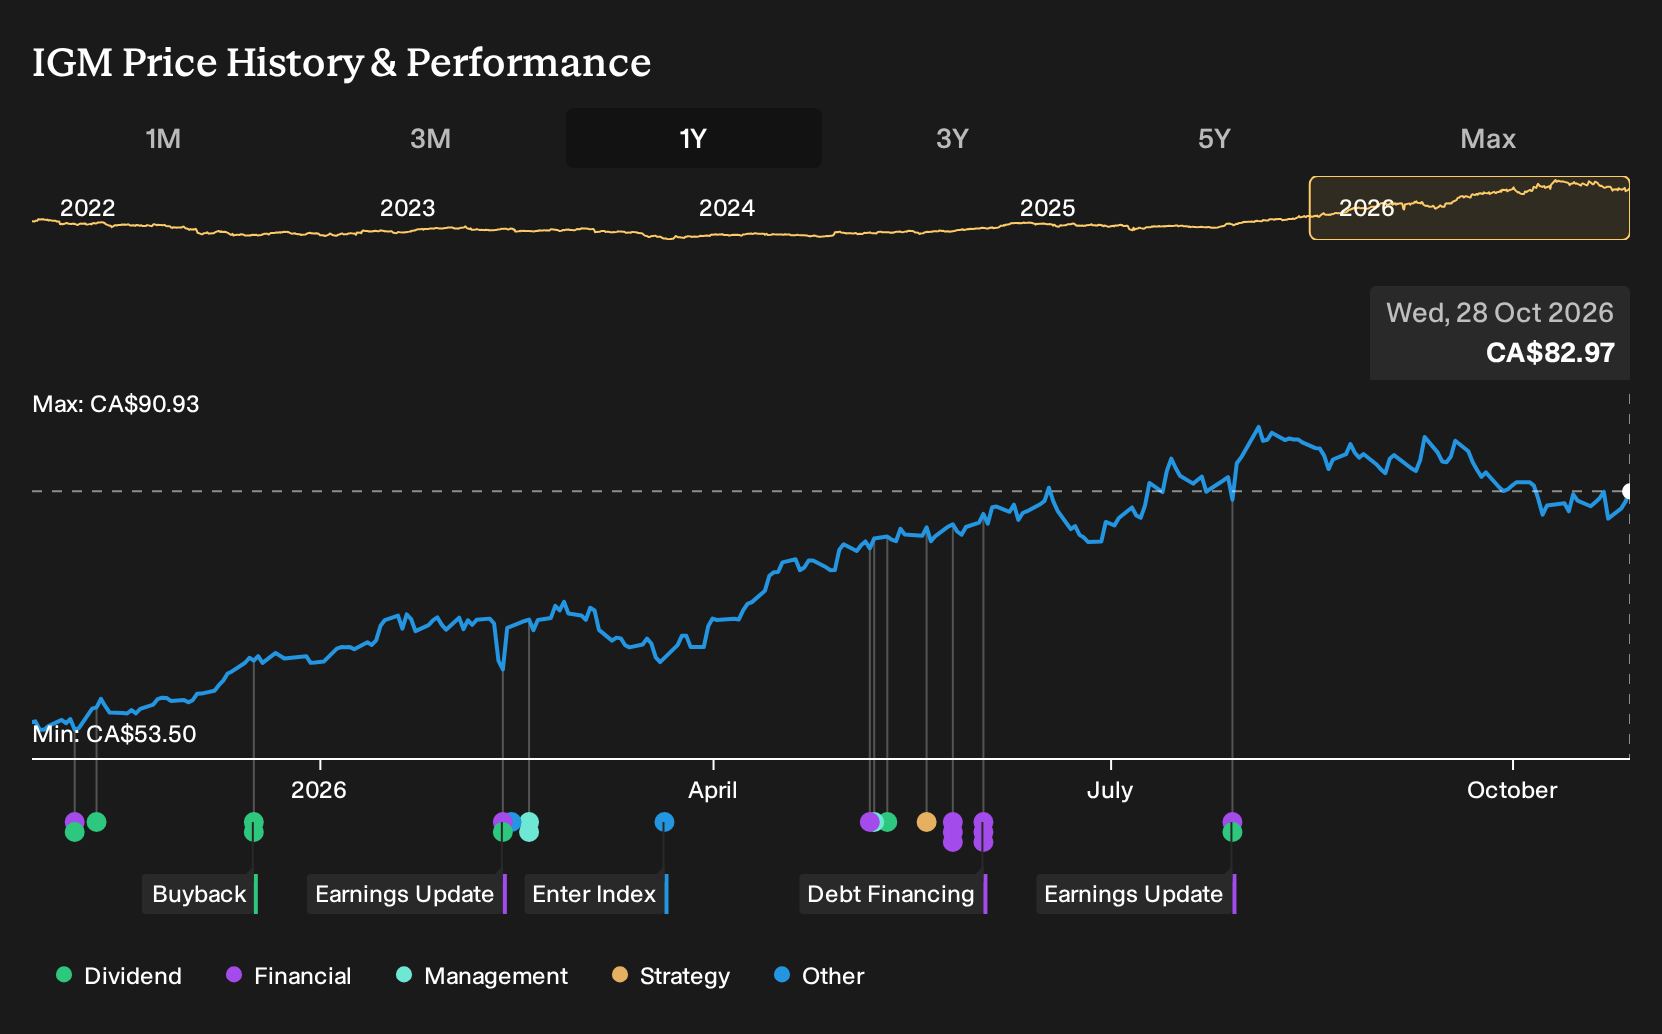
Consensus price targets cluster around CA$89.25, with a range from CA$78.00 to CA$96.00 against a current price of CA$79.59. That spread reflects different views on how much weight to give the margin expansion path, the role of AI and data spending, and the resilience of advisory fees. It also captures differing opinions on the value of affiliates such as Wealthsimple, where fresh capital at a CA$13.8b valuation gives a clear market marker for that platform but not for how much of that value ultimately flows back to IGM Financial shareholders.
Uncover why IGM Financial's fair value indicates an 8% potential upside to its current price, a gap that could tighten if sentiment toward IGM Financial improves.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between CA$89.25 and about CA$92.85, which suggests some retail investors see limited mispricing in IGM Financial. Those views sit beside real execution questions around fee pressure, advisor support and whether AI, Wealthsimple and other affiliates shift earnings quality. Readers should compare these competing angles, and weigh several community perspectives before forming a view.
Explore another IGM Financial fair value estimate, including one that suggests there may be as much as 12% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IGM Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IGM Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IGM Financial's overall financial health at a glance.
Looking for more IGM Financial style investment ideas?
If the IGM Financial story has sharpened your thinking around fees, balance sheets and capital allocation, widen the lens and compare it with other businesses riding similar themes using the Simply Wall St Screener.
- For investors who want quality at a discount, start with companies that screen well on valuation and fundamentals through the 4 high quality undervalued stocks.
- If capital preservation matters most to you, focus on businesses that pass strict risk checks using the 8 resilient stocks with low risk scores.
- When you care about resilience as much as returns, look at companies with strong balance sheets and solid financial footing via the list of solid balance sheet and fundamentals (6 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com