
Textron Stock Jumps Into Focus After Earnings Beat And Higher 2026 Guidance
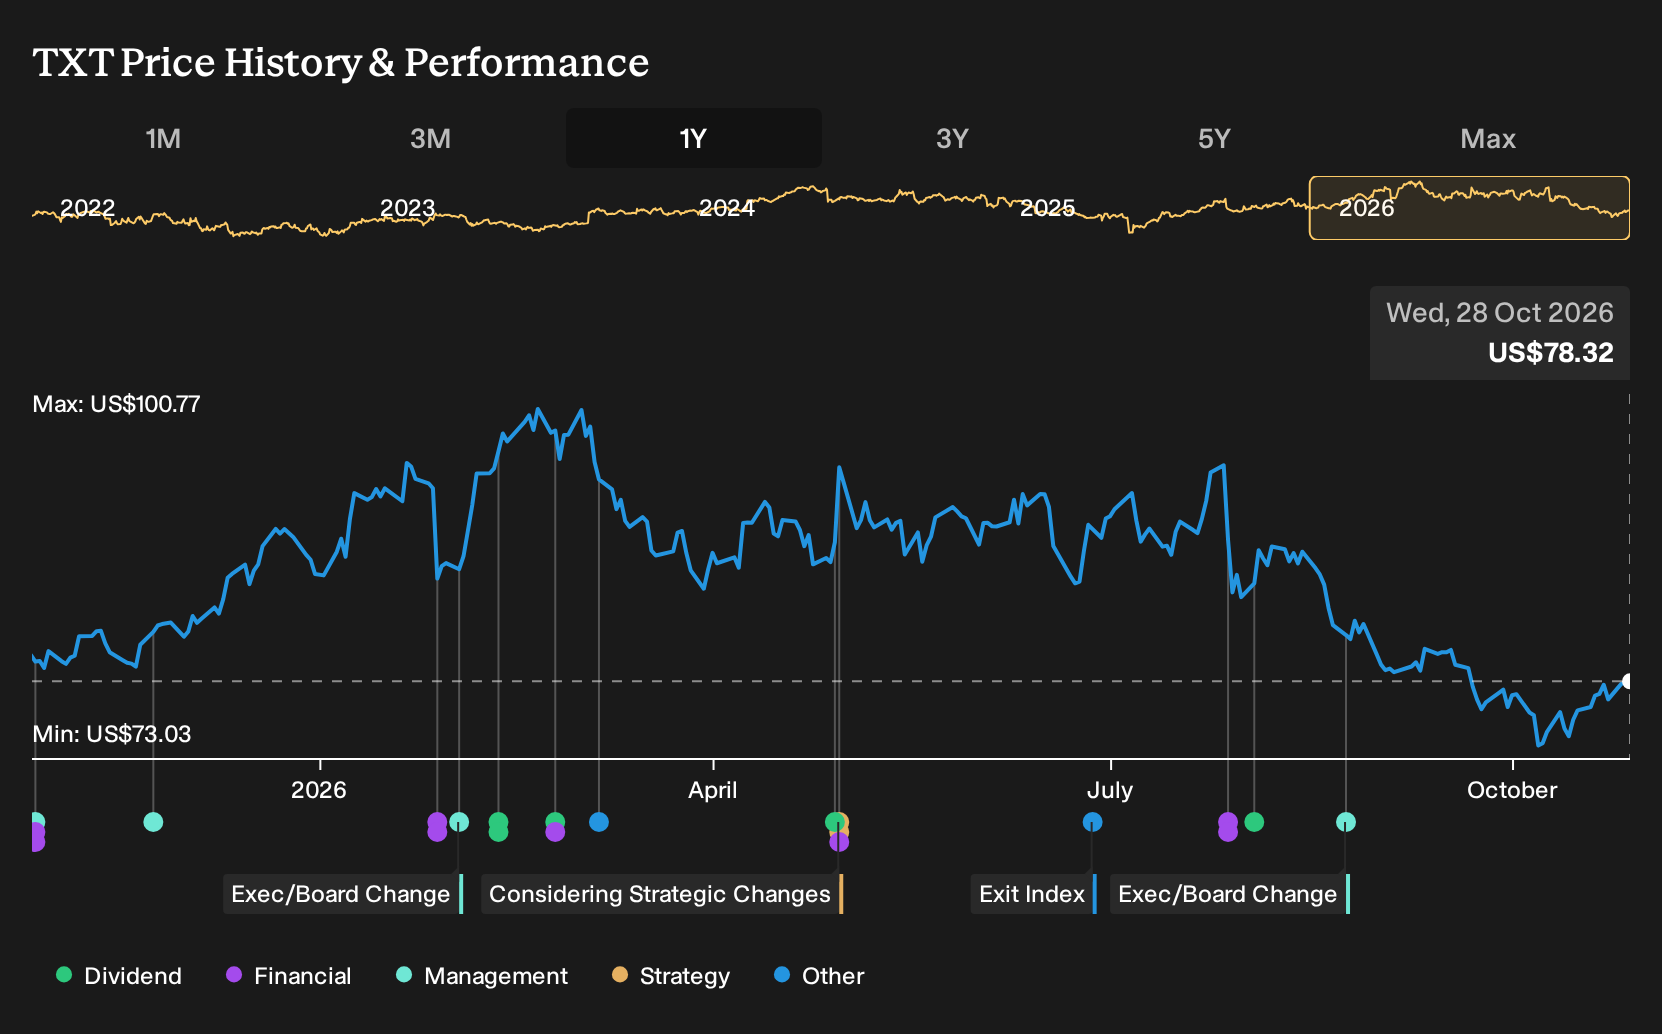
- Textron reported third quarter 2026 revenue of US$3,751 million and net income of US$270 million, with higher diluted EPS from continuing operations compared with the prior year period, and also released stronger nine month figures.
- Management raised 2026 GAAP EPS guidance from a prior US$5.39 to US$5.59 range to US$5.64 to US$5.74 and projected income from continuing operations between US$985 million and US$1,000 million, which reflects greater confidence in the current operating plan.
- Attention now shifts to how Textron's investment narrative around execution, margins and long term programs aligns with this upgraded earnings outlook.
Scan how Textron’s earnings upgrade compares with other potential breakouts across our hand picked 26 high quality undervalued stocks for your watchlist.
Textron Investment Narrative Recap
For someone owning Textron, the core belief is that aviation, Bell and long duration defense programs can compound earnings as execution gets cleaner. The latest quarter supports that story, with higher revenue, net income and EPS and a guidance raise that signals management sees the current operating plan holding up. The near term swing factor is still margin recovery in aviation and Bell.
The biggest risk stays the same. Manufacturing inefficiencies, MV-75 funding timing and future catch up charges could pressure reported profit even if sales remain healthy. The fresh numbers do not remove those issues; they suggest Textron has a bit more cushion against them in the short term.
The most relevant new data point is the higher 2026 GAAP EPS and income guidance. Management now expects US$5.64 to US$5.74 in EPS from continuing operations and US$985 million to US$1,000 million of income, compared with the prior range. That update ties directly to the earnings catalysts investors have been watching.
Higher guided profitability gives more support to the thesis around aviation margin repair, Bell program execution and the planned Industrial separation because it shows the current year is tracking ahead of the earlier plan. It also raises the bar. Any delay in MV-75 funding, larger than expected LRIP charges or fresh production issues would now be judged against a higher earnings baseline.
Textron's current analyst narrative points to revenues of US$16.8b and earnings of US$1.2b by 2029, based on an assumed 3.1% yearly revenue growth rate and an earnings increase of about US$261m from US$939.0m today.
Uncover how Textron's fair value indicates a 30% potential upside to its current price before the market closes that valuation gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Textron’s Aviation margin recovery as the real swing factor. Before this earnings beat and guidance hike, they were already modelling revenue of about US$18.1b and earnings near US$1.3b by 2029. That is a meaningfully brighter path than consensus, and it might shift again once this new information is absorbed. Readers like you can treat that gap in expectations as an invitation to compare several views before deciding what story feels reasonable.
Explore 4 other Textron fair value estimates, including one that suggests as much as 89% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Textron research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Textron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Textron's overall financial health at a glance.
Looking for more investment ideas beyond Textron?
Once you have formed a view on Textron, it can help to cross check that thesis against other opportunities that fit different risk and income profiles, all within the Simply Wall St Screener.
- If you want potential growth with strict quality filters on financial strength, review the 19 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation sits high on your priority list, compare Textron with a 32 resilient stocks with low risk scores that score well on resilience and balance sheet metrics.
- If income is a key goal alongside capital growth, line up Textron next to a 6 dividend fortresses and see how the cash return profile differs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com