
CRISPR Therapeutics (CRSP) Stock Still Looks Rich Against Its Balance Sheet
CRISPR Therapeutics has delivered a mixed share price story in recent years, and that uneven record raises a clear question about whether today’s US$54.11 price is sensible when set against the company’s book value. For anyone looking at the biotech, the issue is less about the latest headline move and more about how much of its balance sheet strength is already embedded in the stock.
- Over the past 5 years, the share price has fallen 44.1%, which puts the focus squarely on whether the current valuation still lines up with what the balance sheet actually supports.
- The business model is capital intensive and research heavy, which can influence how quickly spending on new therapies turns into assets on the balance sheet and affects how book value backs the equity.
- Your read on CRISPR Therapeutics is one view; the desks covering it have another. See what analysts think CRISPR Therapeutics's shares could be worth.
The issue now is whether the current share price is adequately supported by CRISPR Therapeutics’ book value when compared with the industry average.
If you are weighing CRISPR Therapeutics against what its balance sheet can justify, it can help to line it up next to solid balance sheet and fundamentals stocks screener (24 results).
Does CRISPR Therapeutics Look Pricey on Book Value?
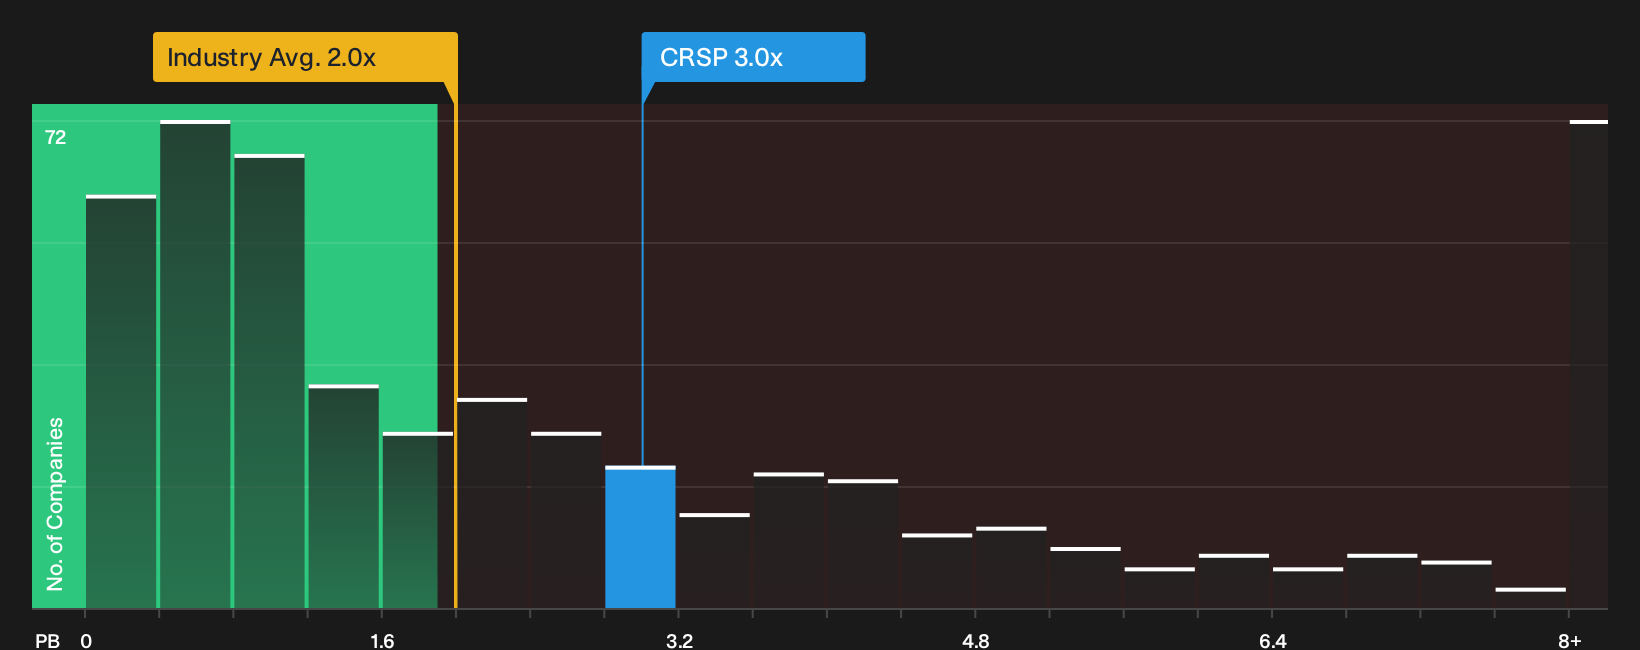
P/B suits CRISPR Therapeutics because the business is still shaped more by its research pipeline and balance sheet than by steady earnings. On this yardstick, the stock trades on a P/B of about 3.0x, compared with an industry average for biotechs of roughly 2.0x. That gap means investors are currently paying a higher price for each dollar of CRISPR Therapeutics’ book value than is typical across the sector.
Such a premium can reflect confidence in the company’s research portfolio or the quality of assets on its balance sheet, but it also raises the bar for what the future needs to justify. If the pipeline, cash position and risk profile do not match that higher multiple in your view, the shares can look overvalued relative to peers on this single measure. Explore the numbers behind CRISPR Therapeutics's P/B valuation.
The CRISPR Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/B puzzle for CRISPR Therapeutics leaves off by spelling out what kind of future growth, profitability and earnings profile would need to hold for the shares to be worth materially more or less than today's price on the Community page. Each narrative treats CRISPR Therapeutics' implied fair value as a specific thesis about the business, which you can track over time as new information arrives.
The community is divided on CRISPR Therapeutics, with one side seeing meaningful upside from the pipeline and the other flagging execution risk at this valuation.
Bull case: 38% undervalued
"Progression of CTX310 into later stage development following Phase 1a data that showed up to 80% ANGPTL3 reduction in the liver and around 50% LDL and triglyceride reductions for at least a year positions CRISPR Therapeutics to enter large cardiometabolic markets..."
Discover why this Narrative puts CRISPR Therapeutics at 38% undervalued.
Bear case: 23% overvalued
"The current valuation, with a market value of roughly US$3.5b compared with about US$2.4b of cash and a Neutral rating from UBS, implies limited upside for the CRISPR Therapeutics share price unless the pipeline delivers clear, near-term proof of value..."
Explore why this Narrative puts CRISPR Therapeutics at 23% overvalued.
Before making a call on CRISPR Therapeutics, there is one more factor to check
Book value and pipeline only tell part of the story for CRISPR Therapeutics, because the people steering the business and how their rewards line up with your interests can tilt the risk and payoff profile. See who runs CRISPR Therapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com