
Alaska Air (ALK) Stock May Sit Below Fair Value Despite Expansion Plans
Alaska Air Group, trading around US$35.58, has been through a rough stretch on the market, which raises a simple but important question for you as an investor. Does the current share price line up sensibly with the airline's ability to generate sales after a tough few years and a busy expansion plan.
- Over the past 5 years the stock has fallen about 36.4%, which puts the spotlight on whether the business's sales can support even the current valuation level.
- Recent news around international route growth, higher fuel costs and investment in hubs like Honolulu can reshape expectations for future revenue and the timing of cash returns to shareholders.
- There is a second opinion on Alaska Air Group worth weighing. See what analysts think Alaska Air Group's shares could be worth.
For investors, the debate is whether Alaska Air Group's present price is adequately supported by the sales the airline generates today and is reasonably expected to produce over time.
If you want to balance Alaska Air Group's recent share price swings with a broader watchlist, a focused screen of solid balance sheet and fundamentals stocks screener (24 results).
Is Alaska Air Group Still Cheap on Sales?
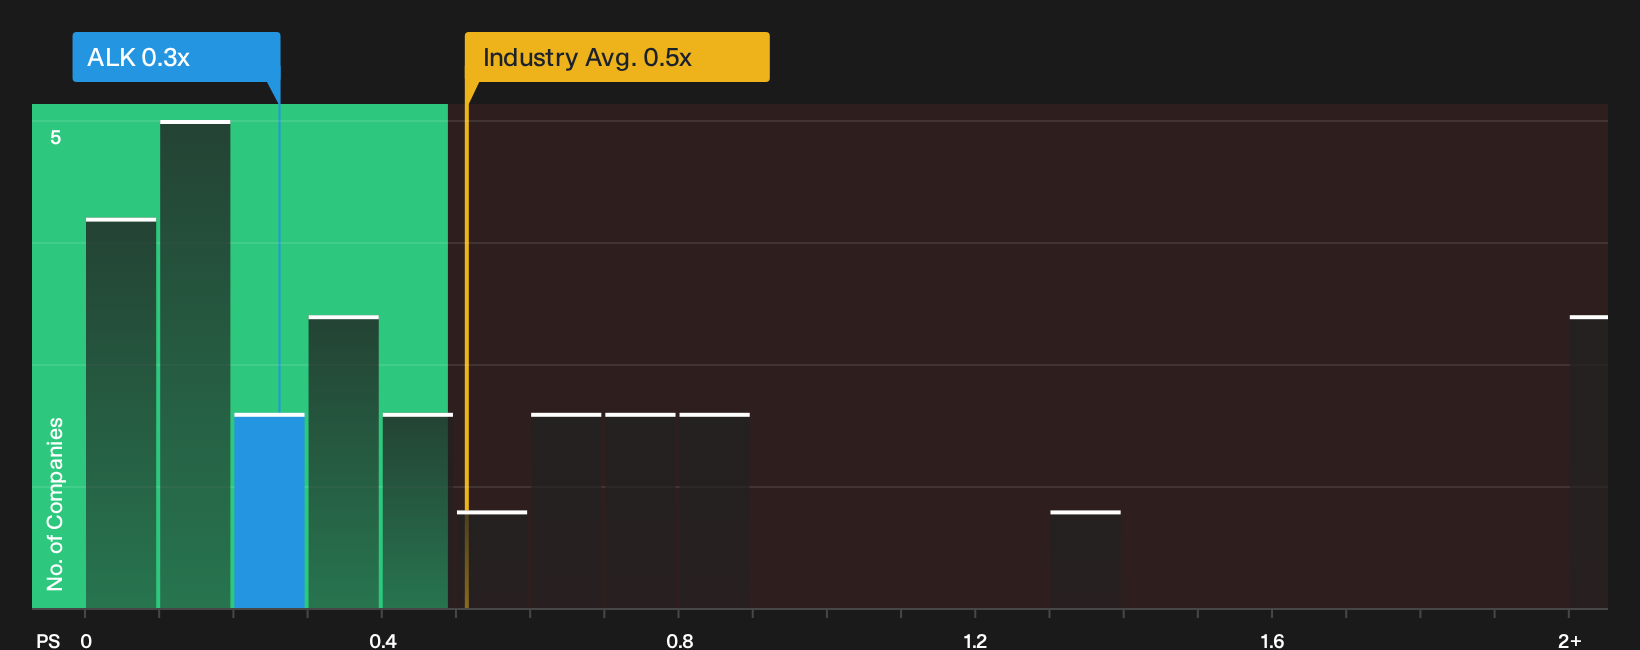
P/S is a useful lens for Alaska Air Group because airlines are often judged on how much investors are willing to pay for each dollar of revenue. On this score, the stock trades on a P/S of 0.3x, compared with an Airlines industry average of about 0.5x and a peer group around 0.7x. That puts the current tag on Alaska Air Group’s revenue stream well below what investors are paying for similar carriers.
The Fair Ratio model, which estimates the P/S level you might expect given Alaska Air Group’s size, margins, growth outlook and risk profile, also points to the current 0.3x sitting below that tailored benchmark. Because management is talking up major international expansion even after reporting a Q3 2026 GAAP loss driven by higher fuel costs, this discount signals that the market is giving limited credit to those projects in the share price right now. For you as a shareholder, the key question is whether the quality and sustainability of future sales can justify a higher multiple than the one implied today. Explore the numbers behind Alaska Air Group's P/S valuation.
The Alaska Air Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle leaves off for Alaska Air Group and explain which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Each narrative treats fair value as a concrete thesis about Alaska Air Group's business that you can watch over time, rather than a one off snapshot.
Community views on Alaska Air Group are split between investors who see the long term plan as underappreciated and others who think fuel and execution risks already justify caution.
Bull case: 35% undervalued
"The successful integration of Hawaiian Airlines and continued progress on the targeted US$1b profit improvement by 2027, supported by completed milestones such as a single operating certificate and unified loyalty program, can add incremental profits and support earnings per share…"
Discover why this Narrative puts Alaska Air Group at 35% undervalued.
Bear case: 8% overvalued
"Although Alaska Air Group is increasing revenue from premium cabins, loyalty and cargo, recent adjusted net losses of $192 million in Q1 2026 and $102 million in Q2 2026 highlight that a sharp spike in jet fuel costs can outweigh this diversification…"
Explore why this Narrative puts Alaska Air Group at 8% overvalued.
One more Alaska Air Group check that sits beside the price tag
Analyst roadmaps for Alaska Air Group a few years from now give you a separate yardstick to compare with today's valuation, and they do it without declaring future strength or weakness. Explore where analysts expect Alaska Air Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com