
W. R. Berkley (WRB) Looks Fully Priced After Third Quarter 2026 Results
W. R. Berkley (WRB) just posted third quarter 2026 results, reporting revenue of US$3,738.81m and net income of US$446.01m. These figures may prompt investors to reassess recent share performance.
Recent trading shows a mixed picture for W. R. Berkley. The share price is US$71.63 after declining 1.04% on the day and 3.65% over the past week. However, the 30 day share price return of 5.87% hints at rebuilding momentum, while the 3 year total shareholder return of 69.82% and 5 year total shareholder return of 122.45% underline how long term holders have been rewarded.
Scan how W. R. Berkley compares with other insurance and financial stocks that pair solid fundamentals with resilient balance sheets using our curated list of solid balance sheet and fundamentals (24 results)
W. R. Berkley shares have slipped on softer quarterly earnings even as longer term returns remain strong, which leaves one issue for investors to weigh: Does the current price still offer attractive risk compared with the potential reward?
Most Popular Narrative: 3% Overvalued
The most followed narrative on W. R. Berkley pegs fair value at $69.41, slightly below the last close at $71.63. This suggests the stock is pricing in a lot of good news already, while still leaning on underwriting strength and capital returns to support that stance.
The expanding complexity of global business and assets is driving demand for specialty insurance solutions. W. R. Berkley is building on this with mid single digit gross and net premium growth in its Insurance segment, alongside current accident year ex cat combined ratios around 89%, which can support revenue and underwriting income.
See why 6 investors see W. R. Berkley as 3% overvalued.
Result: Fair Value of $69.41 (OVERVALUED)
Still, the narrative around W. R. Berkley could be tested if softening commercial pricing eats into underwriting margins, or if the reinsurance pullback drags on premium volume.
Find out about the key risks to this W. R. Berkley narrative.
Another View on W. R. Berkley’s Valuation
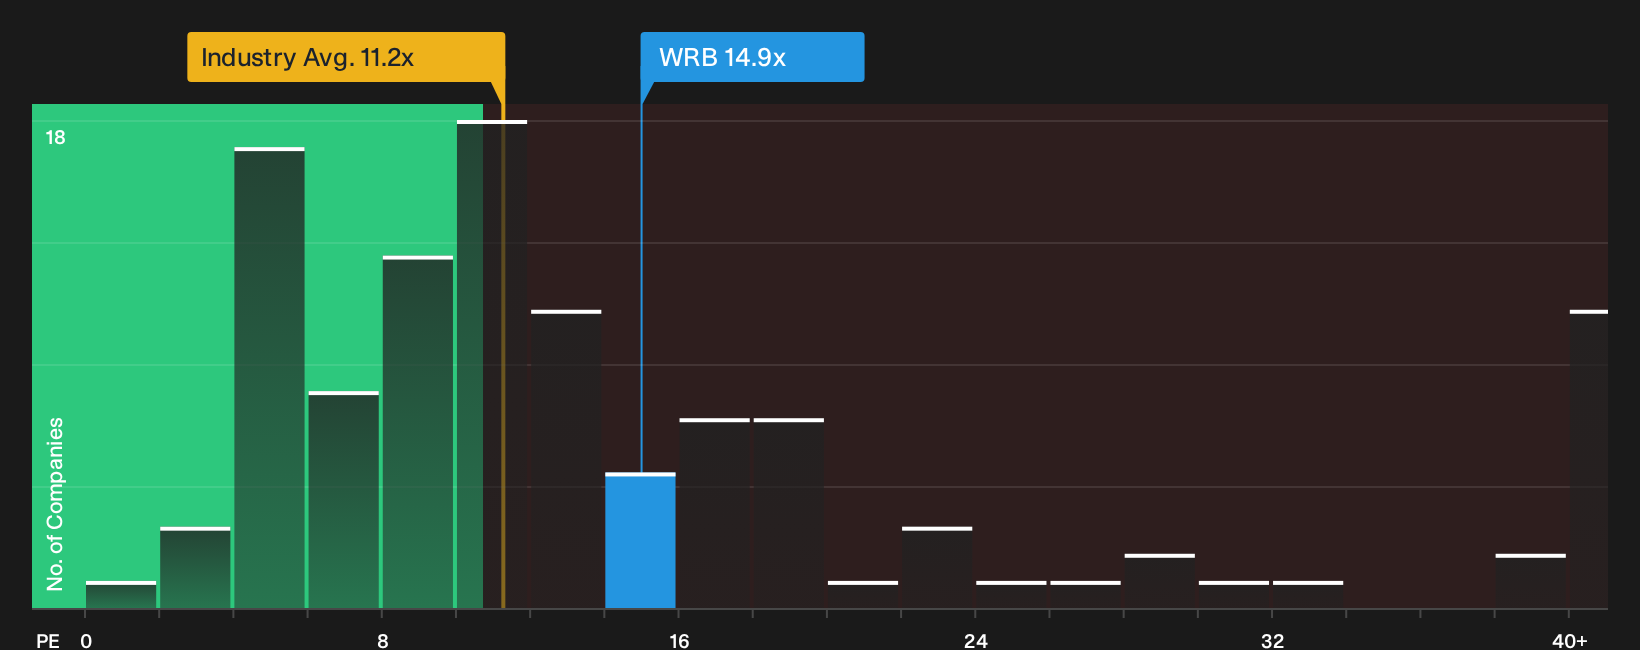
Analyst targets suggest W. R. Berkley is roughly fairly priced at around $69.41. A different lens tells a tougher story. The current P/E of 14.9x sits well above both the estimated fair ratio of 10.4x and the US insurance peer average of 11x, which highlights valuation risk if sentiment cools.
That kind of premium can persist for a while, but it leaves less room for error than a stock priced near its fair ratio. Investors need to decide whether W. R. Berkley’s quality justifies paying this price at the current level or whether patience could offer a better entry point.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out W. R. Berkley for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on W. R. Berkley are mixed so far. If you want a clearer picture, act quickly, review the same data, and weigh both sides for yourself with 1 key reward and 1 important warning sign
Looking for more W. R. Berkley style investment ideas?
Do not stop with W. R. Berkley. Broaden your watchlist with fresh opportunities that match your goals, so you are not reacting after markets move first.
- Target potential mispricing by scanning companies that pair quality fundamentals with attractive valuations through our 26 high quality undervalued stocks.
- Build a steadier income stream by reviewing higher yielding payers that aim for resilience using our 6 dividend fortresses.
- Focus on capital preservation first by filtering for businesses with stronger finances and lower risk profiles via our 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com