
3 British Undervalued Stocks With P E Under 15x
Rising energy led inflation expectations in Europe and the likelihood of more rate hikes from the European Central Bank are putting steady cash generation back in the spotlight for UK investors. When borrowing stays expensive, companies with solid cash flow and undemanding prices can matter more. This article walks through three London listed stocks that screen as cash rich and potentially undervalued on a discounted cash flow basis.
The three stocks covered next are just a starting sample, and the full screen surfaced 25 more companies with similarly cash focused stories that are not included here. To hunt for your own high conviction ideas, head straight into the Undervalued Stocks Based On Cash Flows screener to identify and analyze which cash flow opportunities fit your checklist.
Shell (LSE:SHEL)
Overview: Shell is a global energy and petrochemicals group that turns oil and gas into fuels, chemicals, and low carbon solutions while expanding its Renewables and Energy Solutions activities.
Operations: Shell generates most of its revenue from Marketing at about US$135b and Chemicals and Products at about US$132b, with smaller contributions from Renewables and Energy Solutions at about US$42b and Integrated Gas at about US$49b.
Market Cap: £225.7b
Shell matters for this cash flow focused screen because it combines large scale fossil fuel earnings with a low carbon franchise that is being built to generate future cash flow rather than just tick climate boxes.
"With an LNG portfolio exceeding 60 million tons and significant trading capabilities, Shell is a company that can benefit from volatility in the global gas market. Economic growth in Asia and energy security concerns in Europe are expected to increase LNG demand by over 50% by 2040.
The key question is how a shift in where those cash flows are earned ultimately shapes pricing power and returns.
That shift is the crux of Shell’s story, and the full narrative for Shell shows how its cash engine, LNG exposure and low carbon plans could be decoupling from headline oil cycles.
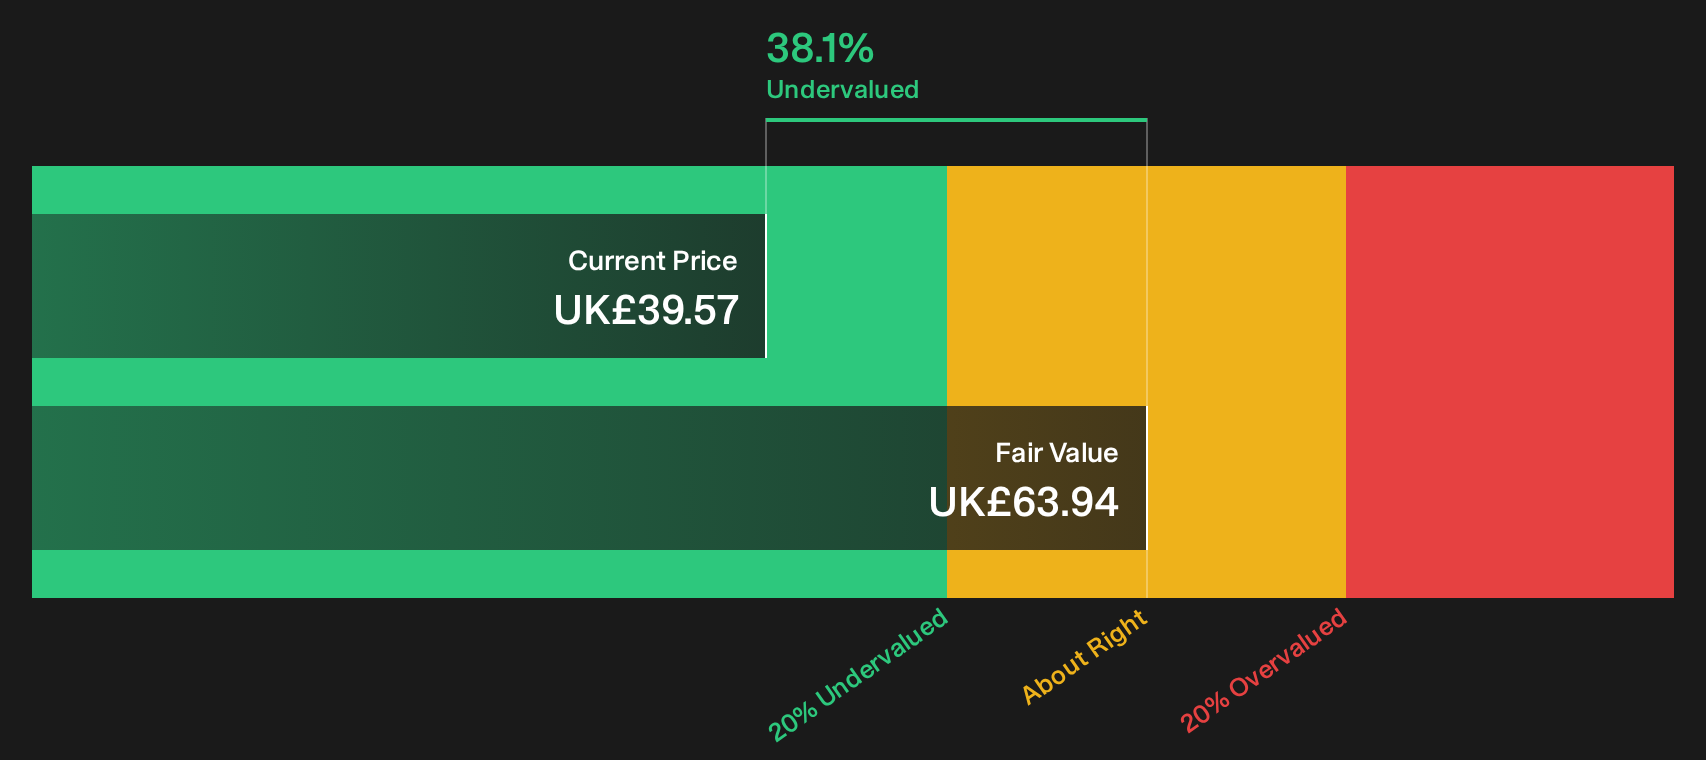
Gamma Communications (LSE:GAMA)
Overview: Gamma Communications runs cloud-based telephony, unified communications and managed network services that generate recurring subscription-style cash flows from business customers.
Operations: Gamma Communications earns most of its revenue from Enterprise at £136 million and Germany SME at £120 million, within a wider £463.4 million UK-led footprint.
Market Cap: £976 million
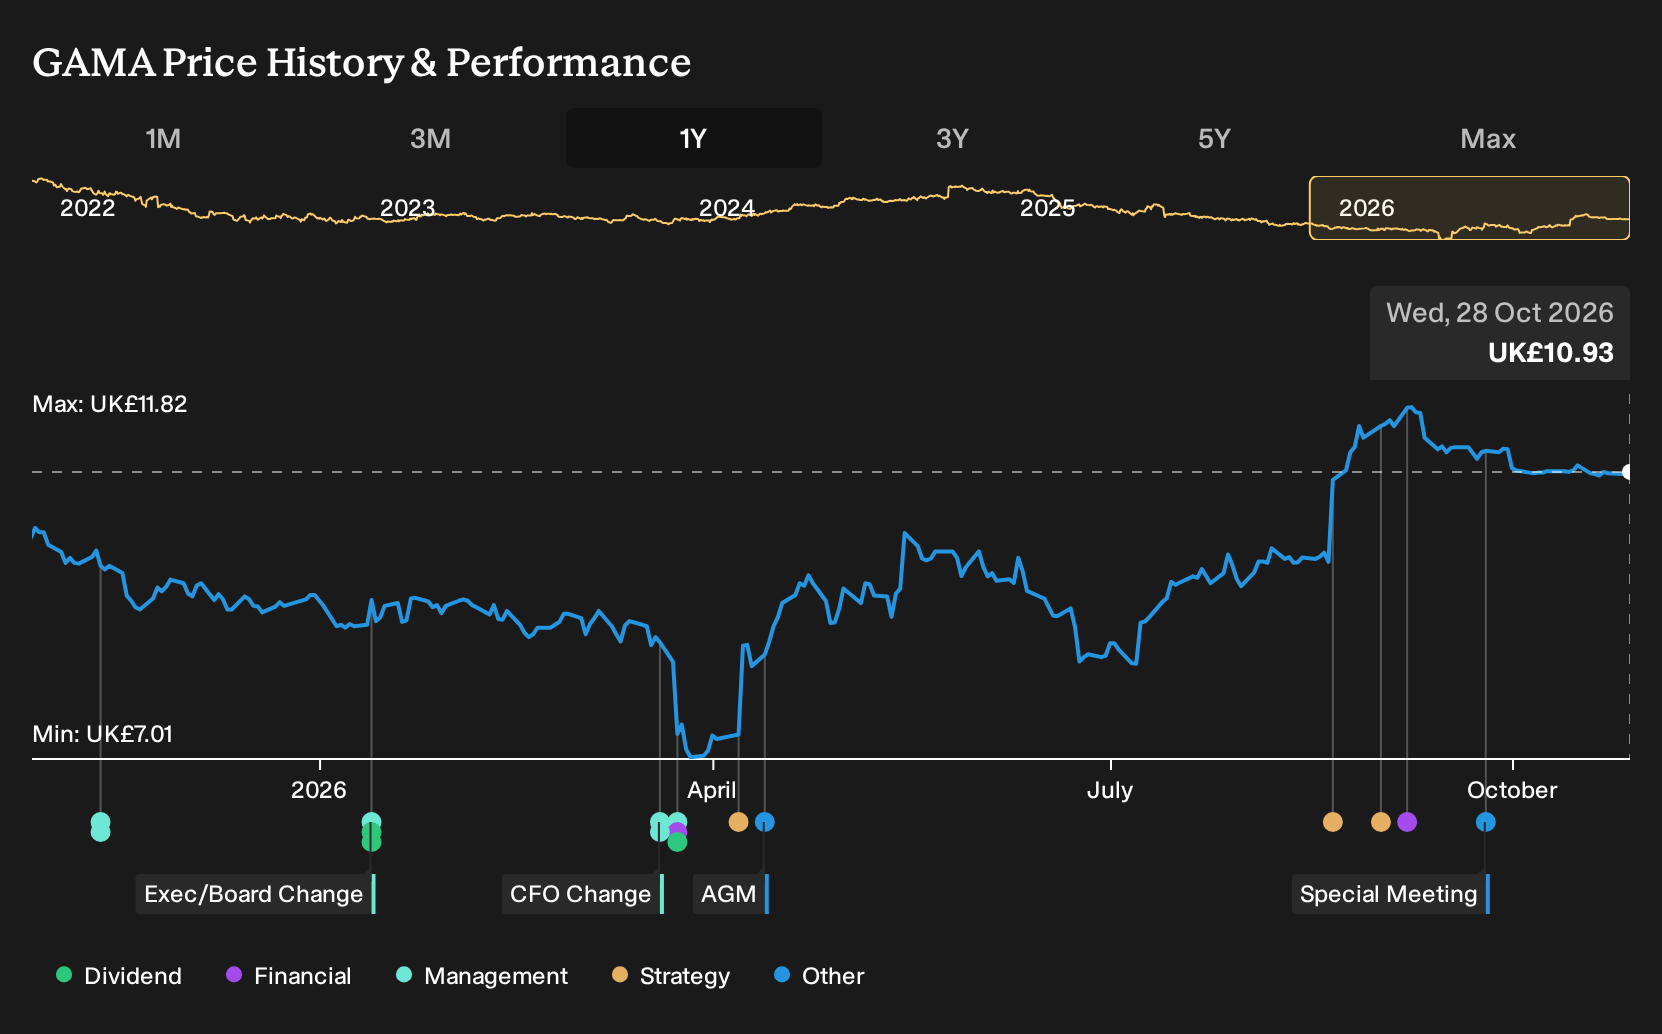
Gamma Communications fits the cash flow theme through its subscription communications platforms. However, what really matters now is how ownership around the takeover story shapes what those cash streams are worth.
"The level of disclosed interest from institutions such as Kite Lake Capital Management and Natixis creates scope for Gamma Communications to convert short term takeover related positioning into longer duration shareholders that support capital access and potentially a lower cost of equity, which can influence earnings over time."
One question for investors is what happens if a quiet shift in who ultimately holds the stock changes the terms on which future cash flows are priced.
If that ownership shift is what you care about, read the full narrative for Gamma Communications to see how the Gamma Communications thesis evolves if takeover interest stalls or accelerates.
Autotrader Group (LSE:AUTO)
Overview: Autotrader Group runs a UK automotive marketplace that connects car buyers, sellers, and advertisers, earning recurring fees from online listings and related services.
Operations: Autotrader Group generates about £585 million from the Auto Trader segment and £39 million from Autorama, all from the United Kingdom.
Market Cap: £4.1b
Autotrader Group matters for this cash flow focused screen because the main Auto Trader platform produces steady, fee based income that can support a discounted cash flow argument when the share price lags those fundamentals.
"Auto Trader Group's continued rollout of Deal Builder, with inquiries and Buying Signals leads converting at least twice as well as average inquiries and around half of deals occurring outside traditional hours, points to further monetisation of higher quality leads that can support retailer revenue and Auto Trader's own ARPR and earnings over time."
The key question is what happens to that cash generation story if a single pressure point quietly shifts how much pricing power Autotrader Group really has.
If that pressure point matters to you, the full narrative for Autotrader Group explains in detail how Autotrader Group’s pricing power, cash generation and risk factors could be shifting beneath the surface.

Seeking Fresh Alternatives Before Others?
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Do not get caught watching prices flying without you. Consider acting after careful research and reflection.
- Spot cash rich compounders early and scan a curated pool of resilient businesses using the 10 high quality undervalued stocks.
- Review a carefully filtered group of high yield candidates with the 4 dividend fortresses.
- Focus on sturdier balance sheets and track financially disciplined operators through the list of solid balance sheet and fundamentals (10 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com