
3 US Industrial Stocks With Earnings Leverage to Stronger GDP Growth
A hotter than expected 3.4% US Q3 2026 GDP print has put cyclical consumer and industrial stocks back under the spotlight, as stronger domestic activity, firmer business investment and higher government spending reshape where risk may be rewarded. Sitting on the sidelines may mean watching others react first. This article walks through three stocks from our U.S. Cyclical Consumer & Industrials screener that appear especially exposed to this economic surprise, and explains why that may matter for your portfolio decisions.
The three stocks below are a starting sample from this theme. The full screen surfaced 23 more U.S. cyclical consumer and industrial companies with similarly detailed stories that are not covered here. To see the broader opportunity set, head straight into the U.S. Cyclical Consumer & Industrials Benefiting from Strong Domestic GDP Growth screener to identify, filter and analyze the highest conviction ideas for your watchlist.
Astec Industries (ASTE)
Overview: Astec Industries makes road building and materials processing equipment that ties directly into U.S. infrastructure and non-residential construction cycles.
Operations: Astec Industries generates about $913.9 million from Infrastructure Solutions and $676.8 million from Materials Solutions, with US$1.2b of revenue from the United States.
Market Cap: US$886 million
Astec Industries sits squarely in the U.S. cyclical industrial sweet spot, with equipment demand closely linked to how aggressively governments and contractors push ahead on highways, bridges and large non-residential projects.
"Passage of U.S. infrastructure bills, increased state and local transportation contract awards, and ongoing multi-year federal funding are described by some analysts as potential drivers of sustained, visible demand for Astec's core road construction and materials equipment."
What ultimately happens to Astec Industries margins and cash generation now hangs on how one less obvious cost pressure plays out.
That hidden input cost risk is exactly where the full narrative for Astec Industries picks up, showing how Astec Industries could still turn infrastructure momentum into stronger earnings power.

THOR Industries (THO)
Overview: THOR Industries builds a broad range of towable and motorized recreational vehicles, selling RVs and related components across North America and Europe.
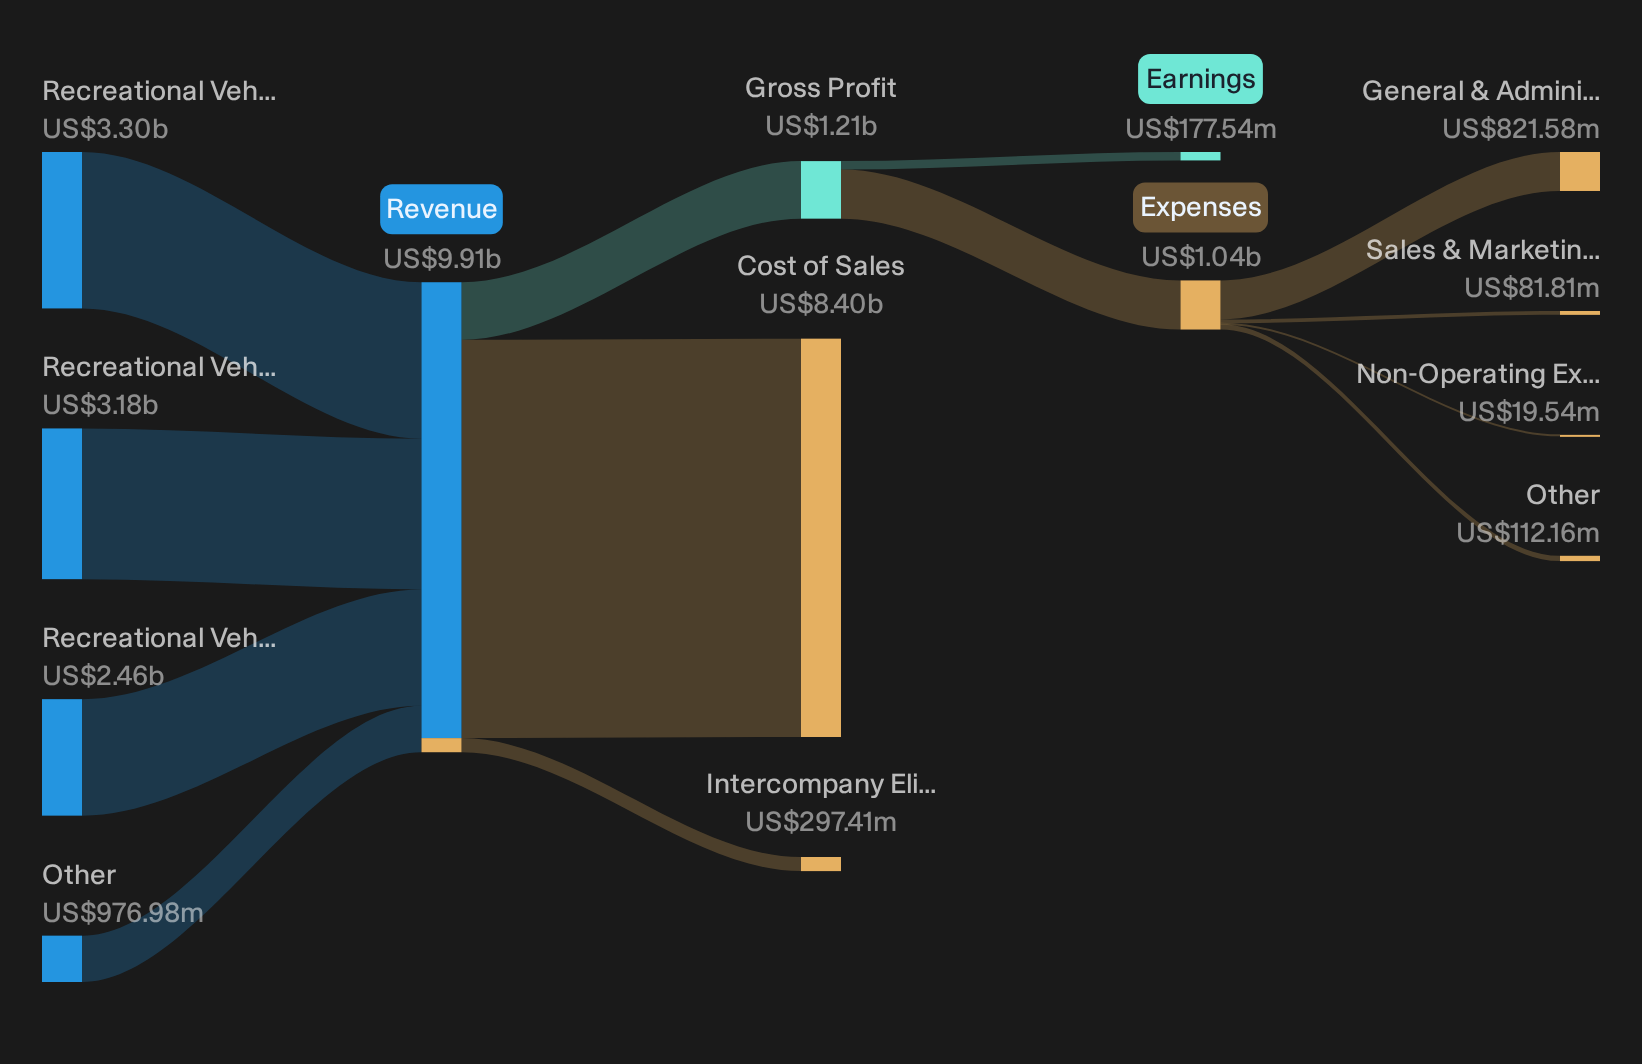
Operations: THOR Industries generates about US$3.2b from North American towable RVs, US$2.5b from North American motorized RVs, and US$3.3b from European RVs, supported by US$5.8b of sales in the United States.
Market Cap: US$3.6b
THOR Industries is a pure U.S. consumer cyclical story, with RV purchases closely tied to household confidence and discretionary spending that often align with strong GDP prints such as the latest 3.4% figure. Investors who want exposure to a rebound in big-ticket leisure demand may find it here. However, how one key pressure on already thin margins evolves could significantly influence overall returns.
With that margin squeeze in mind, move from headline GDP to what really matters in the 1 warning sign that could cap THOR Industries' next upswing
XPO (XPO)
Overview: XPO runs freight transportation networks anchored in North American less than truckload services that closely reflect U.S. industrial and consumer cycles.
Operations: XPO generates about US$5.1b from North American less than truckload services and US$3.5b from European Transportation across freight and logistics solutions.
Market Cap: US$22.0b
XPO ties the U.S. cyclical consumer and industrial theme together in a very direct way because its freight activity rises and falls with domestic goods demand. This makes execution on its freight network and technology upgrades especially important in a stronger GDP backdrop.
"XPO's ongoing investments in AI powered optimization and proprietary technology are now delivering productivity improvements above its prior 1.5 point target. Recent tools have cut damages by 50% and improved load quality by over 40% at test sites, which can support further operating ratio gains and earnings expansion as deployment widens."
What happens if a single cost and pricing assumption inside that freight network shifts will likely decide how much of this cycle XPO captures.
That inflection point is exactly where the full narrative for XPO picks up. It maps how XPO’s operating leverage, pricing power and AI gains could accelerate or stall through the next phase of the cycle.

Seeking Alternatives Before Momentum Flies
Fresh themes move fast, and the first breakout wave often arrives before most investors react. Scan under the radar for now, while information still matters, and get in early.
- Spot strong balance sheets before momentum traders pile in by running the list of solid balance sheet and fundamentals (24 results) and sharpening your shortlist while valuations still look reasonable.
- Ride the next leg of automation and AI-driven efficiency by checking the curated set inside the 93 robotics and automation stocks before the crowd catches these trends mid flight.
- Position for potential cash-return durability as yields stay in focus by screening through the 6 dividend fortresses and tightening your list of income-focused candidates early.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com