
What Amara Raja Investors Missed Before The Fall
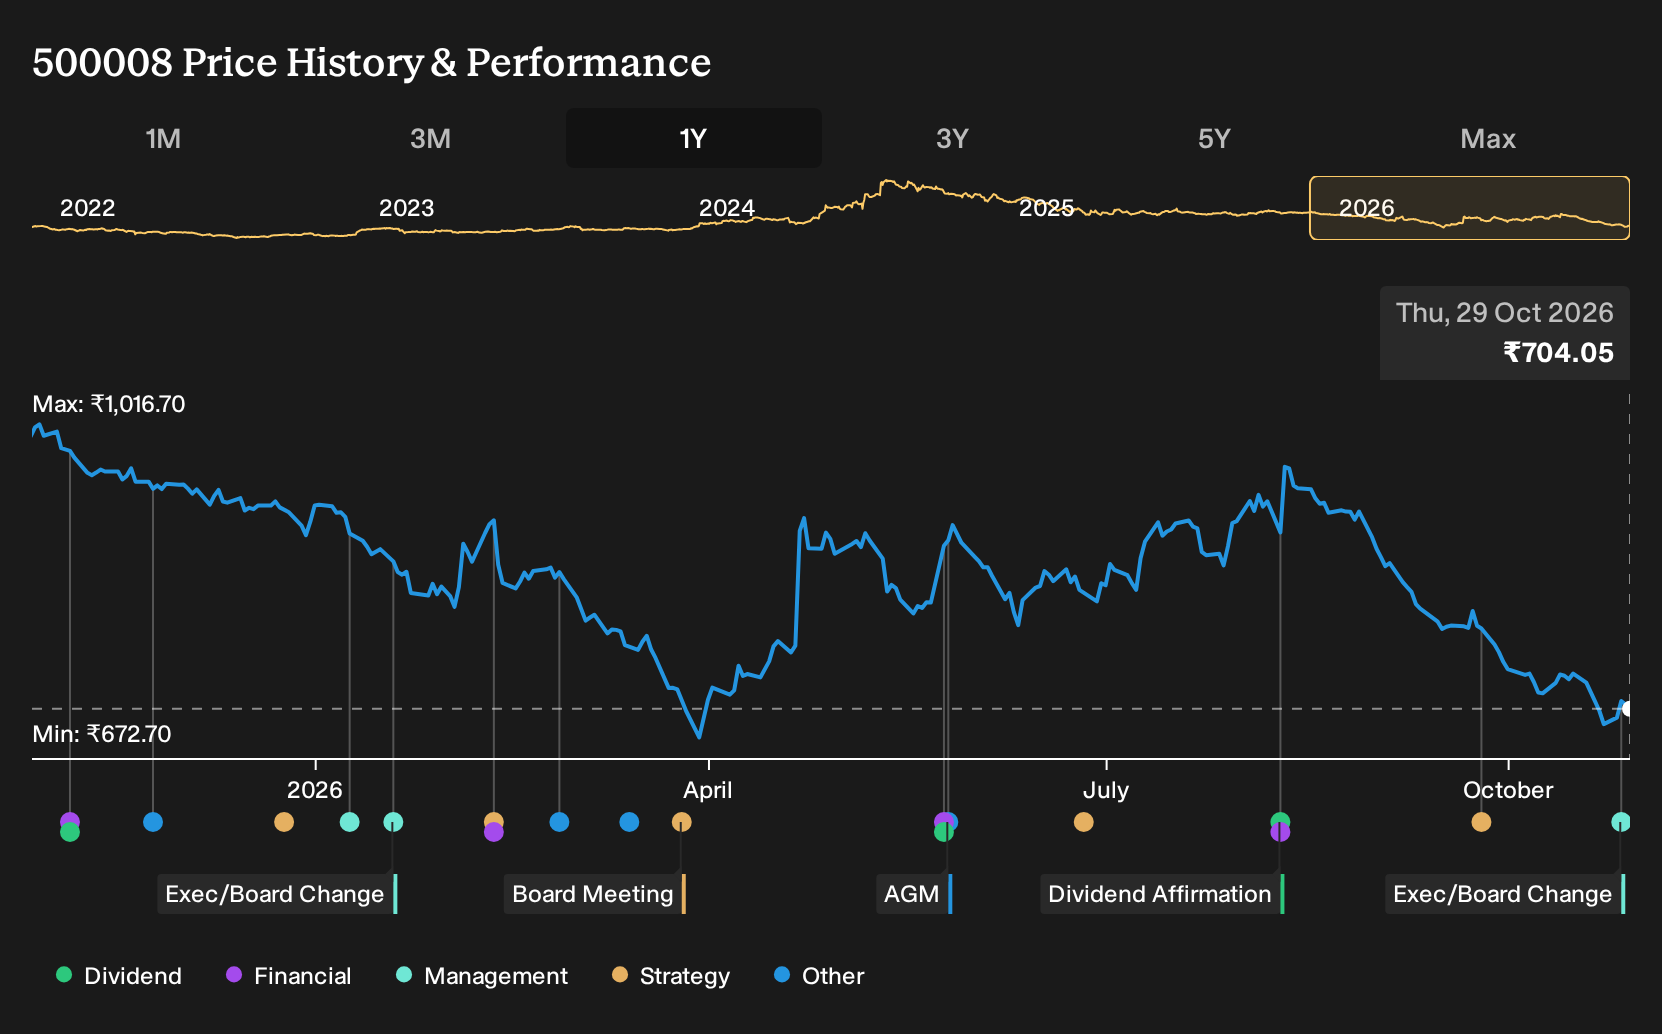
Results at Amara Raja Energy & Mobility moved in the right direction, yet shareholders saw a very different outcome. For Amara Raja Energy & Mobility shareholders, the loss over the past year was 29.9%, including dividends. Revenue and net profit in Q1 2027 were higher than in Q1 2026, but the net margin slipped. If you were weighing a purchase back in October 2025, what warning signs or mismatched expectations were already on the table?
The easy part of this move is behind Amara Raja Energy & Mobility. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Amara Raja Energy & Mobility
The shares cost ₹1,013 at the start of the period, and buyers had to decide which story about Amara Raja Energy & Mobility felt more convincing.
The bullish narrative pointed to heavy new energy investment and a fair value of ₹1,163, a price that only made sense if assumptions such as 7.2% annual revenue growth and a 7.7% profit margin proved accurate.
The bearish view focused on legacy risks and a fair value of ₹925, reflecting concerns that reliance on lead-acid batteries and execution risk on lithium projects could strain future earnings.
What The Results Changed For Amara Raja Energy & Mobility
The clearest fresh evidence came from Q1 2027, where Amara Raja Energy & Mobility reported revenue of ₹42,145.4m and net income of ₹1,909.4m versus ₹34,010.8m and ₹1,648m in Q1 2026. The net margin slipped from 4.8% to 4.5%, so profitability did not move in the direction the upbeat margin story assumed. Overall, the numbers cut both ways.
The key lesson is simple. When a thesis leans on margin expansion, do not just watch sales and profit. Track the reported net margin each quarter and see if it actually moves toward the scenario you are paying for.
What You Would Be Paying For Today With Amara Raja Energy & Mobility
Amara Raja Energy & Mobility now trades at ₹704, after the share price declined about 30% over the past year. The selected Narrative places its Fair Value above that level, based on a view that the market is not fully crediting newer energy storage plans.
Instead of hinging on the older lead-acid story, this Narrative focuses on lithium cells, BESS and recycling as potential drivers of earnings quality. A buyer today would be assuming these projects mature into commercially viable platforms that support higher and more stable margins over time.
"The main thing that has to go right is that in-house manufacturing, government support and R&D efforts on lithium cells, BESS and recycling translate into higher and more stable margins over time despite ongoing input cost and capital intensity pressures."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Amara Raja’s Theme Reappears
Looking at Amara Raja, you are really asking about energy security. Another business is wrestling with the same question from a different angle.
Electric vehicles and renewables do not just need batteries. They also rely on powerful magnets built from critical rare earth materials.
One producer is trying to supply those materials and magnets from closer to end markets. It is backed by government contracts and long agreements with large technology and auto customers.
Policy support, long-term deals and recycling projects could reshape how that enterprise earns money. If material flows keep shifting, your Amara Raja watchlist may not be the only place to look.
Could this be another way into the opportunity? → Explore the critical minerals opportunity and its 42% discount to one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com