
How Investors May Respond To GEO Group (GEO) 10 Year ICE Contract
- GEO Group reported that it entered a new 10 year management contract for the GEO owned 1,635 bed Northwest ICE Processing Center in Tacoma, Washington, with support services and access to medical care and transportation expected to generate about US$140 million in annual revenue through October 2036.
- The contract extends operational visibility at a large ICE facility for a full decade. This development may reshape how investors consider GEO Group's longer term revenue stability and cost planning tied to federal detention services.
- We will now look at how GEO Group's investment narrative could shift given this new decade long Northwest ICE Processing Center agreement.
GEO Group Investment Narrative Recap
To own GEO Group, you need to be comfortable with a business model tied heavily to US federal detention and supervision contracts, and the policy and funding decisions that sit behind them. The new 10 year Northwest ICE Processing Center agreement supports visibility on a large facility, which can help near term revenue planning but does not change the core policy risk around immigration enforcement and detention capacity.
In the short term, the main swing factor remains how quickly GEO Group brings additional ICE beds and monitoring programs into full use versus any pause or scaling back in appropriations. The biggest risk is still a shift in immigration priorities or budget allocations that leaves contracted or owned beds underused, which would pressure margins and cash generation even with long term contracts in place.
The debt redemption and credit agreement amendment disclosed on 19 October 2026 is highly relevant to the new Tacoma contract. GEO Group used cash to redeem US$650,000,000 of 8.625% Senior Secured Notes, leaving US$625,000,000 of gross debt outstanding, plus about US$36,000,000 of headquarters mortgage debt, and extended its US$550,000,000 revolving facility to 2031.
For you as a shareholder, that balance sheet shift affects how predictable contract cash flows translate into equity outcomes. Lower secured debt and longer dated bank lines can give GEO Group more room to handle swings in detention and ISAP volumes. At the same time, the larger US$1.25b share repurchase authorization amplifies the impact of any future changes in operating performance, both positive and negative.
GEO Group's current analyst narrative points to revenues of US$3.8b and earnings of US$137.8m by 2029, based on 9.9% yearly revenue growth and an earnings decline of about US$153.7m from US$291.5m today.
Uncover how GEO Group's fair value indicates a 37% potential upside to its current price, which could narrow quickly if GEO Group's story gains wider attention.
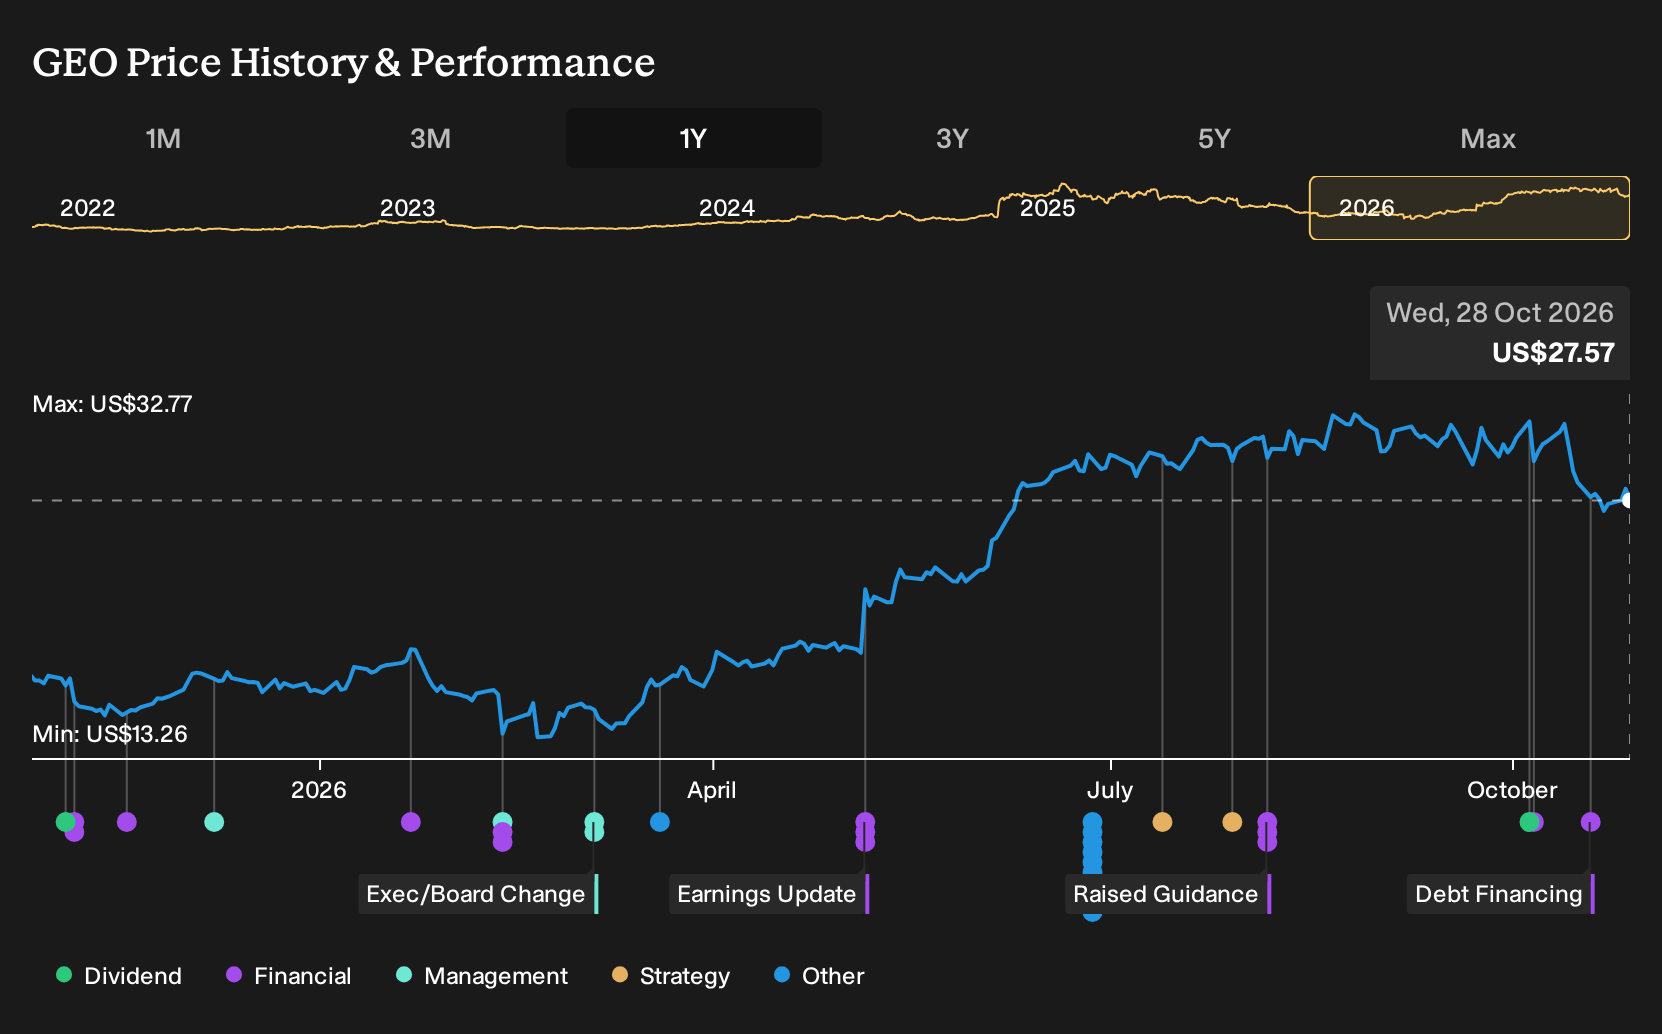
Exploring Other Perspectives
The most bearish GEO Group story hinges on funding interruptions. You see this in the skip tracing contract that can reach up to US$60 million a year yet contributed nothing in Q2 2026. Those analysts were penciling in about US$3.7b of 2029 revenue and US$250.0 million of earnings, and may revise again after this Tacoma deal.
Explore 3 other GEO Group fair value estimates, including one that suggests it could be worth just $37.75!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GEO Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking For More GEO Group Style Investment Ideas?
If GEO Group's contract driven cash flows appeal to you, it can be useful to widen the lens and compare it with other businesses that pair recurring revenue with resilient finances. The Simply Wall St Screener helps you quickly filter for those kinds of profiles without getting buried in spreadsheets.
- If you want potential value upside with stronger balance sheets, scan a 26 high quality undervalued stocks that already clear key quality and financial health checks.
- For investors who care most about cash strength and low refinancing risk, focus on companies that show up in our list of solid balance sheet and fundamentals (24 results) and start building a shortlist from there.
- Prefer steadier profiles over excitement, even if it means slower share price swings? Filter for a 32 resilient stocks with low risk scores and see which businesses fit that brief.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com