
Trial Design Update Might Change The Case For Investing In Edgewise Therapeutics Stock (EWTX)
- Edgewise Therapeutics recently drew fresh attention as investors focused on how the planned Phase 3 trial design for EDG-7500 in hypertrophic cardiomyopathy could reflect the drug's clinical profile and practical use in real cardiology practice.
- The key angle is the potential for a Phase 3 protocol that reduces reliance on echo based titration, which would directly influence how straightforward EDG-7500 might be to dose and monitor in real world care.
- We will now look at how Edgewise Therapeutics' investment narrative could shift if EDG-7500 proceeds with a less echo dependent Phase 3 design.
Scan cardiology focused opportunities with similar risk reward profiles by reviewing the hand picked 36 healthcare AI stocks that could benefit from clinically meaningful trial designs and real world treatment adoption.
Edgewise Therapeutics Investment Narrative Recap
For a shareholder in Edgewise Therapeutics, the central bet is that EDG-7500 and EDG-15400 progress cleanly through later stage cardiology trials and eventually support meaningful commercial use. The recent focus on a Phase 3 design that reduces echo based titration mainly fine tunes that story rather than rewriting it. The key near term swing factor still sits with Phase 3 execution quality and timelines for EDG-7500.
On the risk side, you are still looking at a business with no commercial revenue, a Q1 2026 net loss of US$49.0 million and a heavy spend profile. Any slippage in trial starts or readouts for EDG-7500 or EDG-15400 would likely extend the loss making period and keep pressure on valuation and future funding needs.
The most relevant corporate move around this news is the completed sale of sevasemten and the muscular dystrophy platform to Servier for US$1.55b upfront plus up to US$1.1b in milestones. That transaction leaves Edgewise Therapeutics more focused on cardiovascular programs, with capital earmarked for EDG-7500 in hypertrophic cardiomyopathy and EDG-15400 in HFpEF.
That sharper focus ties directly into the current catalyst stack. Management plans a Phase 3 start for EDG-7500 in Q4 2026 in both obstructive and nonobstructive HCM, using a protocol regulators have already called reasonable without echo based titration. Alongside the planned HFpEF Phase II for EDG-15400, this creates a concentrated but high stakes path where clinical execution, not balance sheet capacity, looks like the primary constraint.
Edgewise Therapeutics Analyst Assumptions And Valuation Setup
Analysts currently model Edgewise Therapeutics with no revenue today and forecast the top line to reach US$140.6 million by 2029, which works out to roughly US$28 million of revenue added each year if growth were spread evenly from a zero base. On the earnings side, the consensus framework uses a shift from a reported loss of US$197.2 million today to forecast earnings of US$24.1 million by 2029, which implies an earnings swing of about US$221.3 million over that period.
That earnings bridge comes from applying an assumed 17.1% net margin, in line with the current average for the US pharmaceuticals peer group, to the 2029 revenue estimate. The same model also assumes the share count grows 2.58% per year over the next three years as Edgewise Therapeutics funds late stage cardiology work on EDG-7500 and EDG-15400. To discount those future cash flows back to the present, the Simply Wall St report uses a 7.24% rate. This frames how sensitive the implied equity value can be to small changes in growth, profitability or capital costs.
The valuation overlay on top of those operating inputs is demanding. To line up with the consensus view, you would need to accept 2029 earnings of US$24.1 million and a P/E of 310.7x on that figure, compared with an industry multiple quoted at 16.4x. That gap points to a setup where a lot of the long term cardiology potential for Edgewise Therapeutics is already embedded in the models, even though the firm is still running at a quarterly net loss and has no commercial sales.
Edgewise Therapeutics' narrative projects revenue of US$140.6 million and earnings of US$24.1 million by 2029. This implies yearly revenue growth from a zero base and an earnings improvement of about US$221.3 million from a loss of US$197.2 million today.
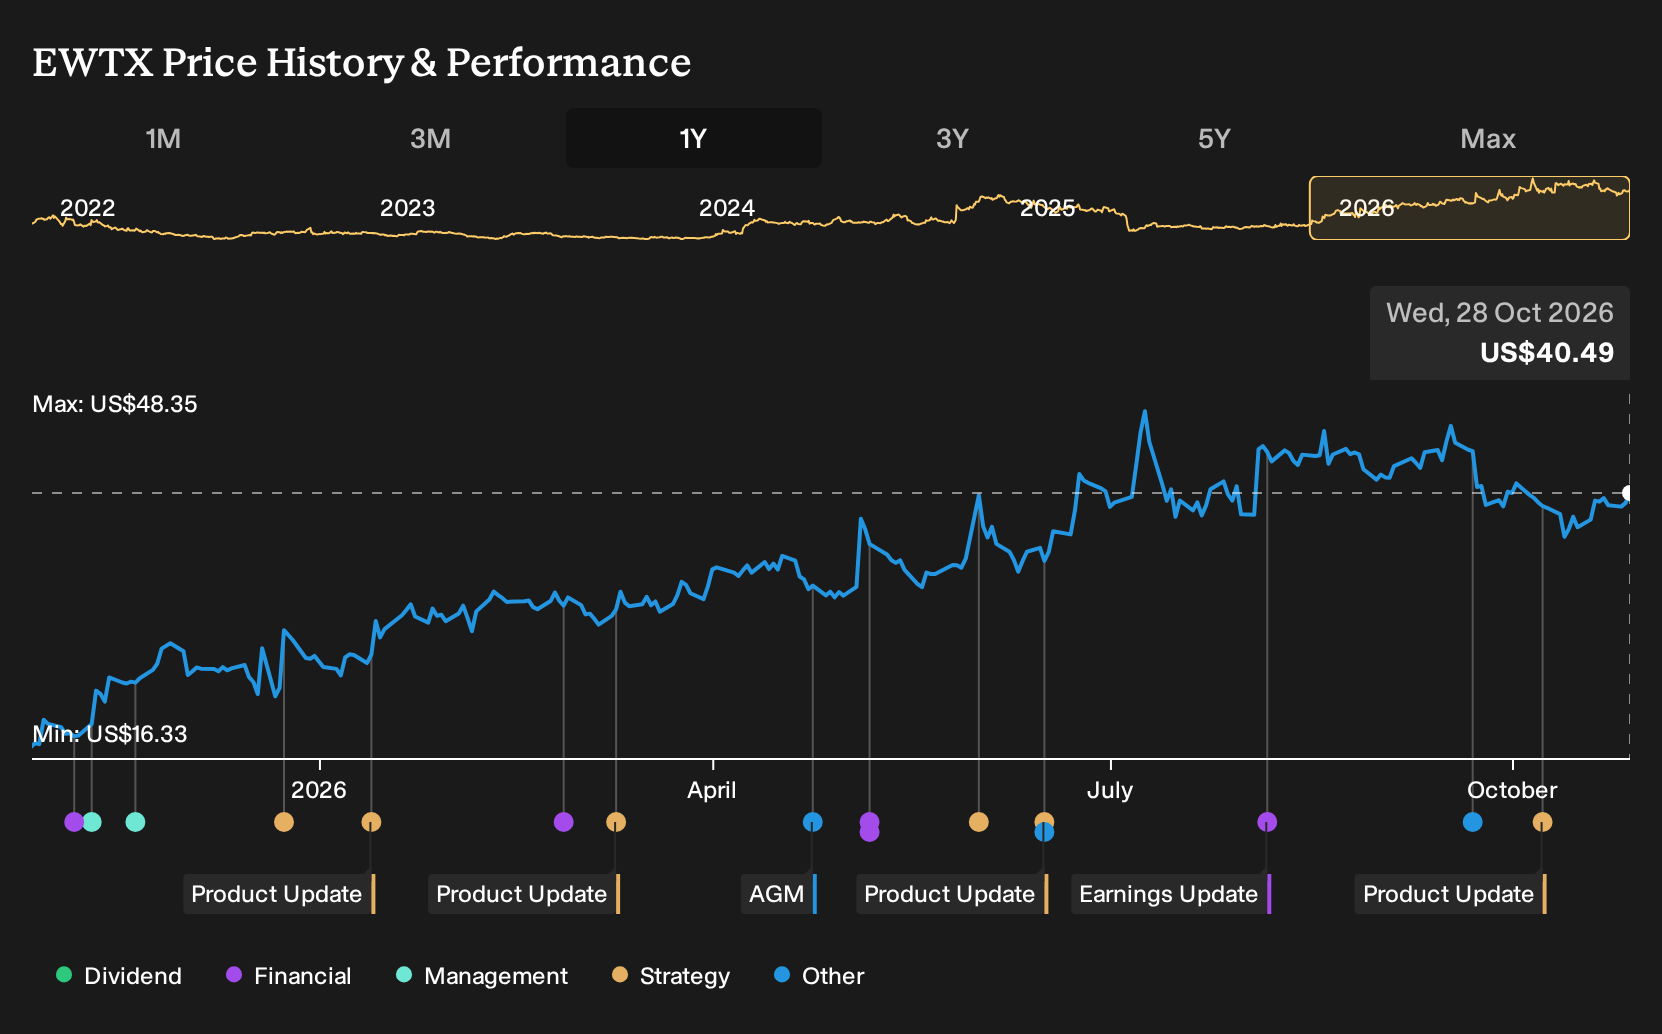
Uncover why Edgewise Therapeutics' fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a different angle on Edgewise Therapeutics, some bullish analysts had already been treating the reduced echo monitoring burden as a key upside catalyst. Before this Phase 3 design news, they were penciling in revenue of about US$378.5 million and earnings of roughly US$63.3 million by 2029. That is far above consensus and illustrates how sharply opinions can diverge. Use this moment to compare several viewpoints and decide which assumptions feel realistic to you.
Explore another Edgewise Therapeutics fair value estimate, including one that suggests there may be as much as 30% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Edgewise Therapeutics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Edgewise Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edgewise Therapeutics' overall financial health at a glance.
Looking For More Ideas Beyond Edgewise Therapeutics?
If you want to balance your view on Edgewise Therapeutics with fresh opportunities, the Simply Wall St Screener can help you line up stocks that match your risk tolerance, income needs, or quality focus in a structured way.
- For investors who care most about stability and capital protection, filter for resilient businesses using the 32 resilient stocks with low risk scores that score well on downside risk.
- If you want solid fundamentals to be your anchor, start with the list of solid balance sheet and fundamentals (24 results) and focus on companies that pair cleaner balance sheets with underlying earnings strength.
- Those hunting for potential mispricings can cast a wider net with the 19 high quality undiscovered gems and see which under followed stocks still screen well on quality and value signals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com