
Jersey Mike's Subs (JMKE) Unveils Buyback And Special Dividend, Is The Stock Too Expensive?
Jersey Mike's Subs (JMKE) just packed several shareholder moves into one week, pairing a $0.35 per share special dividend with a newly authorized $100 million buyback, alongside its latest quarterly earnings release.
Jersey Mike's Subs has had a choppy run since listing, with the 90 day share price return down 19.4% even after a 4.6% gain over the past month. The latest buyback and special dividend look like an attempt to rebuild momentum around a stock that some investors may see as underappreciated at a last close of $17.43.
Scan beyond Jersey Mike's Subs and see how other consumer-focused stocks are reacting to buybacks, special dividends, and choppy post-IPO trading by running the curated 19 high quality undiscovered gems.
Jersey Mike's Subs now trades at $17.43 while the average analyst target and intrinsic value estimate both sit meaningfully higher. Is that gap a genuine mispricing, or a fair reflection of recent losses and capital returns?
Price-to-Earnings of 101.7x: Is it justified?
Jersey Mike's Subs screens as good value against some fair value models, yet the stock changes hands at a steep P/E of 101.7x, well above many hospitality peers at a last close of $17.43.
The P/E ratio compares what investors are paying today for each dollar of reported earnings. For a fast casual franchisor like Jersey Mike's Subs, it effectively reflects how much of its future profit story the market is already pricing in, especially when net income is still relatively modest at $40.0m on revenue of $780.0m.
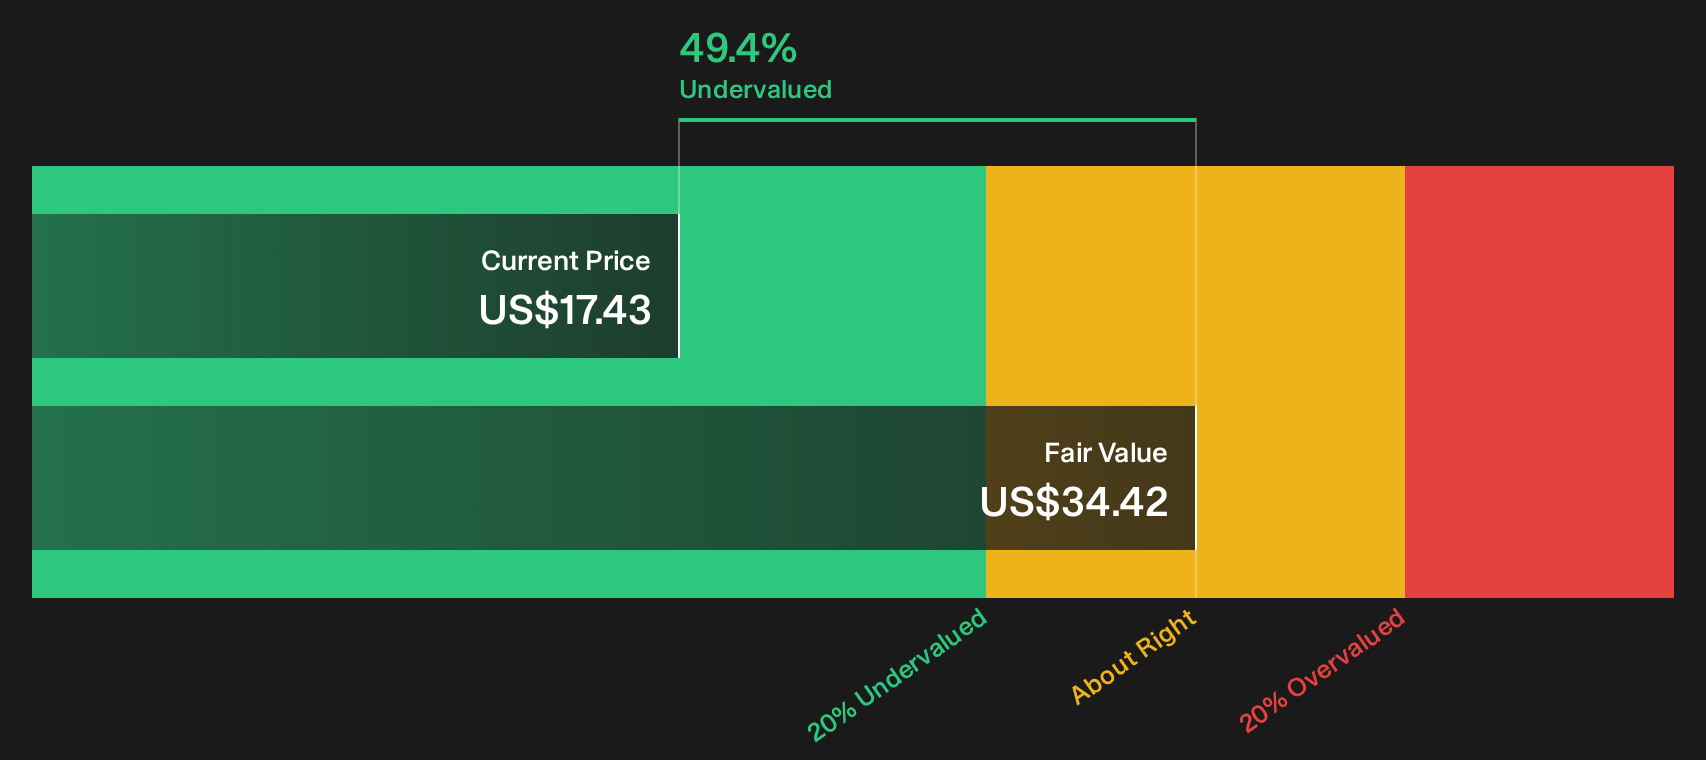
Here, the signals pull in different directions. On one side, the SWS DCF model estimate of future cash flow value sits at $34.42 per share, which is materially higher than the recent share price and implies valuation support based on projected cash generation. On the other side, the current 101.7x P/E is expensive compared both to the US Hospitality industry average of 20.3x and a peer group average of 44.1x. At the same time, return on equity of 0.9% and a forecast ROE of 6.8% remain low, alongside net profit margins of 5.1% that are slightly below last year.
The contrast is stark. Relative to industry and peer benchmarks, Jersey Mike's Subs trades on a very rich earnings multiple, suggesting the equity market is placing a heavy weight on forecast earnings growth of 38% per year even though revenue is projected to rise by 9.2% annually, which is slower than the wider US market. Those P/E gaps to both the 20.3x sector average and the 44.1x peer level are large, so any change in confidence around those projections could have an outsized impact on how that multiple evolves.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 101.7x (OVERVALUED)
Still, that rich 101.7x P/E can quickly look fragile if Jersey Mike's Subs underdelivers on forecast earnings growth or if sentiment shifts on its $5.40b valuation.
Find out about the key risks to this Jersey Mike's Subs narrative.
Another View: DCF Paints A Different Picture For Jersey Mike's Subs
The rich 101.7x P/E suggests Jersey Mike's Subs carries a heavy expectations premium, yet the SWS DCF model points in the opposite direction. On that cash flow lens, JMKE screens as undervalued, with an estimated future cash flow value of $34.42 per share versus the current $17.43 price.
That puts the stock at roughly half of the modelled value. This is a very different signal from the expensive P/E and the slower forecast revenue growth of 9.2% per year. For anyone weighing these mixed messages, the key question is which yardstick should sit at the top of your checklist when you look at JMKE.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jersey Mike's Subs for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mix of rich P/E and supportive DCF signals can feel contradictory, so it helps to move quickly and stress test the numbers yourself. To understand why some investors still see meaningful upside potential despite the recent volatility, review the 3 key rewards
Looking for more investment ideas beyond Jersey Mike's Subs?
If Jersey Mike's Subs has you thinking harder about price, quality, and risk, do not stop here. Your next strong idea could be one screener away.
- Target resilient potential by reviewing a 32 resilient stocks with low risk scores to help keep portfolio swings in check while you focus on the long game.
- Hunt for better value by scanning a 26 high quality undervalued stocks that combines solid fundamentals with prices that some investors may see as appealing.
- Build a sturdier core by filtering for a list of solid balance sheet and fundamentals (24 results) that could help anchor your portfolio when conditions get rough.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com