
Will Lower Earnings And Governance Pressure Change Hilltop Holdings (HTH) Narrative
- Hilltop Holdings reported third quarter 2026 results with net interest income of US$122.37 million, net income of US$24.9 million, higher net charge offs of US$1.16 million, a quarterly dividend of US$0.22 per share, and completion of a US$114.5 million buyback program.
- Corporate governance pressure increased as shareholder Gerald J. Ford urged Hilltop Holdings to separate the CEO and Chair roles due to perceived conflicts tied to ongoing litigation. This has sharpened the focus on how the leadership structure aligns with capital returns and earnings quality.
- This analysis reviews how Hilltop Holdings' investment narrative intersects with a lower earnings run rate and fresh corporate governance pressure.
Hilltop Holdings Investment Narrative Recap
To own Hilltop Holdings, you need to be comfortable with a slower growth banking and broker dealer story that is carrying a pressured mortgage arm. The third quarter showed net interest income of US$122.37 million alongside lower net income of US$24.9 million, so the near term debate stays centered on earnings resilience rather than expansion.
The key short term catalyst is whether PlainsCapital Bank and HilltopSecurities can keep offsetting ongoing PrimeLending drag while credit costs remain contained. Net charge offs of US$1.16 million, higher than a year ago, keep portfolio quality in focus as a practical risk, though the absolute level remains modest for now.
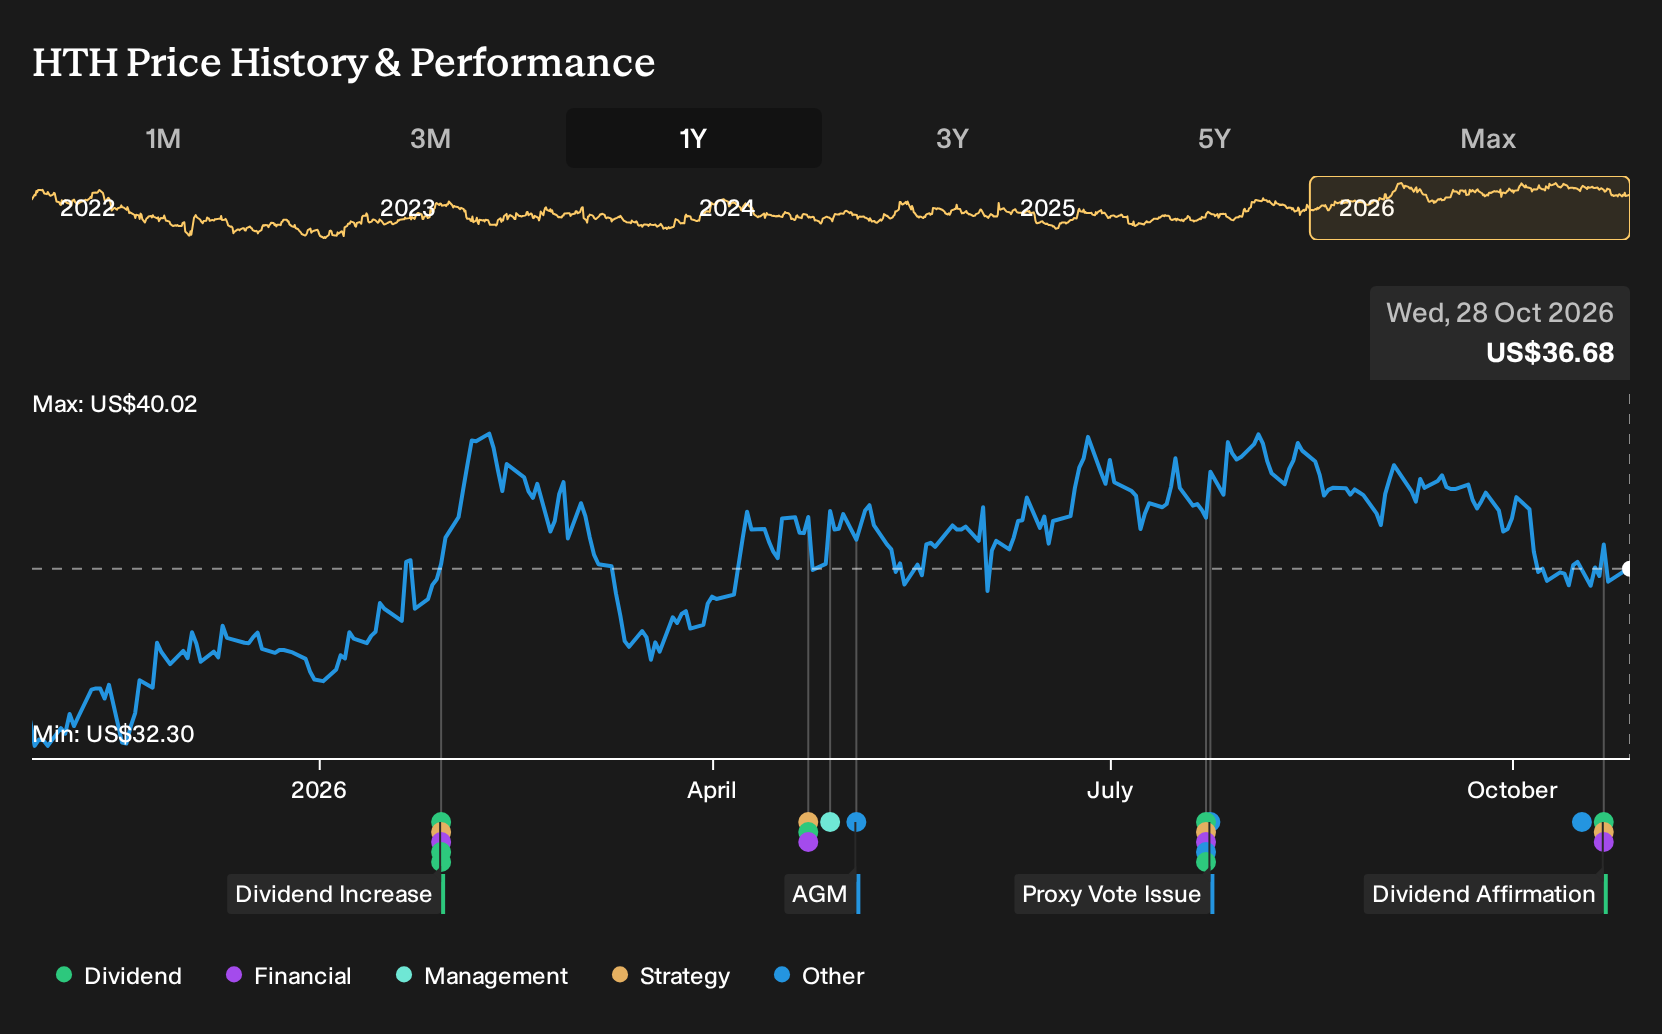
The quarterly dividend affirmation at US$0.22 per share is the most relevant announcement for this set of results because it directly ties capital returns to the current earnings power. You can read that payout alongside prior commentary that Hilltop Holdings pays a reliable 2.4% dividend, which many investors treat as part of the core thesis.
With earnings under pressure and net charge offs moving up from US$282,000 a year ago, the dividend decision puts execution risk in sharper relief. It keeps attention on how effectively management manages costs, credit and loan growth while also returning cash, and how any future shifts in that balance might act as either a support or a drag on the stock’s near term catalysts.
What The Analyst Forecasts Assume For Hilltop Holdings
Hilltop Holdings' published consensus puts revenue at US$1.3b and earnings at US$119.8 million by 2029, based on 1.0% yearly revenue growth and an earnings decline of US$42 million from US$161.8 million today.
Uncover why Hilltop Holdings' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$23.66 and US$41.67, so retail opinions on Hilltop Holdings already span a wide gap. When you set those views against rising net charge offs, ongoing buybacks, and the affirmed dividend, you can see why investors may want to explore several contrasting viewpoints.
Explore another Hilltop Holdings fair value estimate, including one that suggests potential upside of up to 14% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Hilltop Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hilltop Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hilltop Holdings' overall financial health at a glance.
Looking For More Hilltop Holdings Investment Ideas?
Once you have a view on Hilltop Holdings, it can help to line it up against other opportunities with different income profiles, balance sheet strength, or risk levels. A focused screen gives you a faster way to build that comparison set than flicking through tickers one by one.
- If you want income to do more of the heavy lifting, scan higher yielding candidates through 6 dividend fortresses and see how their payouts stack up against Hilltop Holdings' 2.4% yield.
- If capital preservation is your first filter, shape a shortlist using 32 resilient stocks with low risk scores so you can compare Hilltop Holdings with stocks that score well on resilience and downside risk.
- If you are hunting for quality at a price that still looks reasonable, build a watchlist using 26 high quality undervalued stocks to see which other companies pair solid fundamentals with a valuation that may appeal.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com