
Cimpress (CMPR) Could Be 35% Undervalued Following Its First Quarter Earnings Miss
Cimpress (CMPR) stock came into focus after the company posted first quarter results showing revenue of US$934.05 million, below analyst expectations, and a loss of US$0.11 per share from continuing operations.
The earnings miss has already fed into the tape, with Cimpress shares falling 7.4% on the day to US$74.79 and extending a 90 day share price decline of 21.02%. However, the year to date share price return of 13.91% and 3 year total shareholder return of 30.30% still point to earlier momentum that is now fading.
Scan how Cimpress stacks up against other potential turnaround stories by checking a curated set of 19 high quality undiscovered gems with strong fundamentals that have yet to catch broad market attention.
The latest drop forces a simple question: Are investors finally reacting to Cimpress's earnings wobble, or has sentiment swung harder than the business fundamentals justify as you weigh what the valuation now implies?
Most Popular Narrative: 35% Undervalued
Cimpress last closed at $74.79 while the most followed narrative pegs fair value at $114.50. The recent earnings miss sits against a framework that still sees meaningful upside if the long term plan holds together.
The main factor that needs to work in Cimpress's favor is successfully turning its current wave of efficiency projects, AI deployment and shared manufacturing investments into the cost savings, EBITDA growth and free cash flow conversion that management is targeting through fiscal 2028. The current valuation indicates that the market is not fully crediting Cimpress for its stated targets of at least $615 million of adjusted EBITDA, roughly 45% free cash flow conversion and lower net leverage by fiscal 2028, which could allow for share price appreciation if those outcomes are delivered.
See why 3 investors see Cimpress as 35% undervalued.
Result: Fair Value of $114.50 (UNDERVALUED)
Still, the Cimpress story can crack if efficiency projects fall short of the US$70 million to US$80 million savings, or if higher value print categories fail to scale online.
Find out about the key risks to this Cimpress narrative.
Another View: Cimpress Through The P/E Lens
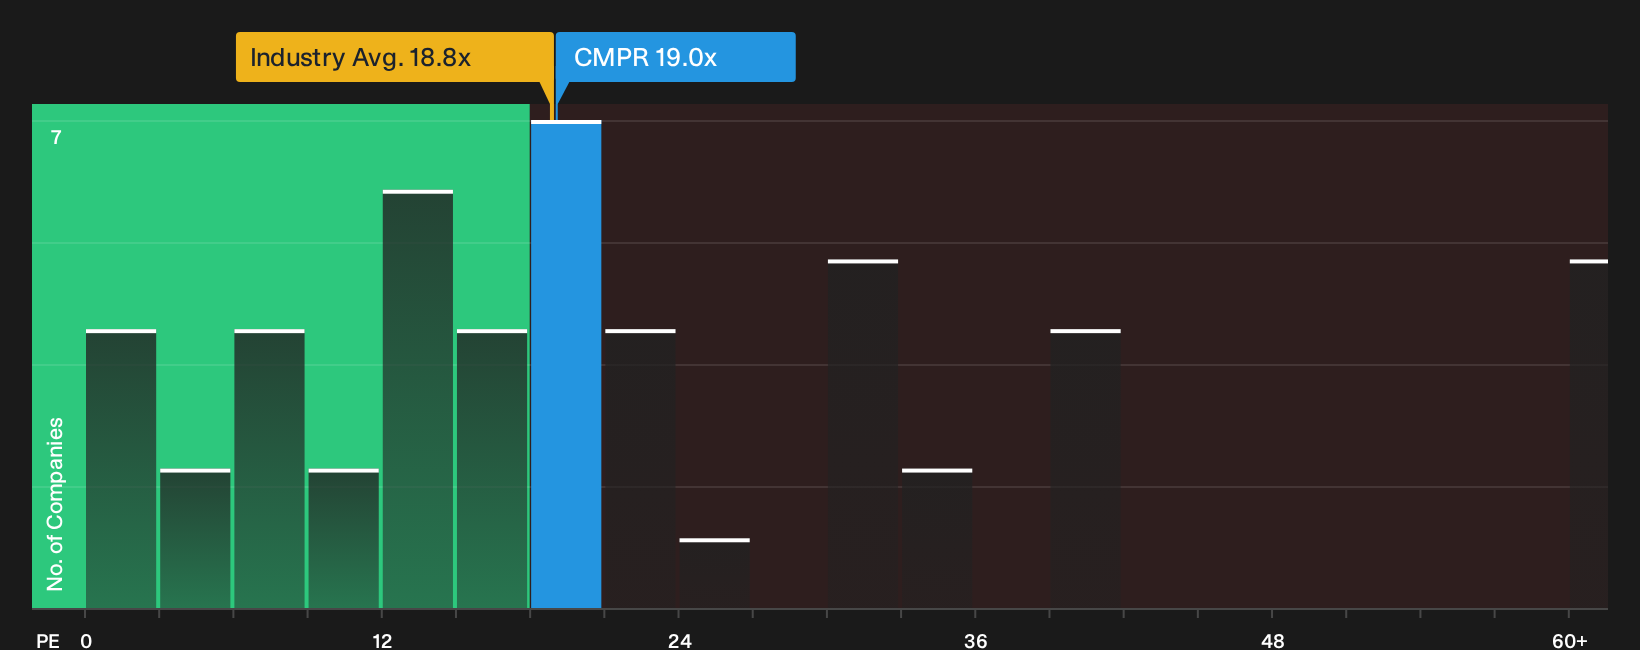
The first narrative paints Cimpress as meaningfully undervalued, yet the simple earnings multiple tells a tighter story. The stock trades on a P/E of 19x, slightly above the US Commercial Services average at 18.9x and well above a 14.8x peer group level, while the fair ratio sits higher at 20.8x.
That mix suggests the market is already paying a premium to peers but not fully matching the fair ratio that the model points to. You therefore need to decide whether this gap feels like upside potential or extra valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Cimpress leaves you unsure, move fast, pull up the data, and weigh both the upside and the red flags for yourself with 3 key rewards and 2 important warning signs.
Looking for more Cimpress-sized opportunities?
Do not stop your research at Cimpress. Broaden your watchlist with focused stock ideas built from clear filters so you can pressure test your next move with confidence.
- Target potential mispricings by scanning a curated list of companies that score well on quality and valuation with the 26 high quality undervalued stocks.
- Strengthen your downside protection by zeroing in on businesses with resilient finances through the list of solid balance sheet and fundamentals (24 results).
- Build a watchlist designed for staying power by focusing on companies with relatively low risk profiles using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com