
Earnings Beat Might Change The Case For Investing In Five Star Bancorp Stock (FSBC)
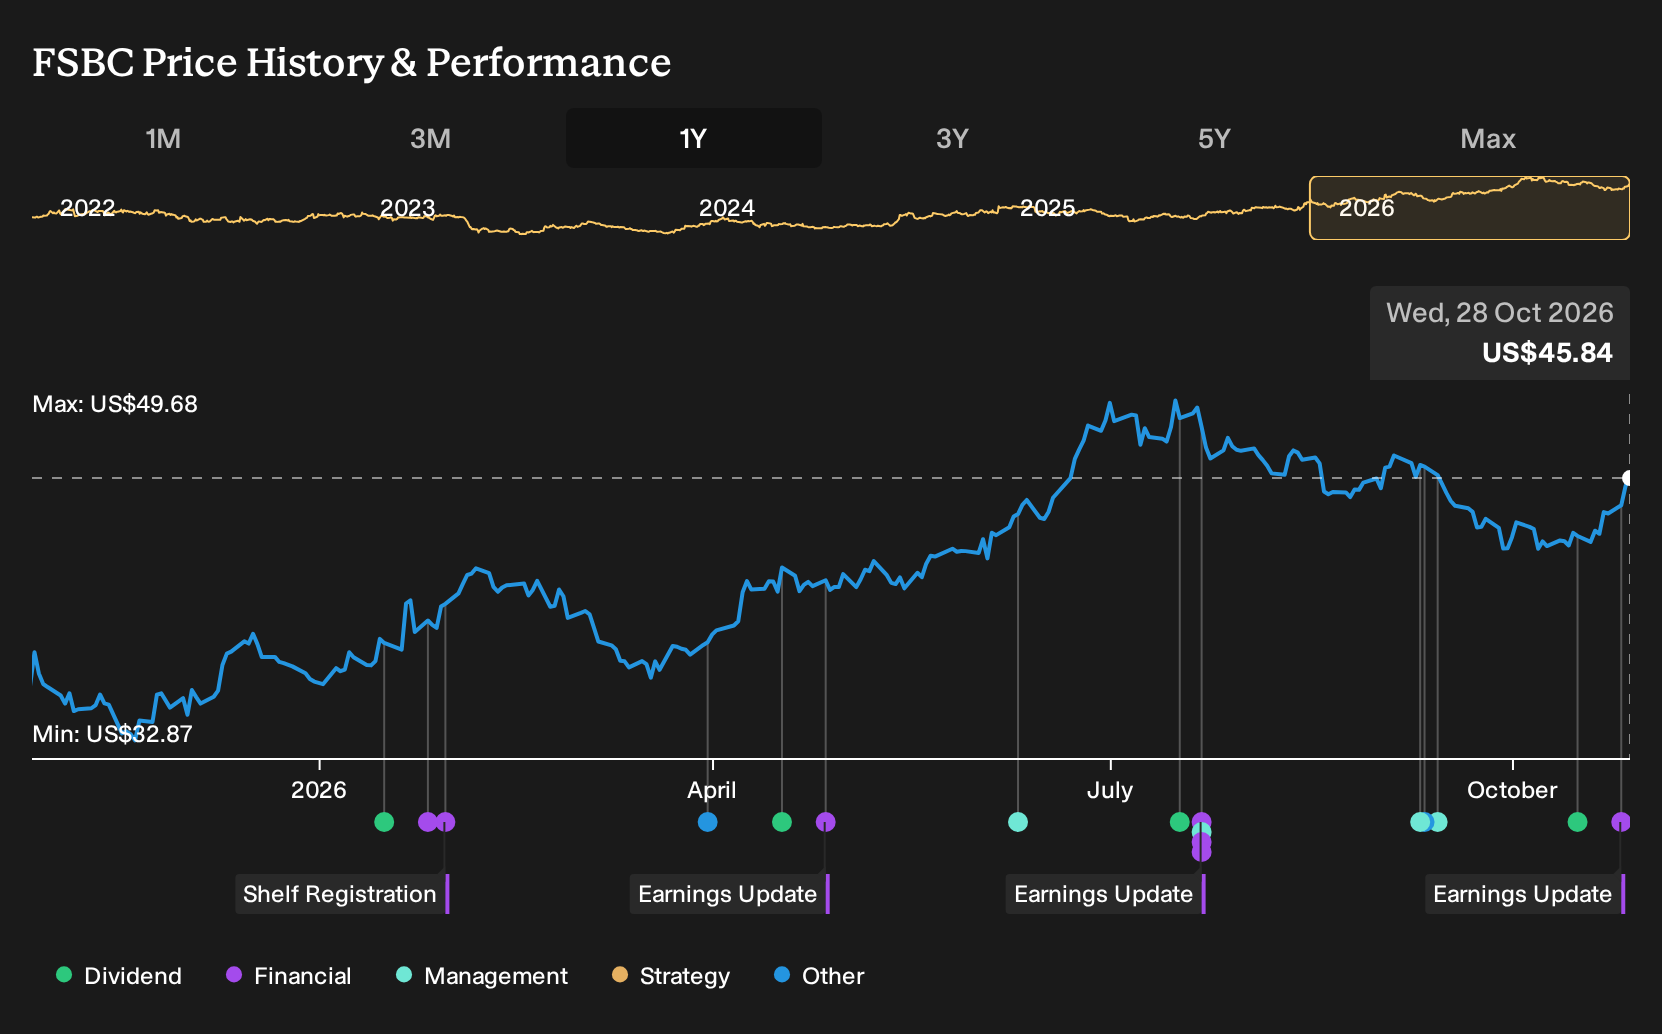
- Five Star Bancorp reported third quarter 2026 results with net interest income of US$50.93 million, net income of US$21.91 million and basic and diluted earnings per share from continuing operations of US$0.92, all compared with the same period in 2025.
- The board also affirmed a cash dividend of US$0.25 per share payable in November 2026. This, alongside higher quarterly earnings, highlights management’s focus on returning capital while continuing to fund the bank’s operating and expansion plans.
- Now the focus turns to how Five Star Bancorp’s investment narrative around core deposit growth and California expansion lines up with this stronger quarterly profitability.
Compare how Five Star Bancorp’s latest earnings and dividend stack up against other income focused opportunities by scanning our hand picked 6 dividend fortresses right now.
Five Star Bancorp Investment Narrative Recap
To own Five Star Bancorp, you need to believe the bank can keep turning its California expansion and relationship driven model into steady loan and deposit growth without eroding efficiency or capital. The latest quarter showed higher net interest income and earnings, which supports that narrative, but does not remove the execution risk around new markets and banker hires.
The key short term swing factor is whether core deposit growth keeps pace with the loan book while noninterest expenses stay in the guided range. The biggest risk remains that growth pushes capital ratios and forces fresh equity, which could dilute earnings per share. Recent results do not materially change that trade off yet.
The most relevant fresh data point is the third quarter 2026 earnings print. Net interest income was US$50.93 million, up from US$39.35 million a year earlier, with net income of US$21.91 million compared with US$16.34 million. Basic and diluted EPS from continuing operations reached US$0.92 versus US$0.77.
For investors, that earnings step matters because the whole Five Star Bancorp story depends on converting higher staffing and expansion costs into sustainably higher profitability while keeping credit quality and capital in check. Stronger quarterly profit supports the idea that recent hiring and market entries are gaining traction, although the risk of higher operating costs or future capital needs remains in the background.
Five Star Bancorp's current analyst setup points to US$285.2 million in revenue and US$111.0 million in earnings by 2029. That profile assumes revenue expands at about 19.4% per year and earnings rise by roughly US$39.0 million from US$72.0 million today to reach the 2029 consensus level.
Uncover why Five Star Bancorp's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently has 2 fair value views on Five Star Bancorp, ranging from about US$51.80 up to roughly US$84.02. That wide band shows how far opinions can spread before earnings and the recent dividend decision are fully absorbed, so treat it as a cue to compare several viewpoints rather than anchor on one number.
Explore another Five Star Bancorp fair value estimate, including one that suggests it could be worth just $51.80.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Five Star Bancorp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Five Star Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Five Star Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Five Star Bancorp?
If this Five Star Bancorp update has sharpened your view on bank earnings and dividends, use that same lens across the wider market. The Simply Wall St Screener lets you quickly sift through different types of stocks so you can compare income, quality and risk across a much broader opportunity set.
- For investors who care most about durable balance sheets and dependable fundamentals, start with this curated list of solid balance sheet and fundamentals (24 results) and see which businesses meet a higher quality bar.
- If your priority is limiting downside risk while still staying invested, check out a focused 32 resilient stocks with low risk scores that filters for companies with more resilient profiles.
- When you want to widen the search for potential future leaders that the market might not be pricing fully yet, scan through the 19 high quality undiscovered gems and compare their metrics side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com