
Canadian Stock Market Today: TSX Futures Edge Higher On BoC Hike And GDP Test
The Morning Bull - Canadian Market Morning Update Thursday, 29 Oct 2026
Canadian equities are set for a cautious but firmer open, with S&P/TSX 60 futures edging higher. The clear driver is the Bank of Canada’s fresh 25 bps rate hike to 2.5%, which is resetting risk appetite.
Policy makers raised the benchmark rate yesterday and flagged ongoing concern about persistent inflation linked to higher energy prices. With guidance pointing to the possibility of further tightening, investors are recalibrating how long borrowing costs could remain restrictive in Canada.
Higher policy rates typically lift funding costs for households and businesses. This can weigh on interest sensitive parts of the market while rewarding companies with strong balance sheets. The new 2.5% setting also feeds directly into government bond yields, influencing equity valuations that rely heavily on discounted future cash flows.
The open now hinges on whether the inflation narrative justifies more action from the Bank of Canada or not. Upcoming domestic GDP data on Friday presents a clean test of that judgment and could either reinforce or challenge today’s early rate driven tone.
Stocks to Watch Before the Opening Bell
Athabasca Oil (ATH)
Athabasca Oil agreed to be acquired by Cenovus Energy in a $5.7 billion cash and share deal, alongside reporting a 20% quarter over quarter production increase. The takeover includes the Leismer expansion, which targets 40,000 bbl/d by the end of 2027. Readers should watch for closing conditions and any updated project timelines.
Air Canada (AC)
The Competition Bureau warned that Air Canada’s expanded joint business arrangement with United Airlines would likely reduce competition on 10 Canada U.S. routes. Regulators flagged a risk of higher fares on most of those corridors. Attention now turns to the Transport Minister’s public interest review, since that decision will determine whether the partnership proceeds.
GFL Environmental (GFL)
GFL Environmental reported Q3 revenue and adjusted EBITDA ahead of expectations and raised full year 2026 guidance for the third time. Management cited 7.4% organic revenue growth and over 115 basis points of underlying margin expansion. A Special Committee is reviewing unsolicited going private proposals, with a final bid deadline set for November 9.
Top Movers
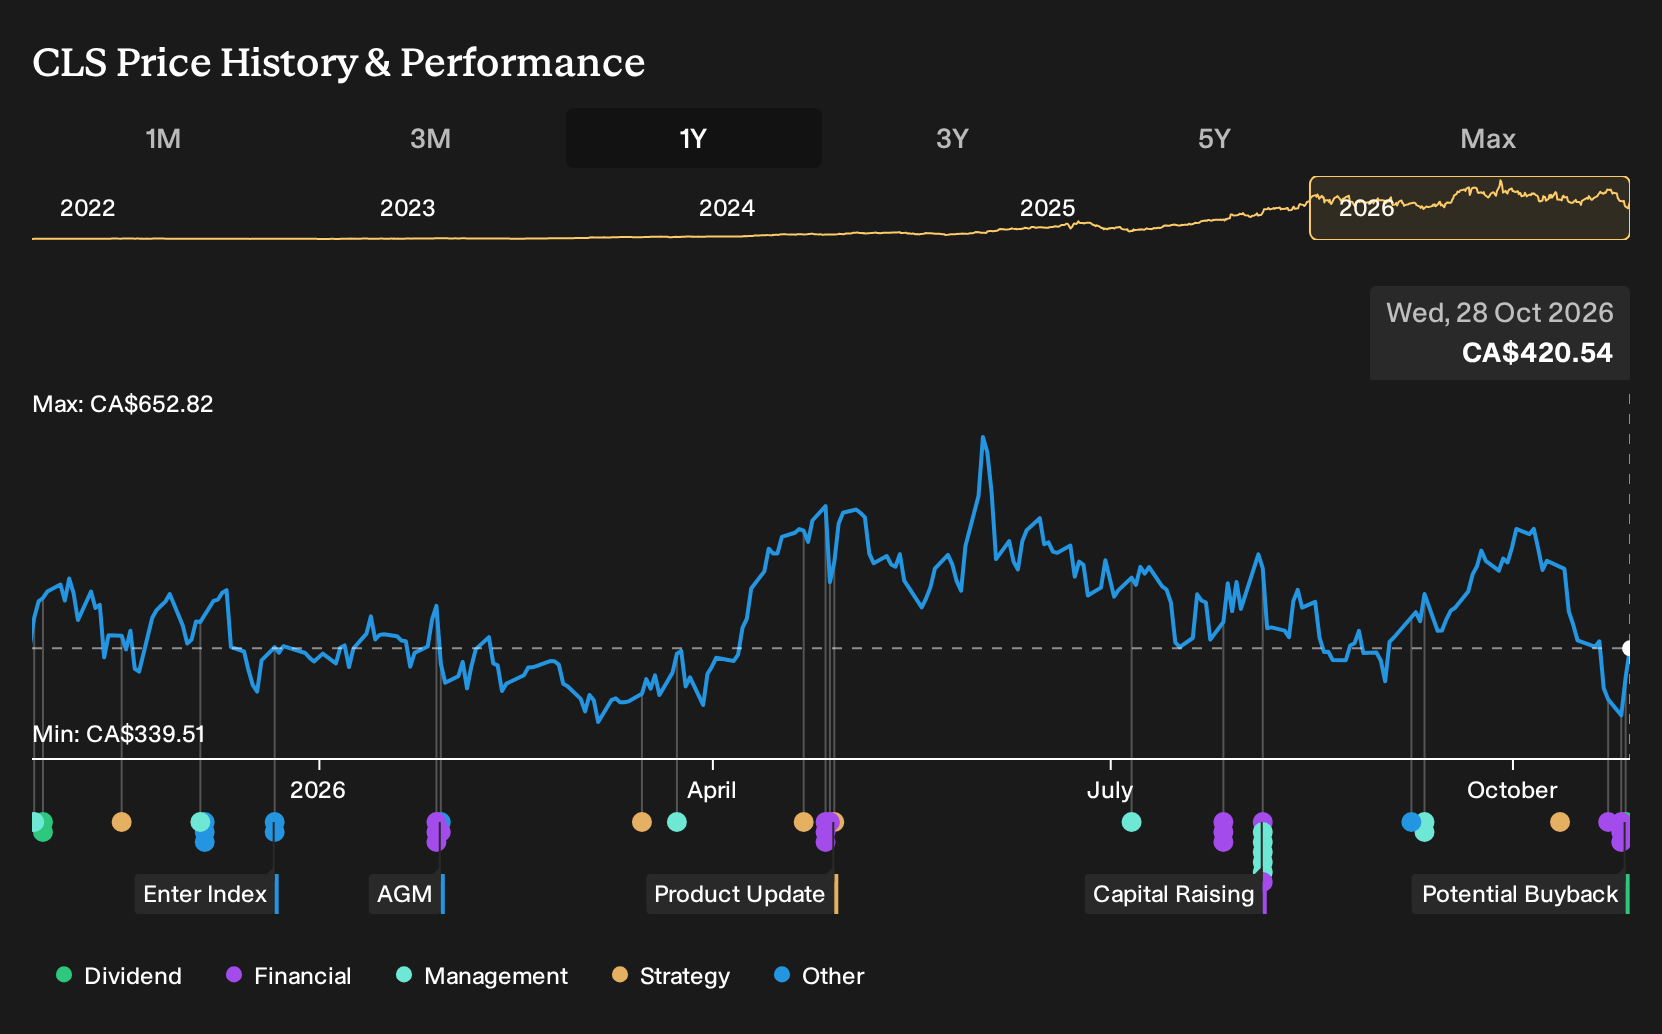
- Celestica (TSX:CLS) jumped 8.29% after strong Q3 results, higher guidance, commentary on AI demand, and fresh analyst target hikes.
- Aecon Group (TSX:ARE) gained 5.97% as investors focused on its large infrastructure backlog and its upcoming Q3 2026 financial update.
- Precision Drilling (TSX:PD) advanced 5.45% following a Q3 earnings release and a recent analyst upgrade with a higher price target.
Top Losers
- Extendicare (TSX:EXE) declined 2.23% following a recent CIBC price target lift that came after earlier Q3 results.
- West Fraser Timber (TSX:WFG) fell 2.11% after Q3 results and mill curtailments tied to weak wood products demand.
- FirstService (TSX:FSV) declined 2.08% despite positive news on luxury residence designations and new management mandates.

On The Radar
Canadian investors face a tight cluster of domestic GDP data and heavyweight TSX earnings that land alongside US inflation gauges and GDP, all hitting just after the Bank of Canada’s latest rate hike.
- Canada GDP MoM, Fri 30 Oct. The August print, with consensus at 0.2% after a flat prior month, will shape views on how restrictive a 2.5% policy rate is for growth sensitive areas of the Canadian market.
- Canada GDP MoM Prel, Fri 30 Oct. The early read for September, with a 0.1% forecast, will cue investors on whether the Bank of Canada can keep emphasizing inflation risks without adding pressure to already rate exposed domestic sectors.
- US Core PCE Price Index MoM, Thu 29 Oct. A September outcome above the 0.3% consensus would reinforce the Fed’s inflation concerns and could support US$ strength, often a headwind for Canadian exporters and gold producers.
- US GDP Growth Rate QoQ Adv, Thu 29 Oct. The first Q3 estimate, with consensus at 3.2% against a prior 2.2%, will influence expectations for global demand that matter for Canadian resource, manufacturing, and rail stocks.
- Big TSX financials and resources earnings, Tue 3 Nov to Wed 4 Nov. Results from Great-West Lifeco, Sun Life Financial, Manulife Financial, Suncor Energy, Brookfield Renewable Partners, WSP Global, and others will put margins and guidance in focus for Canada’s dividend heavy financial and commodity groups.
Sector & Industry Watch
Financials: Higher prime reshapes borrowing math
Financials has inched higher over the past week, with Banks showing slightly firmer 7 day gains on top of solid 1 year returns versus the CA Market. Every major lender has moved prime to 4.70% after the Bank of Canada rate hike to 2.5%, so variable mortgages, credit lines, and many business loans are now priced off a higher base.
The single data point that can shift the tone is Friday’s Canada GDP report, because a surprise on growth would feed directly into how investors think about loan demand and credit risk across Financials.
Energy: Busy producers despite weekly pullback
Energy and Oil and Gas have slipped modestly over the last seven days, although that softer 7 day patch follows a firm 30 day run and strong 1 year readings. Companies such as Athabasca Oil, Cenovus Energy, Whitecap Resources, and Precision Drilling are pushing ahead with takeovers, higher budgets, and heavier winter drilling plans, which keeps cash flow and balance sheet quality in focus.
For Energy, the clearest near term catalyst is Canada’s August GDP release on Friday, since it will help show how much of current national output is tied to resource heavy activity.
Real Estate: Rate sensitive trade still under strain
Real Estate has fallen over the past week after a flat 30 day spell, and both year to date and 1 year returns sit below the CA Market. The move to a 4.70% prime rate raises carrying costs for mortgages and commercial loans, which matters if you hold REITs that rely on debt to refinance properties or fund acquisitions, even as Primaris REIT and Morguard report property level news.
The domestic release to watch is Canada’s monthly GDP on Friday, because any sign of softer activity can influence views on rent growth, occupancy, and financing conditions across Real Estate.
Materials: Miners weak while projects advance
Materials is down sharply over the last month, with a further drop over the past seven days, and Metals and Mining has declined even more across both periods. Yet companies from West Fraser Timber to PMET Resources, Cymat Technologies, and a long list of explorers continue to push drilling, mill decisions, and pre feasibility work that often requires new capital.
The key swing factor is Canada’s GDP report on Friday, since a stronger or softer read on growth can influence how patient investors feel with longer dated mining and forestry projects in Materials.
Tech: AI projects contrast with past slump
Tech has posted a small positive 7 day move while still showing a weaker year to date return, and Semiconductors remain under heavy pressure across every period given. At the company level, HIVE Digital Technologies has lined up about $129m of fixed rate funding for a domestic AI GPU cluster, while Docebo and Cannabix Technologies are rolling out new AI linked tools and platforms.
The next meaningful check for Tech is the upcoming round of Canadian earnings calls, where comments on software budgets, AI projects, and hardware spending can help you judge how well recent share performance aligns with business trends.
Identify The Next Market Leaders
With prime now at 4.70% after the Bank of Canada hike to 2.5%, income focused investors can start with this list of 3 dividend fortresses
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com